
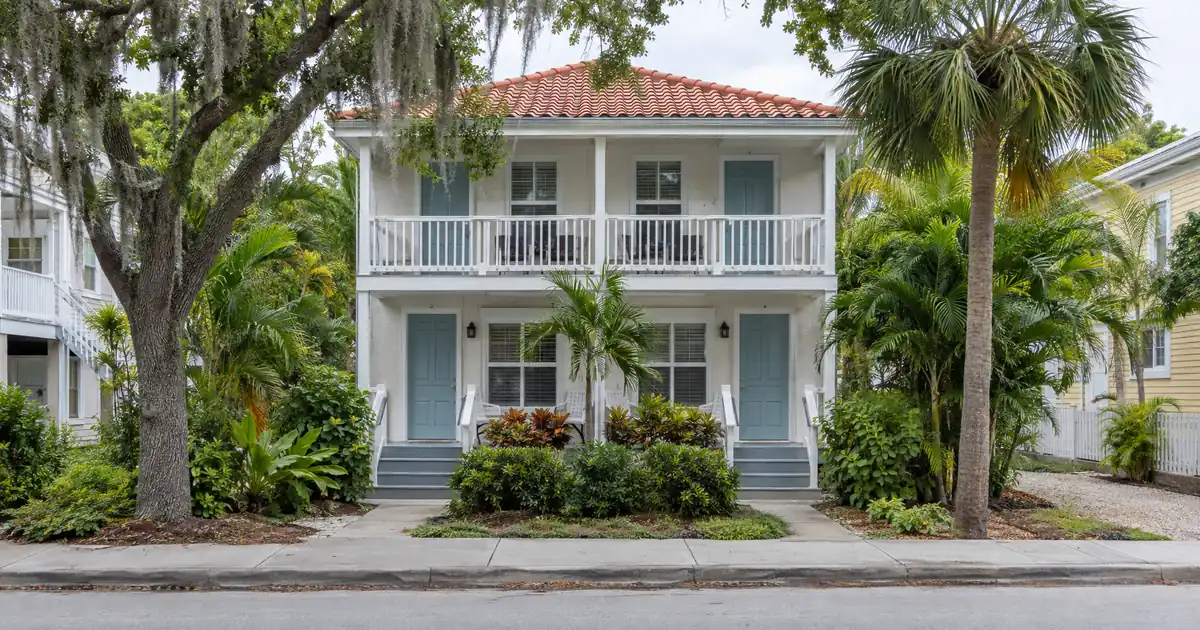
Redfin’s trailing three-month data puts the Key West median sale price at $1.3M, up 28.0% year over year, while price per square foot fell 9.9% over the same stretch. Prices up and per-foot value down: larger, higher-end sales are skewing the headline. That split shapes any DSCR cash out refinance in Key West, Florida, because the median tells you very little about what a lender’s appraiser will see on a workforce duplex.
The Short Version: A DSCR cash-out refinance in Key West, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation. The island’s price base makes this a multi-unit conversation: single-family rents rarely cover a seven-figure basis, while stacked units on Stock Island and in New Town can.
DSCR Cash-Out Calculator
Run the cash-out numbers in Key West, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV tops out at 75%, with about six months of ownership required first.
- Stock Island’s 280-unit Wrecker’s Cay leased fully, with roughly 230 people on a waitlist (Keys News).
- Old Town, Truman Annex, and Casa Marina behave as appreciation holdings, not coverage plays.
- Days on market stretched to 148 from 97, so appraisal comps deserve attention (Redfin).
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that works with Key West, Florida investors to place DSCR financing through wholesale lenders reaching 41 markets — 40 states plus Washington, D.C. This article skips purchase mechanics. It assumes you already own the asset and want to know how much equity the numbers will let you pull, and where that capital goes next.
Key West Market Snapshot
A quick read on the Key West investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.3M median (Redfin) |
| Typical rents | 1br rent $2,865 (2015: ~$1,750) (Multifamily Dive) |
| Population | 25,720 population (U.S. Census Bureau / Census |
| Employment | ~5,500 employees/dependents (WLRN) |
Where Equity Extraction Actually Pencils
Small multifamily on the island’s lower-basis side is where cash-out math holds up. Single-family product struggles almost everywhere in Key West on rent-to-value, while two-to-four-unit product in Stock Island, New Town, and Midtown can stack enough gross rent to support a meaningful refinance balance without leaning on anything but long-term leases.
The arithmetic is unforgiving on the single-family side. Rent aggregators disagree, but every version of the data points the same way: Rentometer shows one-bedrooms in the $1,500-$2,000 band and two-bedrooms near $3,500, while Zumper reports a $3,300 average and Apartments.com reports $2,548. Treat all of these as directional, since Key West’s rental inventory is thin and the datasets are noisy. Against a home value near $1.1M per Zillow, those rents don’t carry a full-obligation coverage ratio at any leverage a lender will meaningfully entertain.
Stack the units and the picture changes. RentCafe reports that 51% of Key West housing is renter-occupied, 62% of rental units sit in buildings under 50 units, and 15% are single-family rentals. The rental stock is small-plex by nature, which is the property type DSCR underwriting handles best. One on-market example: BeInKeyWest lists a triplex with three 3-bed, 2-bath units and a rent roll of $187,200 a year. Property-level income like that is what a lender reviews, and a single-family house at a similar price point can’t produce it.
Stock Island: The Workforce Anchor
Stock Island is the strongest long-term-rental submarket in the data, and the reason is documented absorption, not sentiment. Wrecker’s Cay Apartments delivered 280 units, described as the largest workforce housing development in the Florida Keys in more than 50 years, and per Keys News it was 100% leased on completion with a waitlist of about 230. REBusinessOnline published unit rents of $2,460 for one-bedrooms and $2,769 for two-bedrooms. That is a professionally underwritten benchmark you can hold your own duplex or triplex rents against, which beats a citywide average that blends Old Town luxury with workforce stock.
Tenant demand here rests on three legs that don’t depend on the visitor cycle. The College of the Florida Keys has its main campus on Stock Island and reported 920 undergraduates in fall 2022. Lower Keys Medical Center, a 167-bed acute-care hospital, sits on College Road beside the campus. And Naval Air Station Key West brings roughly $1 billion a year into the local economy with about 5,500 employees and dependents on base, per WLRN. Military-housing guidance also points affordability-minded base families toward Stock Island and New Town.
One caution on scale: the college is small, and the hospital’s headcount couldn’t be confirmed from an official source. The Navy and workforce-housing evidence carries the thesis. The enrollment number doesn’t.
New Town and Midtown: The Quiet Basis Advantage
New Town and Midtown carry lower acquisition bases than Old Town or Casa Marina, which improves rent-to-value before you stack a single unit. Less postcard, more paycheck. For an investor sitting on a small multifamily property here, the refinance case usually rests on rents that have reset upward while the original basis stayed modest.
The honest wrinkle is the workforce duplex. Modeled with two units each renting near the citywide average, the coverage number comes out close to break-even, around 1.00x including taxes and insurance. For most standard programs, 1.00x is the benchmark, though exact eligibility depends on lender guidelines, credit profile, reserves, and property review. A duplex landing right at that line has options a lender would review: lower leverage than the 75% ceiling, an interest-only structure, or a sub-1.00 program that typically asks for stronger compensating factors and more cash retained. Those are paths to price out, not outcomes to assume.
Skip the Postcard Neighborhoods
Old Town, Truman Annex, and Casa Marina are equity plays, not coverage plays, and an owner should walk in expecting that. A local brokerage’s half-year report showed Truman Annex sales averaging $2.35M across 8 properties, and Bahama Village averaging $1.1M across nine sales at $1,163 per square foot, roughly 10% below comparable Old Town and Truman Annex pricing per John Parce Real Estate.
At those bases, a long-term lease doesn’t clear a full-obligation coverage ratio, so DSCR cash-out is a poor fit for those neighborhoods unless the property is a multi-unit historic conversion. Legal 2-to-6-unit conversions do exist in Old Town. If you hold one, the same unit-stacking logic applies, but underwrite it as a small multifamily asset, not a landmark house. (Sunset Key, the private-island enclave, isn’t a standard DSCR play at all.)
Reading the Appraisal Risk
Thin comps are the real constraint on how much equity you can extract, and Key West’s own sales data flags it. Redfin shows homes selling after 148 days on market against 97 a year earlier, and an aggregator drawing on Redfin data, RealEstateAgentNearMe, cites 6.6 months of inventory and about 154 days to sell, characteristics of a buyer’s market. Yet the median keeps climbing.
That pairing is a classic thin-comp warning. A rising median built on fewer, slower, higher-end sales can make an appraiser cautious about aggressive valuations, even where the headline trend looks generous. The stronger play might be assuming a conservative appraisal and treating anything above it as upside. Honestly, this is a genuine toss-up for owners with a high original basis: the trend favors extraction, but the transaction depth argues for patience.
The Cash-Out Structure, Step by Step
Three constraints set the equity you can access: 75% LTV, about six months of ownership, and coverage at or above the standard 1.00x benchmark. How the cash-out works is straightforward. The lender measures rent used for lender review against full monthly obligations (principal, interest, taxes, insurance, and any HOA dues), and the 75% ceiling applies to the appraised value. The 80% figure you may see for purchases doesn’t carry over. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
- Seasoning: about six months from title recording before cash-out is available.
- Credit: tiers commonly start at a 620 floor, with better terms at 660, 680, and 700.
- Reserves: typically about six months of PITIA, stepping up to roughly nine months on balances above $1.5M.
- Loan size: standard programs run up to $3M, which covers most Key West small multifamily.
Equity is not a guaranteed cash figure. It depends on rent used for lender review, obligations, reserves, and that 75% ceiling, all subject to lender guidelines and program terms. If the property is titled in an LLC, financing is available subject to lender program eligibility. For a broader comparison of programs, see the guide “Where DSCR and Conventional Diverge”, and for the mechanics behind qualification, the guide “What Is a DSCR Loan”.
Picture an investor who bought a low-basis triplex on Stock Island more than six months ago and has since re-leased all three units at current market rents. The refinance question comes down to three ratios: the existing balance against 75% of the new appraised value, full-obligation coverage against the 1.00x benchmark, and post-closing reserves against the six-month expectation. Get any one wrong and the cash-out shrinks or disappears.
What the Deal Desk Sees in Markets Like This
In supply-locked island markets, the file friction is rarely the borrower. It’s the valuation and the insurance line. Cleaner files from a documentation standpoint tend to arrive with current leases, a rent roll that ties to the leases, and an insurance quote refreshed before submission, since coverage math built on a stale quote is the most common source of late repricing. Where some DSCR platforms require tax-return review despite the DSCR label, a property-level file lets the lender focus on the asset’s income, though the exact documentation package still varies by lender.
Where the Proceeds Go
The strongest use of Key West cash-out proceeds is often outside the island. Key West is a finite island, 1.5 miles wide and 4 miles long, with essentially no vacant land left to develop, and Census Reporter puts the city population at 25,720 across 5.6 square miles. Supply can’t expand, which supports the holdings you keep. It also makes the next acquisition here expensive.
Many owners in this position use proceeds toward a second small multifamily deal, either on Stock Island or on the mainland, where basis is lower and coverage is easier. You can also review investor refinance options for existing holdings, and Lendmire’s page on DSCR loans in Florida covers the statewide program picture. If you’d like to talk through a specific Key West file, reach the team at 828-256-2183 or connect with Lendmire. Current local rules, taxes, and insurance are worth confirming with qualified local professionals before you commit.
The Next 6-24 Months
Expect the bifurcation to persist. Luxury-tier pricing can keep the median elevated while slower absorption (148 days on market and 6.6 months of supply) makes appraisals more selective, and workforce-tier multi-unit product on Stock Island and in New Town should hold its footing because it rests on Navy, hospital, and college tenants rather than tourism. Owners who season a low-basis small multifamily property and re-lease at market rents are best positioned to extract equity. Owners waiting on a single-family house to bridge the coverage gap will likely keep waiting.
Frequently Asked Questions
How do you qualify for a DSCR loan in Key West?
Qualification centers on the property’s rent relative to its full monthly obligation, with 1.00x the common benchmark. Beyond that, lenders typically review credit (a 620 floor with better tiers at higher scores), about six months of reserves, and the property itself. In Key West, small multifamily usually clears more easily than single-family. Final eligibility is subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Key West, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for a cash-out refinance on a Key West investment property?
Expect a 75% maximum LTV, about six months of ownership measured from title recording, coverage at or above 1.00x, and reserves of about six months of PITIA (about nine above $1.5M). Loan sizes run up to $3M on standard programs. Manufactured homes, log homes, and barndominiums fall outside these programs.
Why do Old Town and Truman Annex rarely work for DSCR cash-out?
Their pricing is far above what long-term rents can carry, so full-obligation coverage falls short. Truman Annex sales averaged $2.35M in a local brokerage’s half-year report, and those neighborhoods function as appreciation holdings. Multi-unit historic conversions are the exception, underwritten as small multifamily.
How does DSCR program review differ from a bank’s approach in Key West?
Lendmire arranges DSCR investor programs and eligibility is commonly reviewed around property-level rent rather than personal income documentation. Banks lean on traditional personal-income documentation and debt-to-income, which penalizes investors with several financed properties. Subject to lender guidelines, files here can be structured around the asset itself.
Does Stock Island’s workforce housing supply threaten rents on smaller properties?
The evidence so far points the other way. Wrecker’s Cay leased fully with a waitlist of roughly 230, and it was described as the largest workforce project in the Keys in over 50 years, a one-time event on a finite island. Still, a large new property can set the rent ceiling for nearby small-plex units, so benchmark against its published $2,460 and $2,769 unit rents.
About Lendmire
Lendmire — NMLS# 2371349 — is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. DSCR eligibility is commonly reviewed by the lender on property-level rent rather than personal income documentation, subject to lender guidelines, and the brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Key West Housing Market
2. Keys News: Wrecker’s Cay Project Is Complete
4. U.S. Census Bureau / Census
6. Rentometer
7. Zumper
9. Zillow
10. RentCafe
11. BeInKeyWest
12. REBusinessOnline: Wrecker’s Cay Apartments
15. a 2025 Scotsman Guide Top Mortgage Workplace
16. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Longboat Key · Cash Out Refinance Investment Property Doral Florida · Cash Out Refinance Investment Property Dania Beach Florida
Guides: Investment Property Cash-Out Refinance in Key West, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.