
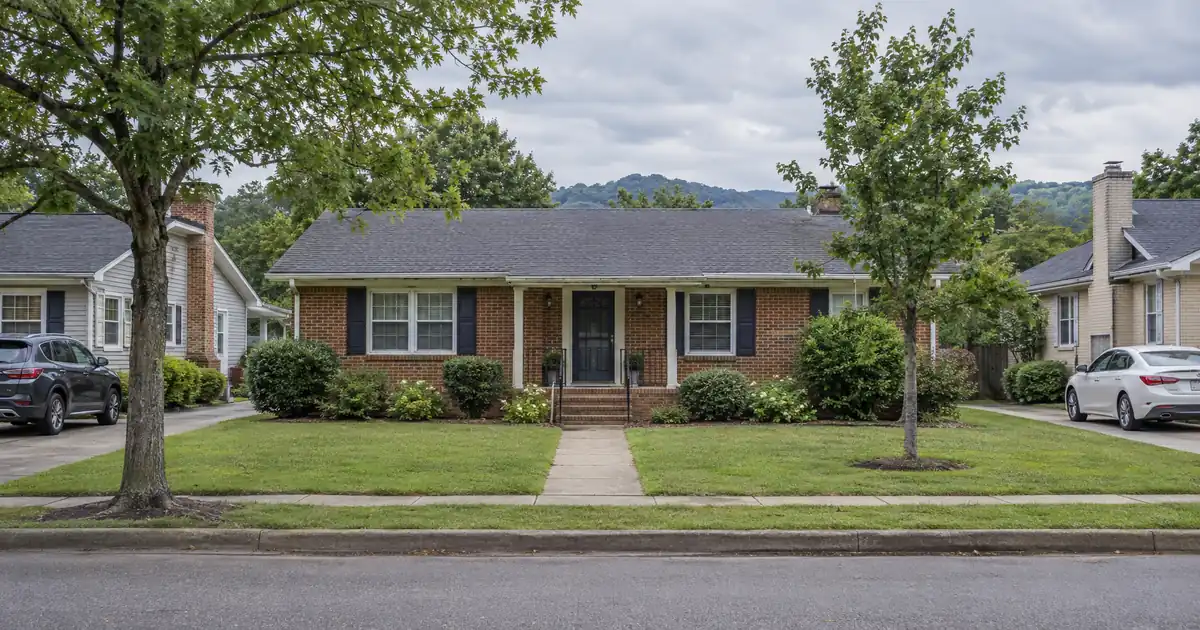
Picture an investor holding a four-bedroom house in a lake-adjacent Lakeland subdivision, bought at $450,000 a few years back and rented out ever since. The tenant pays on time, and the property has been a quiet, low-drama hold. Now the investor wants that equity working on the next deal and calls a broker. The first question isn’t “how much can I pull?” It’s “does the rent cover the new payment?” In Lakeland, that second question decides everything.
The house is a modeled example, not a listing. It is priced near the local value index, which makes it a fair stress test. This article covers what a DSCR cash-out refinance looks like in Lakeland, Tennessee: where the equity comes from, why coverage is the binding constraint, and how to structure around it.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lakeland, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges investor loans across 40 states plus Washington, D.C., 41 markets in all. Lendmire’s team works these files as a broker, not a lender, and every lender decision is subject to program guidelines.
The Quick Read:
A DSCR cash-out refinance on a Lakeland, Tennessee rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds capped by a 75% LTV ceiling and by a lender-ordered appraisal, so coverage and appraised value, not purchase history, set the outcome. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
- Zillow’s home value index sits near $448,503, down 1.1% over the past year.
- Gross rent runs roughly 0.47–0.51% of value monthly, so full-PITIA coverage is thin.
- Cash-out typically needs about 6 months of ownership from title recording, subject to lender guidelines.
- Single-family is the rental product here. Multi-unit stacking isn’t realistic.
- Lower LTV or a stronger structure usually decides whether the file clears.
Where the Equity Comes From
Don’t count on price gains in Lakeland. Zillow’s index is down 1.1% year over year, and NeighborhoodScout shows trailing appreciation of about -1.22%. Movoto reports a September median list price near $565,000, down 3% from a year earlier. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
If you bought at a good basis, your equity is mostly a purchase-discount or principal-paydown story. It is not a market-lift story. That changes how a cash-out should be planned. The lender’s appraised value drives proceeds, and the appraiser has to work with what has actually sold.
The sources disagree on the citywide median. Zillow’s $448,503 is the working figure here. Movoto’s June median sold price of $599,900 runs much higher, and Redfin shows a median sale price of $460,000, up 3.6% in its most recent read. Movoto’s number skews toward large lakefront and estate homes. Treat the spread as a warning that the appraised value on your specific house can land anywhere in a wide band.
Run the Coverage Math First
Lakeland rents don’t keep pace with its home prices. Homes.com puts the median home rent at $2,090 with a price-to-rent ratio of 19.2. Zumper shows an average rent of $2,285. Against Zillow’s value, that works out to gross rent of roughly 0.47% to 0.51% of value each month. Rentometer’s 3-bedroom figure of $2,068 tells the same story, though its page has narrative errors and is best used as a loose cross-check.
DSCR is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. The standard benchmark is 1.00x. Some lenders review below that, but those files usually need lower leverage, stronger credit, or more reserves.
Here is a modeled run on the $450,000 example. It assumes rent between $2,090 and $2,285, 30-year amortization, and taxes and insurance included. These are modeled assumptions, not quotes.
| LTV on refinance | Modeled coverage (with taxes and insurance) | Read |
|---|---|---|
| 75% (program ceiling) | Around 0.8x | Below 1.00, needs restructuring |
| 65% | Around 0.9x | Still short |
| 55–60% | Around 1.0x | Borderline at best |
That is the honest picture. Push this house to the 75% ceiling and coverage lands well under 1.00. The cash-out ceiling is a cap, not a target. On a typical Lakeland single-family, the number only clears 1.00 at meaningfully lower leverage, or on a lower-basis house.
When coverage falls short, the paths a lender may review include a sub-1.00 program, an interest-only structure, or a lower LTV with less cash pulled. Each carries different pricing, reserve, and credit expectations. Whether any of them fits depends on lender guidelines, credit approval, and property review. It is not a given.
For reference, typical parameters on most files: minimum credit near 620, with better pricing tiers at 660, 680, and 700, reserves around 6 months of PITIA, and loan amounts up to $3,000,000 on standard programs. Confirm current terms against lender overlays.
Submarkets: The Lake, the District, and the Rest
Garner Lake subdivisions. The private lake covers 241 acres and is the largest in Shelby County, per the Garner Lake community site. Six subdivisions border it (Lakeland Estates, East Shores, Windward Slopes, The Preserve, Long’s Landing, and The Pointé), with 634 homes, 266 of them lakefront. Access belongs to lot owners only.
This is a premium owner-occupant enclave, and it is the hardest place in town to make a rent-to-debt ratio work. Expensive houses against moderate rents is the exact formula for sub-1.00 coverage. If you already own here, you probably bought for lifestyle or appreciation, and a refi will show you how thin the income side is. If you’re shopping, skip it for cash flow.
The Lake District and Canada Road corridor. This is the mixed-use node near I-40. Lakeland Town Square and The Lake District have recently opened, per the Homes.com neighborhood guide, and an apartment community sits there. Land east of Canada Road is described as seeing development all around. That is the most likely source of purpose-built rental supply, and also of competing supply. No reliable rent bands exist for it, so underwrite conservatively.
Windward Slopes, Lakeland Meadows, and the golf-oriented areas. These are newer single-family communities that skew owner-occupied. Rental listings are sparse. That scarcity can help occupancy but doesn’t fix the ratio problem.
That’s the whole list. Lakeland has no cheap-basis pocket in the research. The math improves only if your basis is well below market.
Seasoning and Appraisal in a Slow Market
Homes here are sitting longer. Movoto’s market data shows 68 days on market in June, up from 39 a year earlier, and a September median of 73 days. Sales totaled 96, down from 106. That is a slower, thinner comp environment.
Two things follow. Programs typically look for about 6 months of ownership measured from title recording before a cash-out, so a recent purchase can’t be refinanced immediately. And once you’re past seasoning, appraisers with few fresh comps tend toward conservative valuations.
The practical move: model proceeds at a lower LTV than the program ceiling and treat the appraisal as the swing factor. Equity available is never a guaranteed cash figure. It depends on rent used for lender review, PITIA, reserves, and that 75% cap.
Skip the Multi-Unit Thesis Here
Renter-occupied households in Lakeland run 63% below the national average, and the housing stock is dominated by large single-family homes. Homes.com identifies single-family houses as the most affordable rental option locally. No duplex, triplex, or fourplex inventory turned up in the research.
Underwrite Lakeland as a single-family rental in the low-$2,000s a month. If your strategy depends on stacking multiple doors’ income under one loan, look at neighboring markets. Lakeland won’t supply it.
What Lendmire Sees on Files Like This
In high-price, low-renter-share suburbs, the common friction point is a strong borrower with a weak ratio. Credit and reserves look fine, but rent sits close to 0.5% of value, so the refinance only works at conservative leverage. The cleaner files tend to come with a signed lease at or near market rent, a current rent comp package, and a borrower who has already decided how much cash they need rather than how much they can pull. Deciding that first often keeps the LTV realistic and the file simpler for the lender to review. Loans to LLC-titled borrowers are subject to lender program eligibility, which is worth confirming before you retitle anything.
Why Demand Holds Even When Yields Don’t
Lakeland is a bedroom community, with a Census Reporter-based population near 14,192 and a median household income of about $113,843. Residents commute to Memphis-area employers. HUD’s Memphis market profile counted roughly 30,000 FedEx employees in the metro, a dated figure but a reminder of how concentrated the job base is. It also noted St. Jude’s multi-billion-dollar expansion plan. Baptist Memorial, Methodist Le Bonheur, and other Memphis systems add healthcare demand.
The forward story is eastern-corridor development ahead of Ford’s Blue Oval electric truck plant. IRR’s Memphis multifamily research expects development to continue in Arlington, Lakeland, and Cordova. It’s a plausible long-term demand driver, but it is a forecast, and it brings new competing supply with it.
The metro apartment picture argues for restraint. IRR describes the Memphis multifamily market as stable through a heavy supply wave, and MMG Real Estate reports effective rents fell 0.2% last year, with deliveries projected to drop to 456 units. Use flat rent assumptions, not growth.
Where the Proceeds Go
The point of a cash-out is redeploying capital. Given Lakeland’s yield profile, one reasonable play is pulling modest equity at conservative LTV and putting it into a higher-yield Memphis-metro property. That keeps the Lakeland asset stable while the new purchase does the cash-flow work. The other play is a rate-and-term refinance with little or no cash out, if the goal is simply restructuring.
Two internal resources cover the mechanics. The guide “The Refi Options” walks through seasoning, LTV, and reserves, and the investment property refinance options lay out the broader menu. The DSCR loans in Tennessee hub covers the state overview.
DSCR vs. conventional financing
Two common ways to finance an investment property in Lakeland, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Investors with a Lakeland rental can request a scenario review or call 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before you finalize any plan.
Frequently Asked Questions
How much equity can I pull from a Lakeland rental?
It depends on the appraisal, the rent, and the 75% LTV ceiling. Because Lakeland’s rent sits near 0.5% of value monthly, coverage often forces a lower LTV than the ceiling allows. Proceeds are never guaranteed and are reviewed by the lender.
Will a Lakeland single-family clear 1.00x coverage?
Sometimes, but usually at reduced leverage. Modeled on a home near the local value index with taxes and insurance included, coverage around 0.8x at 75% LTV improves toward 1.0x only at much lower LTV. Sub-1.00 programs or interest-only structures may be reviewed, subject to guidelines.
Does Garner Lake frontage help my refinance?
It can help value but rarely helps coverage. Lake-subdivision homes are priced as premium owner-occupant properties, and rents don’t scale with price. Expect the appraisal to matter more than the rent.
Can I refinance right after buying?
Not typically. Programs generally look for about 6 months of ownership from title recording before a cash-out. Lakeland’s longer days on market also mean the appraiser may have fewer comps, so leave room in your projections.
Is a duplex or fourplex strategy realistic in Lakeland?
No. Research found no meaningful small multifamily inventory, and the market is dominated by large single-family homes. Look to neighboring Memphis-area markets for multi-unit math.
The most useful next step is pulling three current single-family rental comps within Lakeland and running each against a conservative appraised value. That tells you whether your specific house belongs in the cash-out column or the hold-and-wait column.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire — NMLS# 2371349 — connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s tax returns, is central to lender review, an approach that suits self-employed operators and portfolios beyond four financed properties.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Lakeland
4. Redfin
6. Zumper Lakeland rent research
8. Homes.com neighborhood guide
9. areavibes.com — Lakeland TN Housing
10. 14,192
11. $113,843
12. HUD PD&R Memphis Housing Market Profile
13. IRR Memphis multifamily viewpoint
14. MMG Real Estate
15. Scotsman Guide — Top Workplaces 2026
16. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance La Vergne Tennessee · Cash Out Refinance Investment Property Brentwood Tennessee · DSCR Cash Out Refinance Murfreesboro Tennessee
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.