
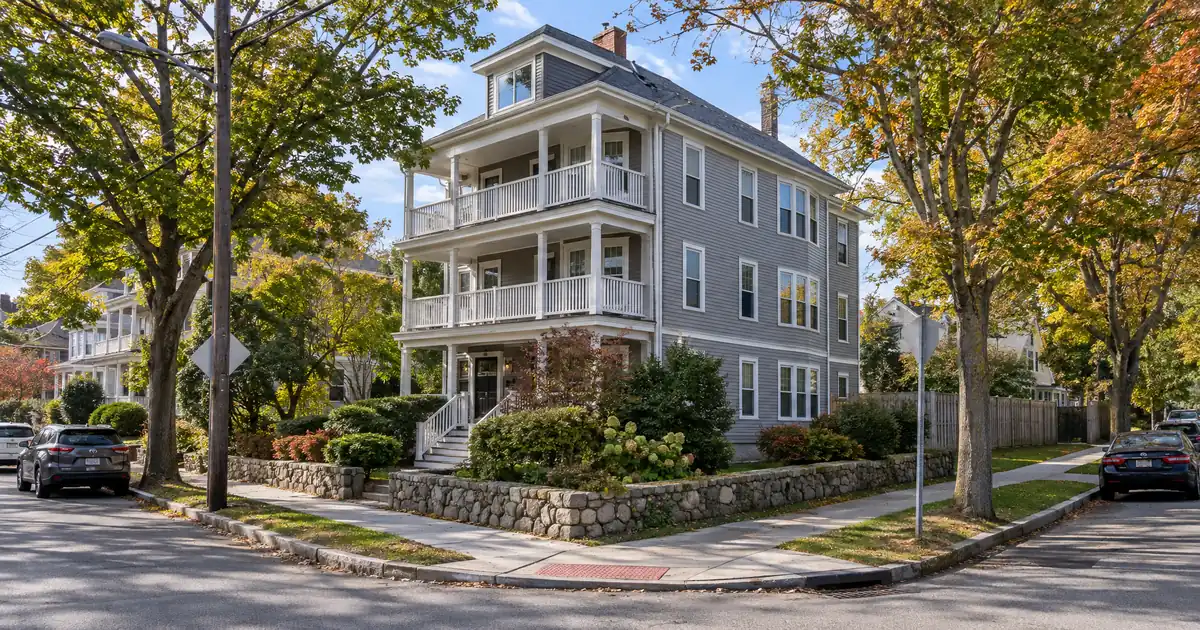
Picture an investor holding a two-family in Central Lynn, purchased at $520K, which is roughly where Redfin puts the neighborhood’s median sale price, up 31.3 percent from the year before. The property has been rented, stabilized, and held past the seasoning window. The question is not whether equity exists. It is how much of it a 75 percent loan-to-value ceiling lets out, and whether the rents still cover the new, larger obligation once it does.
That is the DSCR cash-out refinance problem in Lynn, and the answer changes sharply by property type.
DSCR Cash-Out Calculator
Run the cash-out numbers in Lynn, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A DSCR cash-out refinance on a Lynn, Massachusetts investment property is underwritten primarily on the rental income the property produces measured against its full monthly obligation, rather than the owner’s personal income, and it converts seasoned equity into capital subject to a loan-to-value ceiling, reserves, and lender review.
- Cash-out LTV typically tops out at 75 percent, with about six months of seasoning from title recording.
- Lynn single-family at median pricing models below 1.00 coverage; three-unit stock models well above it.
- Listed Lynn six-family buildings advertise 7.1 to 7.2 percent cap rates.
- Entry prices span $365K in Downtown Lynn to $632K in West Lynn.
Lynn Market Snapshot
A quick read on the Lynn investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $905K median multi-family listing price (Redfin) |
| Typical rents | $2,261 median (Zillow Rental Manager Market) |
| Cap rates | 7.2% cap rates (Homes.com Lynn multi-family) |
| University enrollment | ~10,000 students/year (North Shore Community College) |
| Population | 103,510 population (Census Reporter) |
| Employment | 4,391 (fall 2022 headcount) (North Shore Community College) |
How Much Equity Actually Comes Out
A DSCR cash-out refinance in Lynn is capped at 75 percent of appraised value, so extractable equity equals 75 percent of the new value minus the existing payoff, less costs and reserves. Eligibility generally requires roughly six months of ownership from title recording, a coverage ratio at or above 1.00, and about six months of PITIA in reserves, subject to lender guidelines.
The mechanics are simple arithmetic, so run them in percentages. Say a property appraises 20 percent above the investor’s all-in basis and the existing loan sits at 60 percent of that new value. The 75 percent ceiling leaves 15 percent of value on the table before costs. Raise the appraisal and the proceeds expand. Hold the appraisal flat and they shrink. Proceeds are never a guaranteed figure; they depend on rent used for lender review, full PITIA, reserves, and the appraisal.
Credit tiers in the network start at a 620 floor and step up through 660, 680, and 700, with better tiers generally supporting stronger leverage and pricing. Reserves rise to about nine months above a $1.5 million balance, and standard programs run up to $3 million. Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker with DSCR financing in 40 states plus D.C., arranges these cash-outs through wholesale channels, with eligibility decided by the lender. For the underlying definition, see the DSCR fundamentals. Investors weighing this against a standard refinance can compare refi programs.
The 1.00x benchmark is common because rent covers the payment at that level. Some lenders review lower coverage, but that usually costs the borrower leverage, pricing, or cash down. Exact eligibility depends on credit profile, reserves, property review, and state overlays.
Where Lynn Equity Built Fastest (and Where It’s Noise)
Appreciation in Lynn is uneven, and the neighborhood medians that look best are the least reliable. The strongest equity story is West Lynn. Central Lynn and Downtown Lynn show larger percentage gains on thin samples, while Lynn Woods and the Lynnway have softened.
Start with the signal. West Lynn’s median sale price was $632K over the trailing three months, up 11.9 percent year over year, at $366 per square foot, with homes selling in 29 days. That is a market-rate, owner-occupier-heavy pocket with commuter demand, and a sustained double-digit move across a larger sales base is the kind of appreciation an appraiser can actually support.
Now the noise. Central Lynn’s 31.3 percent jump comes with a median price per square foot of $342, which Redfin shows down 13.2 percent. Downtown Lynn tells a similar story: a $365K median up 18.5 percent, but $272 per square foot, down 11.7 percent. When price rises and price per square foot falls, the mix of homes sold changed. Smaller sample, different product, and not necessarily a market that re-rated. Skip the temptation to underwrite a cash-out on that headline.
Then the soft spots. Lynn Woods shows a $590K median, down 1.7 percent, though its price per square foot rose 4.6 percent to $432. The Lynnway corridor sits at a $625K median, down 5.3 percent. An investor in either should assume the appraisal lands flat, not higher.
East Lynn, with no Redfin median in the research, deserves a mention for stock rather than price: small pre-war buildings of four units or fewer, which is the format DSCR lenders understand best. Rent variation across these neighborhoods could not be sourced below the citywide level, so the neighborhood-level rent comparisons here are directional only.
The Coverage Math: Triple-Deckers vs. Single-Family
Multi-unit property clears 1.00 comfortably in Lynn; median-priced single-family does not. The cash-out decision should start with property type, not neighborhood, because the rent roll, not the appraisal, determines whether the new loan is reviewed.
Rents frame the inputs. Zillow Rental Manager puts the citywide median at $2,261, and RentCafe reports an average of $2,419, down 0.76 percent over the past year, with one-bedrooms at $2,128, two-bedrooms at $2,711, and three-bedrooms at $3,696. The $2,100 to $2,600 band cited in a North Shore multifamily investing guide overlaps the middle of that range.
The table below runs modeled scenarios at the 75 percent cash-out ceiling. Coverage is rent divided by full PITIA, including taxes and insurance at Massachusetts averages. The three-family value is a modeled assumption, not a sourced figure, and the rents are the researched ranges above.
| Scenario | Value basis | Rent assumption | Modeled coverage |
|---|---|---|---|
| West Lynn single-family | $632K median | $2,261 to $3,696 | 0.55 to 0.90 |
| Downtown Lynn entry unit | $365K median | $2,128 to $2,711 | 0.90 to 1.15 |
| Three-family (modeled) | $800K assumed | $2,100 to $2,600 per unit | 1.25 to 1.55 |
Two readings matter here. First, a single-family at West Lynn’s median price falls below 1.00 at full leverage even at the top of the rent range. Sub-1.00 files may route through a sub-1.00 program, an interest-only structure, or reduced leverage, each reviewed by the lender and each costing the borrower something in pricing or proceeds. Qualification is subject to lender guidelines, credit approval, and property review.
Second, the three-family clears with room to spare, because three rent streams sit against one acquisition basis. That is the multi-unit mechanic in its simplest form. In-place cap rates support it: listed Lynn six-family buildings advertise 7.1 and 7.2 percent, meaningfully wider than the compressed cap rates typical of Boston-core triple-deckers.
Working DSCR brokers see a recurring pattern in older, small-multifamily markets like this one: the file is won or lost on expense allocation, not on rent. Separately metered, gas-heat units with clean rent rolls underwrite cleanly. Shared utilities, undocumented rents, or a unit rented below market push the qualifying figure down even when the building is full. One West Lynn three-family listing, for instance, advertised separately metered units with lead-compliance paperwork, which is the profile that tends to clear without surprises.
Rent growth deserves a footnote. Average rent slipped slightly year over year, so the cash-out case rests on in-place income, not on projected increases. (A coverage ratio that only works with a 5 percent rent bump is not a ratio worth borrowing against.)
Who Pays the Rent: The Employment Base
Lynn’s tenant base is anchored by industrial and health-care employment, which supports long-term occupancy for workforce rentals more than it supports speculative rent growth. That distinction matters for how much cushion to build into a cash-out.
GE Aerospace’s Lynn plant designs, produces, assembles, and tests military and commercial aircraft engines across 1.6 million square feet and has invested more than $100 million in the facility over five years. The company’s page lists more than 2,500 employees, and local reporting cited a roughly $31 million annual investment alongside a training program that has enrolled 600 local adults with an 83 percent job placement rate across more than 140 area companies. That last figure is the useful one for underwriting: the wage base feeding Lynn rentals is not a single-employer bet.
Health care is a real anchor but a subtler one. Lynn lost its acute-care hospital when Union Hospital closed, and Mass General Brigham replaced it with a 41,000-square-foot outpatient medical village covering primary care, urgent care, imaging, and behavioral health. Emergency and inpatient care now route through Salem Hospital. For investors, the takeaway is that health-care employment supports demand, but Lynn is an outpatient node, not a hospital town. The old site is slated for 150 senior apartments, a pipeline project worth watching for supply in the age-restricted segment.
Demand context from Census Bureau QuickFacts: a population of 103,510 across 10.7 square miles and a median household income of $73,340. Per RentCafe, 52 percent of housing is renter-occupied, and 75 percent of apartments sit in smaller complexes under 50 units. That small-building profile is why per-unit stacking works. North Shore Community College adds roughly 10,000 students a year across its campuses, a modest renter driver rather than a core one.
No reliable citywide vacancy figure turned up in the research, so occupancy is best read through days on market: homes in West Lynn sell in 29 days, and Redfin describes the city as very market-rate.
What Makes Cash-Out Underwriting Tight Here
The risk in a Lynn cash-out is not that equity is missing but that the appraisal and the coverage ratio can diverge. An appraisal built on thin neighborhood comps can come in below the expected value, and a lower value shrinks proceeds fast under a hard 75 percent cap.
Three specifics to stress-test. One: small-sample volatility in Central and Downtown Lynn means last quarter’s median is not a predictable appraisal. Two: citywide values are nearly flat, with Zillow’s average home value at $584,482, up just 0.5 percent over the past year. The strong neighborhood gains are real but local. Three: transit upside is partly speculative. Commuter rail service returned to Lynn with an interim station, a delivered catalyst for Downtown Lynn. The Blue Line extension, by contrast, is long-planned but unfunded, and no cash-out should rest on it.
The stronger play might be the older, separately metered three-family in West Lynn over a Downtown Lynn condo for cash-out purposes, though investors who bought at the Downtown floor and want the highest percentage equity gain could argue the other way. It is a genuine toss-up. The coverage math favors the multi-unit; the basis favors the condo.
Prospective borrowers should also check LLC-titled holdings against eligibility, which varies by program; LLC ownership is commonly accepted subject to lender program eligibility. Local rental rules, taxes, and insurance should be verified with qualified Massachusetts professionals before underwriting.
Putting the Proceeds to Work
Cash-out proceeds in Lynn are best recycled into the next small-multifamily acquisition, because the regional price gap makes Lynn a relatively cheap entry point. North Shore REALTORS reported a regional median of $726,000 for single-family homes against Lynn’s late-period rolling median of $583,000, and $459,900 for condos against Lynn’s $355,000, per a local brokerage analysis. Lynn trades at a visible discount to its own region.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Lynn, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The recycling logic is straightforward. Pull a measured slice of equity, hold the reserves, and redeploy into stock priced where rents cover the debt. At Lynn’s multifamily median listing price of $905K, with 30 multi-family units sold in a recent month, the product is trading, not stranded. The same logic works in reverse: leave some equity untapped. Pulling to the full 75 percent on a property whose coverage sits in the low 1.2 range leaves little room for a vacancy or an expense surprise.
Investors who want to see their own numbers can request a quote through DSCR loan options for Massachusetts investors, or call 828-256-2183. Other non-QM options in the market often apply tighter sub-1.00 guidelines, which makes confirming a program’s coverage treatment before applying worthwhile.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Lynn, Massachusetts?
Qualification centers on the property’s rent against its full PITIA, with a 1.00 benchmark on most files, plus a credit score at or above the 620 floor and about six months of reserves. Ownership typically needs to be seasoned about six months from title recording. Final eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Lynn, MA?
Expect an appraisal, a lease or rent schedule, reserves of roughly six months of PITIA, and a loan amount within program limits of up to $3 million on standard programs. Manufactured homes, log homes, and barndominiums fall outside these DSCR programs. Requirements vary by borrower, property, and lender.
Why does a three-family often qualify when a single-family does not in Lynn?
Three rent streams sit against one purchase basis, so the coverage ratio climbs. On modeled assumptions, a West Lynn single-family at its median price lands below 1.00, while a three-family at an assumed $800K lands in the 1.25 to 1.55 range. Sub-1.00 files may still be reviewed under different structures, with trade-offs.
Does the loss of Union Hospital hurt Lynn rental demand?
Not materially on the available evidence. The site now hosts an outpatient Mass General Brigham center, and acute care routes to Salem Hospital. Demand is anchored by GE Aerospace’s 2,500-plus employees and a broader manufacturing and health-care base, though investors should not describe Lynn as a hospital market.
What DSCR terms may lenders review for investors in Massachusetts?
Lendmire is a mortgage broker, not a lender, and it arranges DSCR investor loans that lenders review on rental income rather than personal income documentation. A key feature on cash-out files is the 75 percent LTV ceiling, with reserves and credit tier shaping leverage. All scenarios remain subject to lender review and program guidelines.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
The Next Step in Lynn
Before modeling any cash-out, pull sold comparables for the specific block, not the neighborhood. Lynn’s medians swing on small samples, and the gap between a Central Lynn headline and an appraiser’s actual comps is where the proceeds are won or lost.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income instead of the borrower’s W-2 history, a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to program review and program guidelines. The firm has been recognized by Scotsman Guide’s Top Mortgage Workplace program as a top-ranked workplace in 2025 and a top-ranked workplace in 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Homes.com — Lynn MA Multi Family Homes for Sale
2. $905K
4. North Shore Community College
6. West Lynn’s median sale price was $632K
7. RentCafe
8. North Shore multifamily investing guide
12. Zillow’s average home value
13. cbfirstquality.com — Lynn Housing Styles and Price Trends Explained
14. Scotsman Guide — Top Workplaces 2025
15. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Lynn, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.