
Picture an out-of-state investor scrolling Methuen listings for the first time. The citywide median sale price sits near $650K per Redfin data via Bentley’s Real Estate, and the rent comps look thin against that number. The investor wonders whether anything here cash flows. Then a Google Maps tab shows a 19th-century concert hall built around the first concert pipe organ in the United States, a mill-conversion apartment district, and an I-93 on-ramp that puts Boston within commuting reach.
That mix of heritage character and expensive entry pricing is why a DSCR cash out refinance in Methuen, Massachusetts works differently than it does in cheaper merrimack Valley markets. This article is about owners who already hold a Methuen property and want to pull equity out of it. It is not about buying one.
DSCR Cash-Out Calculator
Run the cash-out numbers in Methuen, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Oct 1, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Oct 1, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A cash-out refinance on a Methuen rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the lender reviewing leverage, seasoning, reserves, and credit alongside it.
- Downtown’s median sits at $525,000 per Homes.com, well below the citywide figure.
- Cash-out leverage on investment property tops out at 75% LTV, with about six months of seasoning.
- Two-unit income stacking clears coverage far more easily than a single-family rent at these prices.
- Zumper shows average rents flat year over year, so underwrite today’s rent with no growth.
- Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Prices Are Flat, So the Equity Was Made at Purchase
Methuen owners who bought well have equity. Owners counting on appreciation to create it from here are waiting on a market that isn’t cooperating.
Sources disagree on direction. Redfin data via Bentley’s shows the median sale price up 5.6% year over year, while Zillow’s home value index shows 2.4% growth on an average value of $533,818. That index covers all housing types, so it runs lower than the sale-price medians. Movoto has list price per square foot down 1%. Call it roughly flat to mid-single-digit growth, depending on whom you ask. Every figure here varies by lender and program, since guidelines, property type, leverage, and credit profile all apply.
This changes how you think about a cash-out. In a steep appreciation market, you refinance on the market’s work. Here you refinance on the discount you negotiated when you bought, or on the value you added. If neither describes your property, the appraisal may come in closer to your purchase price than you hoped, and 75% of a flat number leaves little room above the existing payoff.
The refinance sequence works like this:
1. The appraisal sets value.
2. The 75% LTV ceiling sets the maximum new loan.
3. The existing mortgage gets paid off first.
4. Whatever remains is the cash-out, and it is not a guaranteed figure. Rent used for lender review, the full monthly obligation, and reserves all constrain it.
5. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Downtown Spicket Falls: Where the Coverage Works
Downtown Methuen is the strongest DSCR submarket in the city, and it isn’t close. Homes.com puts the median there at $525,000, down 5% year over year, with homes selling in about 20 days on average. That is the lowest basis in the city. Homes.com’s local guide also describes downtown as the densest part of town with the largest concentration of multi-family homes, while the East End and West End are mostly single-family. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
The core is the Broadway, Osgood, Hampshire, and Pleasant street grid, walkable to the Rail Trail and the Music Hall, with mill-conversion apartments nearby. Redfin’s neighborhood rent snapshot is about a year stale and thin, but it ranks downtown at the top of the city’s neighborhoods for rent. Lowest prices and highest rents is the combination a debt-coverage ratio wants.
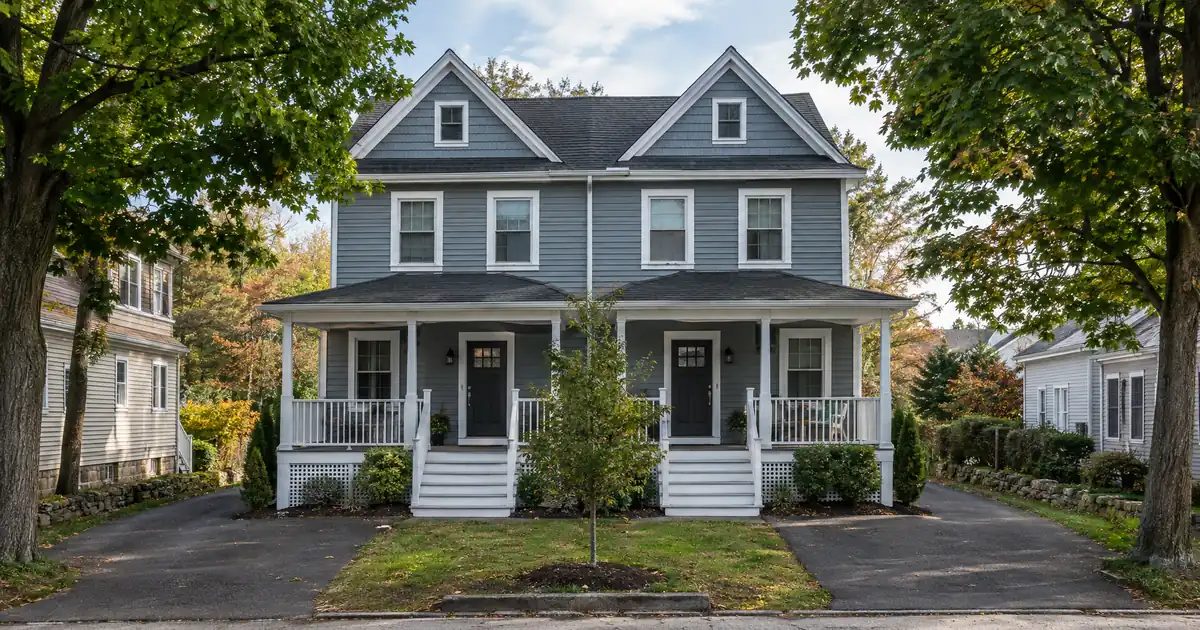
Run the numbers on a downtown two-family. These are modeled assumptions, not sourced market data. Take a building that appraises near the $525,000 neighborhood median and use Rentometer’s listing-based 2-bedroom figure of $2,470 per unit. Two units gross about $4,940 a month. At 75% LTV, with taxes and insurance counted in the full monthly obligation, coverage lands around 1.4x. That is a comfortable margin over the 1.00 baseline, and it is why the downtown multi-family stock deserves the attention. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Now compare a single-family house at the $650K citywide median renting as a 3-bedroom at Rentometer’s $3,139. At the same 75% LTV and with taxes and insurance included, coverage falls below 0.80. A single 2-bedroom rent on that same price is worse. Stacking two units roughly doubles the rent-to-price ratio, and that gap decides whether the file works. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
DSCR files in markets like this one typically split into two groups. Small multi-unit properties with a modest basis show coverage with room to spare, and the conversation is about how much cash to pull. High-basis single-family rentals show coverage below the baseline, and the conversation is about structure: lower leverage, interest-only options, or a sub-1.00 program. Lenders review those scenarios case by case. Lower leverage alone often doesn’t close the gap on a single-family at these prices, so owners should run it before assuming it will.
Skip the Searles and Nevins historic streets for this purpose. The Mass. Historical Commission describes higher-end heritage housing there. It is owner-occupant character, not cash-flow territory.
East Methuen and the Loop: Think Twice
East Methuen draws retail and commuter tenants off I-93 and the state line. The Loop open-air shopping center anchors the Pleasant Valley corridor. Redfin’s East Methuen median rent runs around $2,350, and current new-build asks nearby run roughly $2,100 to $2,289 for a 1-bedroom and $2,600 to $2,943 for a 2-bedroom, per Zillow’s rental listings. Those are amenity-driven apartment asks, not what an older house will command.
The problem is the price side. East End stock is mostly single-family, which means one rent against a high basis. That is the sub-1.00 pattern from the single-family scenario above. Owners there who bought years ago may hold plenty of equity, but the cash-out file still has to clear coverage on a single lease. West Methuen is a popular multi-family area, though no reliable price or rent data turned up. Treat any West Methuen duplex as a case-by-case file.
The south end near the Lawrence line (Arlington, Messer’s, Mount Vernon) has only neighborhood names to go on. Nothing sourced supports price or rent figures there, so evaluate those properties on their own comps.
The Mechanics: Seasoning, LTV, Reserves
Here is the program picture, shown step by step. These are typical guideline ranges from the network’s programs, not commitments, and exact eligibility depends on the lender, credit profile, property review, and state overlays. Review details remain subject to lender overlays.
- Seasoning: about 6 months of ownership, measured from title recording. If you closed on the property recently, the clock matters.
- Leverage: cash-out tops out at 75% LTV. That is a different cap than purchase leverage, so don’t carry the purchase number over.
- Coverage: the baseline is 1.00x, meaning rent used for lender review covers the full monthly obligation. The guide “What Is a DSCR Loan” breaks down that ratio. Some lenders review lower scenarios, but those usually mean more cash in, lower leverage, or stronger compensating factors.
- Credit: a 620 floor, with tiers at 660, 680, and 700 that can improve the file.
- Reserves: about 6 months of the full monthly obligation (about 9 above $1,500,000).
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network.
The Catch: A Small Renter Pool and Thin Comps
Methuen is an owner-heavy city, and that shapes the refinance. RentCafe counts 5,138 renter households, about 27% of the city, against 73% owner-occupied. Zumper’s average rental inventory is only about 32 units. That is a small pool, which means few rental comps for an appraiser to lean on and a reason to confirm lease-up timing locally instead of assuming it.
Rent trends add to the caution. Zumper shows the average rent at $2,225, unchanged from a year earlier. RentCafe’s Yardi Matrix figure shows a 1.34% decrease, though that covers buildings with 50 or more units only. No sourced vacancy figure exists for the city, so don’t underwrite a vacancy assumption you can’t support.
The practical advice is to model coverage on today’s lease and no growth. If a property only qualifies with a rent bump baked in, it doesn’t qualify.
Where the Proceeds Go Next
Equity pulled from a Methuen property is capital with options. The demand base here is residential and commuter-driven. Census estimates put the population at 53,455, and Bentley’s describes a car-oriented residential and retail hub with short runs to Boston and southern New Hampshire. Healthcare adds a steady anchor, with Merrimack Health, the system formed with Lawrence General as a founding member, operating the former Holy Family campus in Methuen. No sourced employer headcounts exist, so treat these as demand context and not as numbers.
Recycling the proceeds into another downtown two-family would repeat the strong-coverage pattern. Using them on a high-basis single-family would repeat the thin one. The refinance is only as good as the next deal’s math. Owners comparing paths can look at investor refinance options alongside the cash-out route.
The Music Hall tells you something about this city, by the way. The hall’s organ was dedicated in 1863 and moved to Methuen when Edward F. Searles built the hall to house it, and the instrument now carries 6,088 pipes. Methuen’s character comes from inherited value that someone recognized and kept. That is not a bad frame for an equity-extraction strategy.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Methuen, MA, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Lendmire (NMLS# 2371349) works with Methuen, Massachusetts investors through a DSCR program footprint spanning 40 states plus Washington, D.C. If a file looks borderline, investors can talk through the file or call 828-256-2183 to see how the structure could work.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Methuen, Massachusetts?
The property’s rent used for program review must cover its full monthly obligation (principal, interest, taxes, insurance, and any HOA dues), typically at a 1.00x baseline. Beyond that, lenders look at a credit floor of 620, about six months of ownership seasoning, reserves of about six months, and a 75% LTV ceiling. A downtown two-family has a much easier time clearing coverage than a single-family at the citywide median. Everything stays subject to lender guidelines and property review.
What are the requirements for an investment property loan in Methuen, MA when cashing out equity?
Expect a property appraisal, a lease or rental analysis, a minimum credit score, and cash reserves. The loan amount is capped by 75% of appraised value, and the existing mortgage is paid off from the proceeds. Eligible property types include single-family and small multi-unit rentals. Manufactured homes, log homes, and barndominiums fall outside these programs.
Does flat pricing in Methuen hurt a cash-out refinance?
Yes, if you were counting on appreciation to build the equity. Sources range from roughly flat to mid-single-digit growth, and downtown’s median is down about 5%. Owners who bought below market value, or who improved the property, are in a much better position than owners who bought at the median and waited.
Which Methuen neighborhoods fit a DSCR cash-out best?
Downtown Spicket Falls fits best because of its lower basis, its concentration of multi-family stock, and its position at the top of the city’s neighborhood rent rankings. East and West End properties are mostly single-family and have to clear coverage on one rent, which is harder at current prices.
Can Lendmire help investors explore DSCR financing for properties outside Massachusetts?
Yes. Lendmire arranges DSCR investor loans. Qualification centers on the property’s rental income rather than personal income documentation, subject to lender guidelines. For Massachusetts specifically, see Lendmire’s Massachusetts DSCR platform.
For how equity extraction works on an investment property, see Lendmire’s DSCR cash-out refinance.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Verify current local rental rules, taxes, and insurance with qualified local professionals before you commit to a plan. If your Methuen property sits downtown near the Rail Trail and could stack two rents, is the equity in it working as hard as the organ at the Music Hall?
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin data via Bentley’s Real Estate
2. Homes.com
3. Zumper — Rent Research Methuen Ma
5. Movoto
7. Rentometer’s
9. RentCafe
10. 53,455
11. The hall’s organ
12. 2025
13. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Methuen Massachusetts · Cash Out Refinance Investment Property Massachusetts · DSCR Cash Out Refinance in Haverhill, Massachusetts: What Qualifying Takes on $2,400 Rent
Guides: Investment Property Cash-Out Refinance in Methuen, MA · Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.