
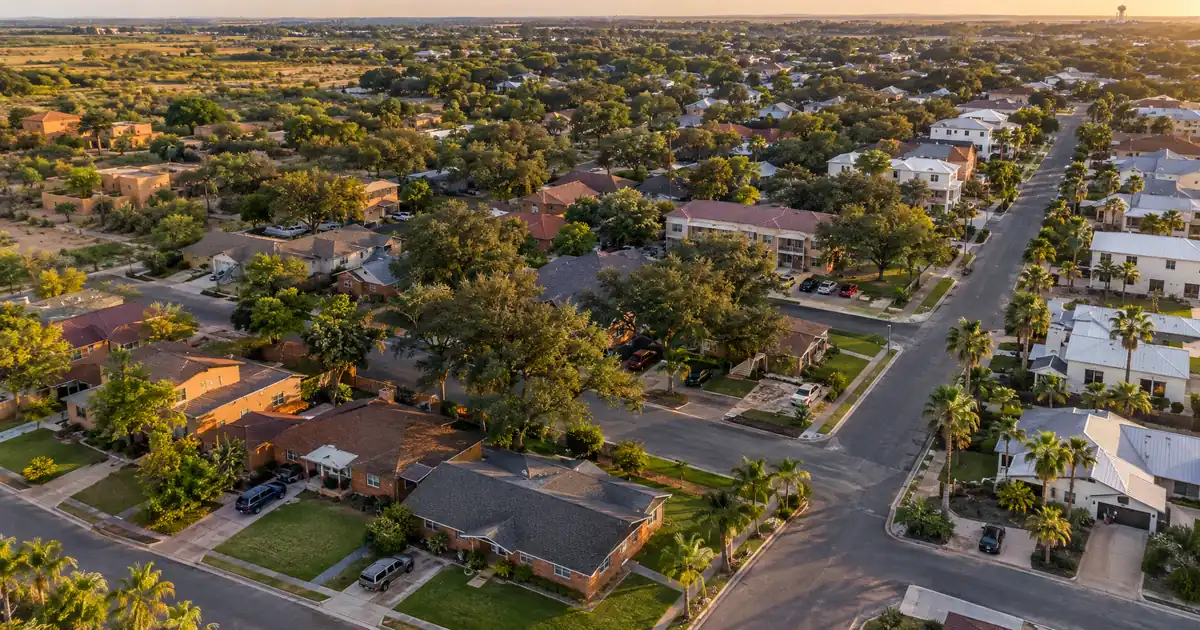
Mission is heading into a stretch where the appraisal is the deal. Redfin shows the median sale price at $263K, down 4.4 percent year over year, with homes taking 99 days to sell against 66 a year earlier. Anyone planning to pull equity out of a Mission rental over the next 6 to 18 months should assume values hold flat at best. The cash-out has to work on rent and basis, not on a rising market.
The Quick Read: A DSCR cash-out refinance in Mission, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the lender reviewing seasoning, an appraised value that caps leverage at 75 percent, reserves, and credit. The file works when documented rent, not appreciation, carries the coverage number.
DSCR Cash-Out Calculator
Run the cash-out numbers in Mission, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Median sale prices in Mission have softened compared with a year earlier, so appraised value is worth checking before you plan a cash-out.
- Blended median rents in the area run modest, which squeezes single-family coverage.
- Newer fourplexes in Hills at Sharyland are the stronger per-building rent case.
- Cash-out needs about six months of seasoning and caps at 75 percent LTV.
- Multifamily listings tend to sit on the market for a while, so plan on conservative appraisals.
Mission Market Snapshot
A quick read on the Mission investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 164 sales (Redfin Housing Market, Mission) |
| Typical rents | No citywide figure sourced (NeighborhoodScout, Sharyland) |
| University enrollment | ~60,000 students (TxEDC McAllen-Edinburg-Mission) |
| Employment | 88 new jobs (Mission EDC Latest News) |
| Vacancy | 9.8% (NeighborhoodScout, Sharyland) |
Sharyland Plantation: Most Equity, Thinnest Coverage
West and northwest Mission holds the newest and largest single-family stock in the city, which makes it the most likely place for an investor to be sitting on real equity. It is also where the coverage math is hardest. NeighborhoodScout reports a median price near $299,299 and a 9.8 percent vacancy rate for Sharyland Plantation, while Movoto shows a median listing price of $392K. The two sources disagree because one tracks sales and the other tracks asks. Neither tells you what a house rents for.
Here is the honest read: Sharyland is owner-occupant territory. Higher prices against a citywide blended rent of $1,200 mean a cash-out on a single-family home here often lands below the 1.00 benchmark once taxes and insurance are in the debt service. A 9.8 percent neighborhood vacancy figure doesn’t help. If you own here, a cash-out can still work, but it usually means lower leverage, a strong lease in place, and an appraiser willing to support value.
Skip Sharyland if you are buying for yield. Refinance it if you already own it and the lease is solid.
Why Flat Rents Change the Cash-Out Math
Mission’s rent story is soft, and cash-out underwriting has to respect that. Zumper reports a median rent of $1,200 across all bedroom counts and property types, down 8 percent over the past year. Zillow’s rental data shows a higher single-family figure of $1,500, but that reading is dated, so treat it as the optimistic case. Both are blended numbers. A real 3-bedroom house will rent differently, and the lease or appraiser rent schedule is what a lender will actually use.
Price also depends on who is measuring. Redfin’s $263K is a median of closed sales. Zillow puts the typical home value lower, at $218,831, down 0.6 percent, and sees homes going pending in around 110 days. Use the Redfin figure as the working benchmark for what an appraiser might see, and remember Zillow’s lower number is the more conservative read.
Run the numbers this way, using modeled assumptions rather than sourced market data. Take a $263,000 value at 75 percent LTV with a $1,500 modeled rent. Including taxes and insurance, coverage lands around 0.8x. Drop the rent to the $1,200 Zumper median and it falls below 0.7x. Now pair that $1,500 rent with the lower $218,831 value at the same leverage, and coverage sits just under 1.00. The difference is entirely about basis. An investor who bought low and can support a modest appraisal has a workable file. One who bought near the top of the market probably doesn’t.
Sub-1.00 files aren’t dead ends, but they are harder. Some lenders in the network may review lower-leverage or interest-only structures, and they typically want stronger credit and more cash reserves in exchange. Eligibility depends on lender guidelines, credit approval, and property review. Most standard programs are built around the 1.00x benchmark because rent covers the obligation at that level.
Working DSCR brokers see a recurring pattern in soft-price border markets like this one: the borrower’s expected cash-out is built on the purchase-era value or on a listing comp, and the appraisal comes in closer to recent sales. The files that clear cleanly tend to have a signed lease near market, documented rent history, and an owner who sized the request to the 75 percent ceiling before ordering the appraisal, not after.
Fourplexes Are the Better Collateral
Small multifamily is where Mission’s cash-out math gets more interesting. Homes.com lists 57 multifamily properties in Mission ranging from $90,000 to $4.5 million, and the stock includes newer builds. One example is a fully occupied fourplex in the Hills at Sharyland subdivision. Another is a gated fourplex in nearby Alton with 3-bed, 2-bath units of about 1,073 square feet. Four rents in one building spread the debt service across more doors than one house does, and a newer 3/2 layout tends to attract longer-term tenants with fewer near-term repair surprises.
Rent per door varies wildly by vintage. Older small-unit stock lists at low rents, and one Homes.com listing shows 2-bed, 1-bath units leased at $750 each. That is a listing anecdote, not a market median. Underwrite the building’s actual leases, and if the borrower is planning a cash-out on an older four-unit, expect the appraiser’s rent schedule to matter more than the pro forma.
Watch the unit count. One listing in North Mission describes six identical 2-bed, 2-bath apartments on half an acre. Five or more units generally pushes a deal out of standard residential DSCR programs, so confirm with a lender before assuming the same terms apply. Standard programs are built for 1 to 4 units.
The trade-off is exit liquidity. Homes.com data shows multifamily properties spending about 117 days listed before selling, and it puts the June median home price at $280,000 against an average sale price of $241,449. That spread says the median is skewed by property mix, not that values are climbing. Thin, dated comps make appraisers cautious. Size the request to a conservative value and treat anything above it as a bonus.
One more property-type note: manufactured homes, log homes, and barndominiums fall outside these DSCR programs. Valley investors owning any of those need a different path.
What Six Months of Seasoning Actually Buys
Lendmire helps arrange DSCR financing for Mission, Texas investors through wholesale and investor-lending channels across 41 markets, including Washington, D.C. (NMLS# 2371349). The brokerage’s cash-out programs share a few guardrails that matter more in a flat market than a hot one.
Seasoning runs about six months of ownership, measured from title recording. Leverage on a cash-out tops out at 75 percent LTV. That is a hard ceiling, distinct from the higher purchase cap. Reserves typically run about six months of PITIA, and credit tiers generally start at a 620 floor, with better positioning at 660, 680, and 700. Standard programs cover loan sizes up to $3,000,000, with smaller balances routing through select lenders. Equity available depends on rent used for lender review, PITIA, reserves, and the leverage ceiling. It is not a guaranteed figure. Details are subject to lender guidelines and can change, so confirm current terms before committing to a plan.
In a market where prices are drifting sideways, seasoning is less about waiting for appreciation and more about building a paper trail. Six months gives you a recorded title date, a lease history, and a cleaner rent schedule. It also gives the appraiser six more months of comps, which in Mission right now may not be flattering. If you bought below market or improved the property, that gap is your equity. If you bought at the median and prices slipped, it is not.
For the mechanics of how coverage is calculated, the guide “What Is a DSCR Loan” walks through rent against full obligation. How a cash-out differs from a rate-and-term refi is covered in more detail on the refinance pages. Statewide program structure is covered on Lendmire’s Texas DSCR loan programs page, and the refi options page breaks down the variations.
Where Does the Tenant Demand Come From?
Mission’s demand base is a mix of healthcare, education, and border-region manufacturing, with the city functioning as a commuter suburb to the Valley’s campuses. Mission EDC puts the population at 89,394, with a median age of 35, and projects growth to 92,624 within five years. That is steady, not explosive.
Healthcare and private education are the largest workforce segment, at 30.5 percent of the metro workforce according to TxEDC. Mission Regional Medical Center is a 297-bed community hospital with more than 300 physicians, and its owner plans to invest $10.5 million in a new emergency department in Palmview. Hospital staff, residents, and trainees tend to rent, which suits workforce 3/2 houses and small multifamily near the medical corridor.
UTRGV opened its latest fall term with a record 36,466 students, including a freshman class of 7,373. The main campus is in Edinburg, and Mission is one of the feeder cities, so 2-to-3-bedroom rentals along the Mission-to-Edinburg corridor have a durable demand base. There’s no source counting how many of those students live in Mission, so treat it as regional support rather than a local guarantee.
Industrial growth adds a second leg. Mission EDC reports a $50 million ZERLUMA aluminum recycling and manufacturing facility, plus a Stanley Black & Decker expansion creating 88 jobs and retaining 150. The EDC is explicitly targeting nearshoring around the Anzaldúas International Bridge. Those jobs support tenant demand, but announcements are not occupied payroll. Watch actual hiring before underwriting rent growth around them.
What Could Break the Pattern
The main risk is supply and concessions. The Dallas Fed says rents are still declining in most Texas metro areas and concessions remain widespread. That analysis covers major metros, not the Valley, so read it as statewide context. Even so, newer apartments offering concessions can cap achievable rents in a small market. Haircut rent assumptions instead of projecting growth.
The cash-out playbook also has a timing angle. Watch four indicators over the next 6 to 24 months:
- Days on market. Redfin’s 99 days is the number to beat. If it shortens, appraisals get easier.
- Rent direction. A reversal of the Zumper 8 percent decline would lift coverage on every file.
- Employer hiring. Announced manufacturing jobs need to become filled positions.
- Multifamily inventory. Listings sitting well past 117 days signal thinning comps.
If those move the right way, holding and refinancing later beats forcing a cash-out into a weak appraisal now. (Patience is underrated when comps are thin.)
DSCR vs. conventional financing
Two common ways to finance an investment property in Mission, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where the Proceeds Go
Cash-out proceeds only make sense if the next deal is better than the one you just tapped. In Mission, that usually means a newer fourplex, a lower-basis house, or a property in a corridor with stronger demand. Recycling equity into another Sharyland-priced house at these rents just repeats the coverage problem. Investors who can point to a specific next acquisition with a coverage number above 1.00 are in a much stronger position than those pulling cash to figure it out later.
To model a specific property, run the numbers with Lendmire or call 828-256-2183. Investors should also verify current local rental rules, property taxes, and insurance costs with qualified local professionals before committing to a structure.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Mission, Texas?
Qualification starts with the property’s documented rent measured against its full monthly obligation, with 1.00 as the common benchmark. Lenders also review about six months of seasoning, credit generally at a 620 floor or higher, and reserves near six months of PITIA. Leverage is capped at 75 percent of appraised value. Final eligibility depends on lender guidelines, credit approval, and property review.
What are the requirements for an investment property loan in Mission, Texas?
Expect a rental-income-based review of the property, a credit score at or above the program floor, reserves, and an appraisal. Standard programs cover 1 to 4 units, so a six-plex would need a different program. Manufactured homes, log homes, and barndominiums are not eligible. LLC-titled borrowers may qualify, subject to lender program eligibility.
Does a Mission fourplex work better for cash-out than a single-family rental?
Often, yes, because four doors of rent share one debt service. The Homes.com listings include newer fourplexes in Hills at Sharyland and Alton with 3/2 units, and those tend to rent better than older 2/1 stock. The catch is appraisal risk, since multifamily properties sit about 117 days on the market and comps are thin. Underwrite actual leases instead of city medians.
Is it smart to pull equity out of Mission property when prices are flat?
It depends on basis. If you bought well below the current median sale price or added value, there may still be room under the 75 percent LTV ceiling. If you bought near the median and prices slipped, the appraisal may leave little to extract. Running the coverage math on the lower Zillow value is a useful stress test.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. The brokerage has been recognized by Scotsman Guide as a 2026 Top Workplace, and the 2026 Top Workplace recognition announcement is public.
Set against Edinburg, where UTRGV’s campus puts a student and medical-trainee base at the doorstep, Mission is the slower rent story, and right now the math favors Edinburg for demand durability while Mission only wins where the basis is low and the building is a newer fourplex.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
3. TxEDC
4. Mission EDC
5. Zumper
7. Zillow
8. Homes.com
9. Mission Regional Medical Center
10. UTRGV
11. Dallas Fed
12. recognized by Scotsman Guide as a 2026 Top Workplace
13. the 2026 Top Workplace recognition announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Mission Texas · Cash Out Refinance Investment Property Harlingen Texas · DSCR Cash Out Refinance Baytown Texas
Guides: Investment Property Cash-Out Refinance in Mission, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.