
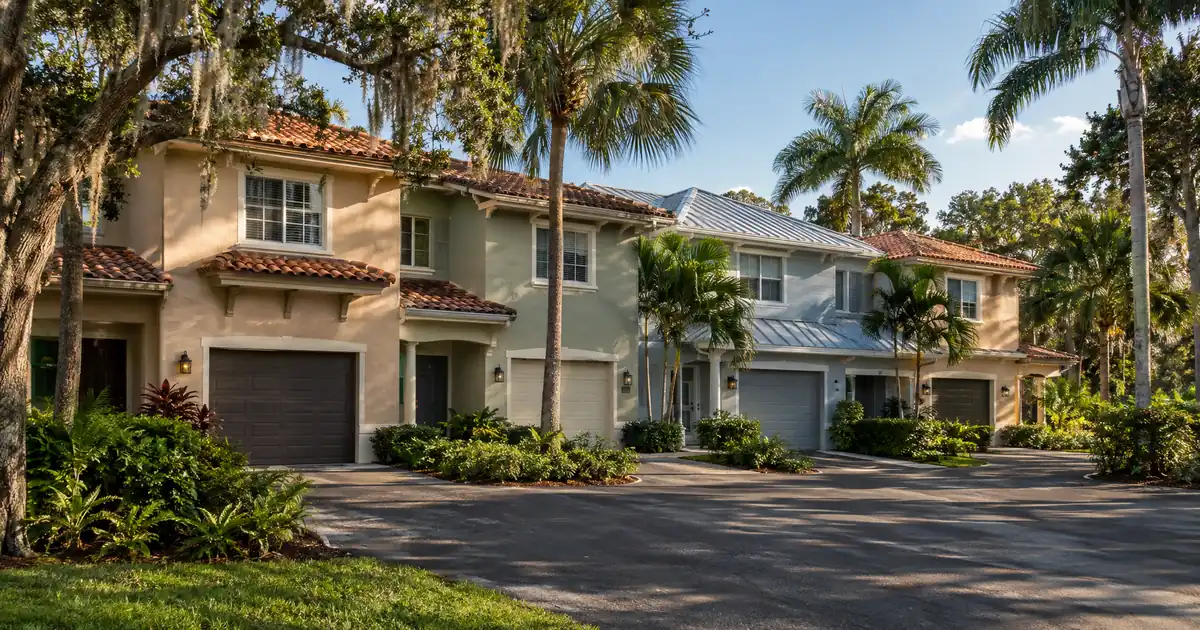
Most investors who hit the cash-out wall hit it in the same place. The property has appreciated, the equity looks real on paper, and then the coverage math and the appraisal cap shrink the check. In Palm Beach Gardens, that gap is wider than in most Florida markets. The price spread between attached product and golf-community estates is enormous, and the rent spread is not.
This is a DSCR cash out refinance market with one clear sweet spot and one clear trap. The sweet spot is small attached and multi-unit product. The trap is anything priced like a country-club home.
DSCR Cash-Out Calculator
Run the cash-out numbers in Palm Beach Gardens, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance:
A DSCR cash-out refinance in Palm Beach Gardens, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation, with loan size capped by both the loan-to-value ceiling and the coverage the rent can support.
- Condo and townhome medians sit near $403,500, versus $1,095,000 for houses, per pbprealestate.com MLS data.
- Six multifamily listings recently spanned $395,000 to $950,000, so comp sets are thin.
- Underwrite unfurnished annual-lease rent, not the furnished PGA National seasonal average.
- Cash-out LTV tops out at 75 percent, with about 6 months of seasoning.
Palm Beach Gardens Market Snapshot
A quick read on the Palm Beach Gardens investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median house $1,095,000 (Aug 2026) (Palm Beach Gardens Real Estate) |
| Typical rents | $2,193 median (Apartment List Rent Report) |
| Population | 60,959 population (Census Reporter) |
| Employment | 2,800 employees at Scripps after 15 years (Florida Trend “The Cluster) |
Why Equity Extraction Works Differently Here
The city’s headline prices mislead. The median house sold for $1,095,000 in the most recent monthly data, up 3.1 percent year over year, while the median condo or townhouse sold for $403,500, up 7.0 percent, per pbprealestate.com. Year to date, 826 houses closed at a median of $1,109,500 and 447 condos and townhomes at $415,000.
Other sources disagree on the citywide figure. Zillow puts the average home value at $665,482, down 4.8 percent, which reflects a different methodology that blends the whole housing stock. This article uses the MLS medians because they track actual closed sales by property type.
The key point is that appreciation on a $1.1 million house does not translate into cash-out capacity if the rent cannot cover the resulting obligation. Rents are the constraint. Apartment List puts the citywide median at $2,193, down 1.3 percent year over year. The Apartments.com local guide shows two-bedroom averages near $2,740. A property with a rent-to-price ratio in the 0.2 to 0.5 percent monthly range has to be sized carefully before any cash-out request.
That is a tradeoff, not a verdict. Lower-priced attached product converts appreciation into proceeds more reliably, while luxury single-family gains stay mostly on paper unless the investor accepts a much smaller loan or a lower-coverage program.
The Rules That Set the Ceiling
Three parameters frame every cash-out file in this market. On most files, the cash-out LTV ceiling is 75 percent, so an investor cannot borrow against the 80 percent figure that sometimes applies to purchases. Lenders typically want about 6 months of ownership measured from title recording before they will treat the value as an appraised cash-out candidate. And the standard coverage benchmark is 1.00, meaning rent used for lender review covers the full monthly obligation of principal, interest, taxes, insurance, and any association dues.
Reserves are typically about 6 months of that obligation, rising to about 9 months on balances above $1,500,000. Credit tiers generally run from a 620 floor upward, and standard programs go up to $3,000,000. All of it is subject to lender guidelines, credit approval, and property review, and none of it guarantees a cash figure.
The two constraints interact. A higher appraisal raises the LTV-based maximum, but a larger loan raises the monthly obligation and compresses coverage. In practice the smaller of the two limits sets the check. For a deeper walkthrough of that sequence, see the guide “The Refi Options”.
Where the Coverage Math Holds
Attached product and small multifamily are where the numbers cooperate. Three submarkets stand out.
Condos and Townhomes Near PGA National and The Gardens Mall
Median condo pricing near $403,500 against 2BR unfurnished asking rents of roughly $2,700 to $3,000 puts these assets near the 1.0 line. Modeled on a price near $410,000 and $2,750 in rent, coverage lands around 1.0 including taxes and insurance, and that is before any association dues. (HOA dues are the line item that quietly decides whether these deals clear.)
That is borderline territory. Where the number falls under 1.00, the options a lender may review include a sub-1.00 coverage program, an interest-only structure, or a reduced loan amount. Each involves tradeoffs in leverage, pricing, or cash required, and qualification remains subject to lender guidelines and property review.
One underwriting trap deserves emphasis. Apartment List’s PGA National data shows a two-bedroom average of $4,896, but that figure is inflated by furnished seasonal leases. Current Corcoran listings show unfurnished annual 2BR condos in the $2,700 to $3,000 range. Using the seasonal average would overstate coverage, and a lender will not accept it.
Highland Pines Duplexes and Triplexes
Older duplex and triplex stock is the strongest fit for equity extraction. Redfin’s multifamily listings show a duplex near $525,000 with each unit renting at $1,950, and a triplex with units at $1,750, $2,300, and $1,800, totaling $5,850 monthly.
Run the numbers on a modeled duplex valued near $525,000 with $3,900 in combined rent. At 75 percent LTV, coverage including taxes and insurance comes out around 1.1x, rounding down. The triplex, modeled near $675,000 against $5,850 in rent, lands in the low 1.3s. These are modeled assumptions, not sourced market data, and they move with appraisal value and the actual insurance quote.
The strategic angle matters more than the math. These are older, lightly renovated assets with separate meters, and listings note kitchen and bath updating potential. That favors a rehab-then-refinance approach. An investor who buys, renovates, waits out the roughly 6-month seasoning window, and refinances against an improved appraisal can extract equity created by work rather than by market drift. The investor refinance options page covers how that sequence fits different loan structures.
The comp caveat is real. Homes.com shows only six multifamily listings priced from $395,000 to $950,000. Thin comp sets can make appraisals less predictable, so an appraiser experienced with this micro-segment matters more than it does for single-family.
Downtown, Midtown, and the San Matera/Legacy Place Corridor
The PGA Boulevard corridor and the retail-adjacent areas near The Gardens Mall draw renters from the shopping and office workforce. Average one-bedroom rents near the Legacy Place and Downtown area run around $2,400, with two-bedroom averages near $2,778. Inventory here is mostly condo and attached product, so the same HOA-driven coverage question applies.
Skip the Golf-Estate Cash-Out
Estates in Old Palm and the luxury tier of Mirasol will not cash-flow to 1.0 on long-term rent, and the same holds for most large PGA National houses. Median house pricing above $1.09 million runs into rents in the low thousands. Mirasol’s average rent is $2,175 for a one-bedroom and up to $2,805 for a two-bedroom.
Avenir is a sharper example of the appreciation-versus-cash-flow tension. The community’s median sale price holds near $1.2 million, with roughly 3,900 homes planned and days on market falling from 95 to about 70. That is an appreciation story. It also carries supply risk: newly approved pods, including a 104-lot community, per TourAvenir’s development update, keep adding units that compete for the same renters.
The stronger play for cash-out is the attached and small multifamily product above. Buyers of Avenir-type stock should treat any future refinance as a value-hold thesis, not an income one. This one could go either way depending on whether the investor is optimizing for coverage or for price growth.
The Tenant Base Behind the Rent Rolls
Rental demand here rests on employment, not on a university. The city’s population is 60,959 per U.S. Census Bureau data, with median household income of $106,947. Palm Beach Gardens Medical Center anchors healthcare employment locally, and the wider Tenet-owned Palm Beach Health Network Physician Groups employ 5,734 people across six county facilities. Anspach, a DePuy Synthes company, and Aurora Diagnostics are headquartered in the city, per the city’s employer directory.
The research anchor is Scripps Florida in adjacent Jupiter. Florida Trend reports roughly 2,800 employees at Scripps alone after 15 years, and the Max Planck Florida Institute for Neuroscience sits on the neighboring Florida Atlantic campus. Researchers and lab staff often rent unfurnished on annual leases in their first year or two, which supports the income figure a DSCR file needs. No residential vacancy figure for the city surfaced in the research, so investors should pull current vacancy from local comps rather than assume it.
What Working Brokers See Here
Working DSCR brokers see a recurring pattern in mixed-price suburban markets like this one: the equity looks large on the highest-priced properties, but the loans that actually clear are on the lower-priced attached and small multifamily assets. Files stall when the borrower supplies a seasonal or furnished rent figure, when association dues were not in the coverage math, or when the appraisal lands below the borrower’s assumption and the 75 percent cap takes a bigger bite than expected. Pulling an insurance quote and the dues letter before submission tends to prevent most of those surprises.
Turning Proceeds Into the Next Deal
Cash-out proceeds are only useful if they can be redeployed at a coverage ratio at least as strong as the asset they came from. Pulling equity from a 1.1x duplex to buy a 0.9x condo swaps stable coverage for a weaker file. The cleaner sequence is to refinance the stronger-coverage asset and put the proceeds into another small multifamily or a rehab.
DSCR vs. conventional financing
Two common ways to finance an investment property in Palm Beach Gardens, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where some institutional lenders cap portfolio size at 10 financed properties, non-QM DSCR programs arranged through Lendmire’s network generally look at the subject property’s income rather than the borrower’s property count, though program terms vary. Investors holding assets in an LLC can generally use that structure, subject to lender program eligibility. The comparison with conventional financing explains why this matters for investors building a portfolio.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Palm Beach Gardens?
Qualification centers on the property’s rent covering its full monthly obligation, with 1.00 as the common benchmark. Lenders also typically look for about 6 months of ownership from title recording, a credit score at or above 620, and reserves of about 6 months. Loan size is capped at 75 percent LTV. Eligibility remains subject to lender guidelines and property review.
What are the requirements for an investment property loan refinance in Palm Beach Gardens, Florida?
Expect an appraisal, a lease or rent schedule, proof of insurance, and reserve documentation. For condos, association dues must be in the coverage math. Unfurnished annual-lease rents should support the number, since furnished seasonal rents at PGA National run well above the annual-lease level and will not be used. Details vary by borrower, property, and loan scenario.
Which Palm Beach Gardens property types work best for cash-out?
Small multifamily and attached product. A duplex or triplex in the older Highland Pines area stacks income across two or three leases, which typically produces stronger coverage than a single-family home at a similar price. Condos near the 1.0 line work but are more sensitive to dues. Golf-community houses priced above $1 million rarely clear on long-term rent.
Can a renovation increase the cash-out amount?
A renovation may support a higher appraised value, depending on comps and underwriter review, and a higher appraised value can raise the dollar amount available under the 75 percent LTV ceiling. The catch is that a larger loan also raises the monthly obligation, so coverage may fall. The smaller of the two limits controls the check, and proceeds are never guaranteed.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, which suits LLC-titled portfolios and self-employed investors. All scenarios remain subject to lender review and program guidelines. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and is a 2025 Scotsman Guide Top Mortgage Workplace.
In this market, a local appraiser would tell you the same thing: the money in Palm Beach Gardens is in the attached and small multifamily product, priced well under the golf-course headline numbers, and the deals that close are the ones where the rent roll, not the club membership, does the work.
For broader investor-financing rules and property-type coverage across the state, see Florida DSCR loans.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Palm Beach Gardens Real Estate Statistics
2. Apartment List Rent Report, Palm Beach Gardens
4. Florida Trend, The Cluster Conundrum
5. Zillow
7. Apartment List’s PGA National data
9. Redfin’s multifamily listings
10. Homes.com
11. TourAvenir’s development update
12. U.S. Census Bureau QuickFacts, Palm Beach Gardens
13. City of Palm Beach Gardens Current Companies
14. Florida Atlantic University Brain Institute Partners
15. recognized by Scotsman Guide as a 2026 Top Workplace
16. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Dania Beach, Florida: Equity After Spirit’s Exit · DSCR Cash Out Refinance in Dania Beach, Florida: Equity Strategy After Spirit’s Exit · DSCR Cash Out Refinance in Doral, Florida: Townhome Equity for the Next Deal
Guides: Investment Property Cash-Out Refinance in Palm Beach Gardens, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.