
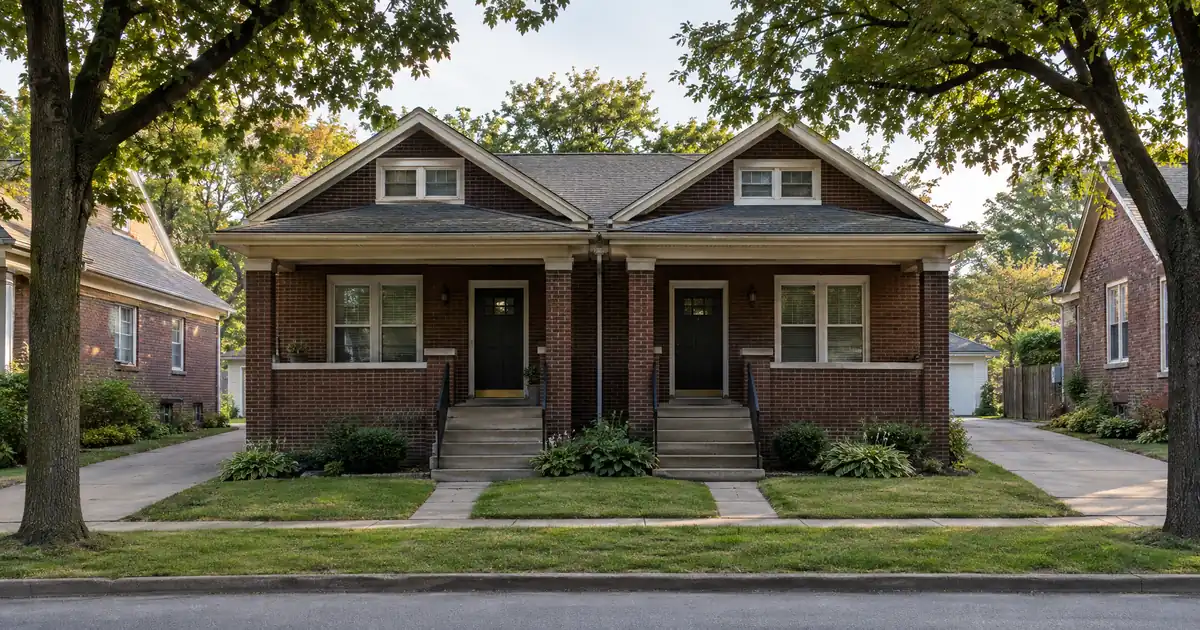
An investor owns a paid-down rental, has a next deal waiting, and can’t get the capital out. The friction is rarely credit. It’s the seasoning clock, an appraisal that comes in light, and whether the rent still covers a bigger balance once the cash comes out.
The Quick Read: A DSCR cash out refinance in Peoria, Illinois is underwritten primarily on the property’s rental income measured against its full monthly obligation. Unit count matters more than price: low-priced duplexes stack two rent checks against one balance and clear coverage more comfortably than single-family homes at similar values.
DSCR Cash-Out Calculator
Run the cash-out numbers in Peoria, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out generally tops out at 75% LTV, with about 6 months of title seasoning.
- Single-family rentals near $1,000 rent land close to the 1.00 line once taxes and insurance are in.
- South Peoria median rent sits at $664 per Redfin, which pressures single-family coverage.
- OSF and Caterpillar anchor the tenant base. Student demand near Bradley is shrinking.
- Reserves near 6 months of PITIA and a 620 credit floor are typical guideline anchors, subject to lender review.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, and Peoria, Illinois rental property investors can tap DSCR programs that Lendmire arranges, available across 41 markets, including Washington, D.C. This piece is about the owner side of the ledger: the property is already yours, and the question is how much equity can come out without breaking the coverage ratio. For the underlying program basics, see the DSCR fundamentals. Purchase mechanics are a separate topic.
Peoria Market Snapshot
A quick read on the Peoria investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $148K median (Redfin Housing Market) |
| Typical rents | $800×2 rents (Homes.com Peoria multifamily pg2) |
| Recent appreciation | +5.9% yoy (Zillow Home Value Index) |
| University enrollment | 5,217 students (fall 2023) (Bradley University) |
| Population | 115,996 population (Census Reporter) |
| Employment | 13,000+ jobs (Greater Peoria EDC) |
Where Peoria Equity Actually Comes From
Peoria equity is mostly paydown, a low purchase basis, and rehab value. Market lift contributes less than in faster-moving metros, and that shapes how aggressive a cash-out should be.
Redfin puts the city’s median sale price near $148,000 over the three months ending May, up 2.0% year over year. Zillow’s home value index runs lower, at $136,960 and up 5.9%, reflecting a different methodology (an index of typical values rather than closed sales). Pick whichever you like. Neither describes a market where appraisals sprint ahead of your loan balance.
The county tells a different story. Peoria County median sale prices ran $179,000, up 8.8%. East Peoria, across the river in Tazewell County, shows an average home value of $186,699, up 9.3%. Appreciation is running hotter outside the city limits than inside them.
The tension is straightforward. An investor who bought a distressed duplex at a low basis and stabilized it has real equity to pull. An investor who bought at today’s price and is counting on appreciation to create it will wait a while. A cash-out that depends on a hoped-for appraisal bump is the version that falls apart.
The Math That Decides the Refinance
The refinance works if rent divided by the new full PITIA (principal, interest, taxes, insurance, and any HOA dues) stays at or above the 1.00 baseline most programs use. Peoria’s low values make that easier than in coastal markets, but only when the property has enough rent for its value.
Guidelines for this structure, subject to lender review and borrower profile:
- Leverage: cash-out tops out at 75% LTV, not the 80% sometimes available on purchases.
- Seasoning: about 6 months of ownership, measured from title recording.
- Coverage: a 1.00 minimum on rent used for lender review versus PITIA.
- Credit: tiers at 620, 660, 680, and 700, with 620 the floor.
- Reserves: about 6 months of PITIA.
- These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Modeled assumptions, not sourced market data: coverage figures below use rent divided by full PITIA, including taxes and insurance at Illinois-typical levels, at the 75% ceiling, rounded down.
Run the numbers on a duplex valued near $150,000. Assume two units at $800 each. Combined rent of $1,600 echoes what active Peoria duplex listings show, though this is not a market average. At 75% LTV, coverage lands around 1.4x including taxes and insurance. Now take a single-family home valued near $148,000 with a modeled $1,000 rent. At the same leverage, coverage sits just under 1.00. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Same price band, same leverage, opposite outcomes. The duplex has room to spare. The single-family leaves none.
A sub-1.00 file isn’t dead, but it gets harder. A lender may review a lower-LTV structure, an interest-only period, or a sub-1.00 program. Each typically asks for stronger credit, more reserves, or a smaller cash-out. Eligibility depends on lender guidelines, credit approval, and property review.
DSCR files in markets like this one typically look the same. The strongest ones are small multifamily or higher-rent single-family homes where the borrower takes less than the maximum. The weaker ones push to the full ceiling on a thin-rent house and discover the coverage number moved when taxes and insurance went into the denominator. Running the calculation on the full obligation before ordering the appraisal saves the most grief.
Mechanics beyond this live in DSCR cash-out refi mechanics, and the contrast with income-documented loans is covered in a comparison of DSCR and conventional loans.
Which Peoria Submarkets Carry a Cash-Out
Central Peoria and the Uplands/West Bluff corridor carry the best cash-out files because they combine small-multifamily stock with workforce demand. South Peoria has a more affordable dirt but the thinnest value for a refinance. North and Northwest Peoria offer rent but charge for it.
Central Peoria and the Uplands. Redfin lists Central Peoria’s median rent at $993. Listing data shows duplex units commonly renting between $800 and $1,050, and the Uplands has century-old houses already subdivided into legal duplexes. One deed and two rent checks is the structure that clears coverage. Borrowers with this property type have the most room to take meaningful proceeds.
North and Northwest Peoria. Rents run higher, with Northwest at $1,205 and North at $992 per Redfin, and prices move up with them. Multifamily in North Peoria carries a median near $222,450, per Homes.com. That favors appreciation-led thinking over pure cash flow. These are good collateral, but the coverage cushion is thinner than in the cheaper core.
South Peoria. Here the picture is mixed, and the honest answer is “it depends.” Rent.com shows South Peoria one-bedrooms near $649 and Hamilton Park near $675. The ratio of rent to price looks attractive, but a very low value means a small loan. That raises the question of whether the balance qualifies at all, since the network’s standard programs run up to $3,000,000 and smaller balances route through select lenders. Check the loan size before getting excited about the ratio.
Skip the Student-Only Play
Bradley University enrollment has fallen below 5,000, to about 4,800, per WCBU. The first-year class is shrinking faster: 632 in the most recent fall, down from 811, 835, and 1,040 in the years before. Roughly 35% of students live off campus, per Rentable, concentrated in West Bluff, Downtown, and Central Peoria.
That is a real tenant pool, but a shrinking one. A property that depends only on it carries a risk lenders and appraisers will notice. Treat student demand as a bonus on top of workforce tenants, not the reason the file works.
The Tenant Base Under the Collateral
Peoria’s rental demand rests on hospitals and a heavy-equipment manufacturer rather than a single employer, which is the sturdiest kind of collateral story for a long-term-lease file.
OSF HealthCare is headquartered here and accounts for over 13,000 jobs, almost half the regional healthcare workforce. Caterpillar employs about 12,000 people in the region. OSF Saint Francis is the Level I trauma center for a 26-county region, per Wikipedia, and the hospital campus added a $237 million cancer institute with proton beam therapy. The city proper counts 115,996 residents inside a metro of 365,668.
Vacancy data is thin at the city level. Statewide, Illinois rental vacancy hit a record low near 5.70%, per Trading Economics. But neighboring West Peoria shows a rental vacancy rate of 11.5% in Census-based data. Citywide averages don’t tell you what the block next to your building is doing. Pull submarket vacancy before assuming the statewide number applies.
Where the Proceeds Go
Cash-out proceeds work best when they become a down payment on a better-covered property, not when they replace a deal you could already afford. The cleanest recycle is pulling equity from a stabilized duplex to fund the next small-multifamily acquisition, so each refinance buys another two-rent-check building.
The decision has two sides. Taking the full 75% maximizes capital but raises the new balance, which cuts coverage on the property you’re keeping. Taking less keeps the ratio healthy and may help eligibility. A thoughtful investor weighs the next deal’s expected coverage against the margin lost on the one being refinanced. If the next deal can’t cover on its own, the cash-out becomes a way to hide a weak acquisition inside a strong one.
For broader refinance structures, including rate-and-term versus cash-out, see Lendmire’s investor refinance guide. Illinois-specific program details live on the page for DSCR loans in Illinois. As a general reminder, verify current local rules, taxes, and insurance with qualified local professionals before committing.
To see how a specific duplex would price against the ceiling, compare DSCR options or call 828-256-2183.
When the Answer Flips
The strategy flips in three situations. The first is a single-family rental under about $1,100 in rent: skip the max cash-out, or skip the refinance. The second is a property in South Peoria with a very small balance: loan-size minimums may take the file off the table. The third is a student-dependent building: expect the lender and the appraiser to notice the enrollment trend even if you don’t. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
For everything else, the rule is simple. Own the duplex, keep the seasoning clock honest, and run coverage on the full obligation before the appraisal gets ordered.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Peoria, Illinois?
The property’s rent must cover its full PITIA at roughly 1.00x or better, using a baseline that varies by lender. Typical guidelines add about 6 months of ownership from title recording, a 75% LTV ceiling, a credit floor near 620, and reserves around 6 months of PITIA. Final eligibility depends on lender guidelines, credit approval, and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Peoria, IL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for a cash-out refinance on a Peoria duplex or fourplex?
The same core guidelines apply, but multiple units help coverage because combined rents sit against one balance. Lenders review leases or market rent for each unit, plus the appraisal and reserves. Equity available depends on rent used for program review, PITIA, reserves, and the 75% ceiling, so it’s never a guaranteed cash figure.
Does a South Peoria rental have enough value to support a cash-out?
Sometimes, but the low values cut both ways. The rent-to-price ratio looks strong, but a small balance may fall below standard-program loan sizes and route through select lenders. Confirm the likely appraised value and loan size first, since that decides whether a refinance makes sense at all.
Can a LLC-owned Peoria rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans, and DSCR review centers on the property’s rental income rather than the borrower’s personal income documents. Entity titling and vesting requirements vary by program.
How much does Bradley’s enrollment decline matter for a West Bluff duplex?
It matters if students are the only tenants. Enrollment is falling, so a building that leans entirely on them carries more vacancy risk. Properties that also draw hospital, manufacturing, and other workforce tenants rent more reliably, and they’re easier to defend in a cash-out review.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
Peoria Versus East Peoria
East Peoria is appreciating faster, with values up 9.3% against 2.0% inside Peoria proper, but it also costs more to own. For a cash-out built on coverage, the math favors Peoria’s lower-priced duplexes right now. For a cash-out built on appreciation, the nod goes across the river.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines. That works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
2. Redfin
6. Census Reporter — Peoria IL
8. Listing data
9. Homes.com
10. Rent.com
11. WCBU
12. Yahoo Finance — Bradley University Continues See Decline
13. Rentable
14. Yahoo Finance — 20 Largest Employers Peoria Area
15. Wikipedia
16. hladvisors.com — Hla Development Update Peoria Illinois
19. 2025
20. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Peoria, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.