
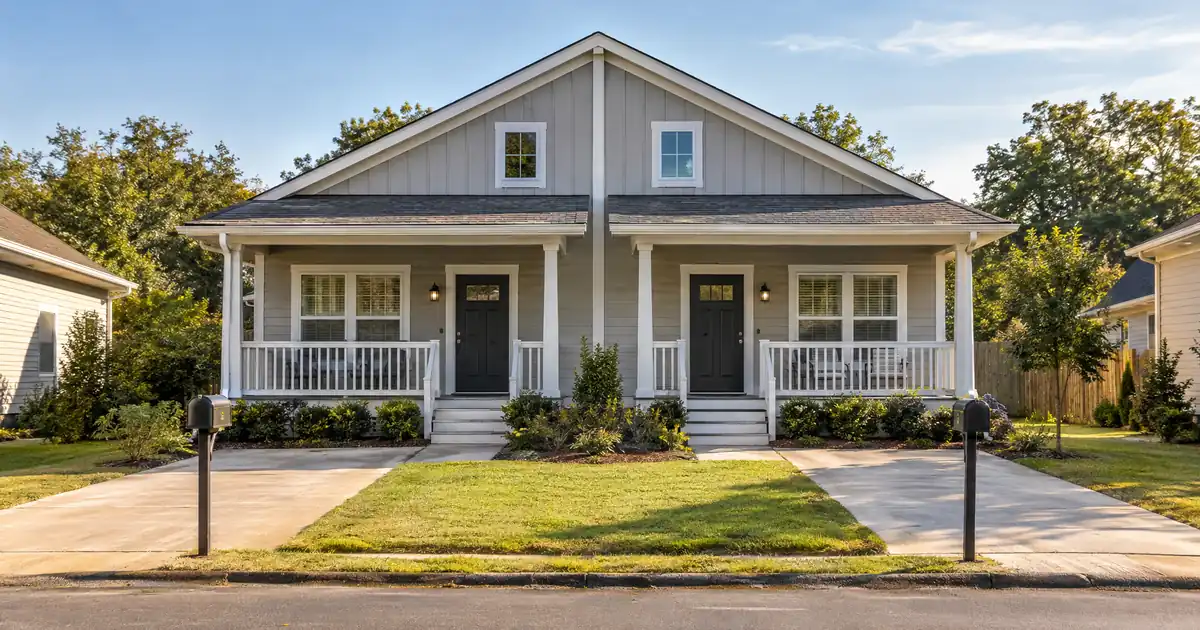
The Quick Read: Yes, usually. An empty second unit does not disqualify a VA cash-out. What drives lender review is that you live in the duplex. The vacancy changes how a lender counts income, not whether the property is eligible. Our reading is that the lender ignores the empty unit’s rent and qualifies you without it. That is the safer route.
Here is the longer version, because the details decide the file.
Why Does Occupancy Decide a VA Cash-Out?
Occupancy is the gate. VA’s cash-out refinance page lists three conditions: a Certificate of Eligibility, meeting VA and lender standards for credit and income, and living in the home you are refinancing. Nothing on that page mentions whether the other unit has a tenant.
The VA cash-out is a program for a home you live in. A duplex where you live in one unit fits. A duplex where you live in neither does not.
The VA guidelines don’t spell out a rule that either permits or bars an empty unit in a 2-4 unit cash-out. So nobody should tell you VA has a “vacant unit rule.” It has an occupancy rule, and the vacancy shows up in underwriting.
Lendmire’s VA cash-out refinance program page covers the basics of how the loan works. This article stays on the vacancy question.
Which Unit Is Empty? It Changes Everything.
There are two different situations, and most online answers blur them. An empty rental unit is an income question. An empty unit you were supposed to live in is an occupancy question. The first is usually workable. The second can stop the file.
| Factor | Rental unit empty (you live in the other) | Your own unit empty (you live elsewhere) |
|---|---|---|
| Occupancy test | Met | Not met |
| Income treatment | Rent left out, or documented | Not applicable |
| Appraisal | Value and property condition | Same, but occupancy fails first |
| Main risk | Payment must fit without rent | Loan does not fit the program |
If you moved out and the whole duplex is empty, the VA cash-out generally does not fit. The home is no longer the one you live in. Some borrowers assume they can certify intent to move back. Do not lean on that. You must be able to truthfully certify occupancy, and a misstatement on a federal loan is a serious problem.
How Does the Lender Treat the Empty Unit’s Rent?
Most files are best built by ignoring the vacant unit’s rent entirely. The full new mortgage payment then counts as your debt, and no rental reserves are required. The lender is simply asking whether you can carry the whole duplex on your own income.
That is the conservative route, and it is the one we steer most vacant-unit files toward. An unrented unit is a real cost, not income.
Counting the rent is possible but harder. The older VA Lenders Handbook text on underwriting counts 75% of the lease or rental agreement amount for an existing rental property, unless a higher percentage can be documented. That text is dated, so treat it as background and let the lender confirm current treatment. The key word is lease. A vacant unit has none. Counting its rent depends on the lender and the appraiser supporting it, and many lenders will not go there.
Your own unit’s rent never counts. You live there.
Can You Use the Cash-Out Money as Reserves?
No. If a lender counts rental income, it requires cash reserves, and those funds must be your own money in the bank before the new loan closes. The VA Lenders Handbook, Chapter 4 bars cash-out proceeds from counting toward required reserves.
How many months of reserves a lender wants varies by lender and by the loan file. Another reason to leave the rent out: no rental income, no rental reserves.
What Do the Appraiser and Underwriter Do With an Empty Unit?
The appraiser sets the home’s reasonable value and checks minimum property standards. The underwriter then tests your residual income and debt-to-income. A VA cash-out can reach 100% of the appraised value, including the financed funding fee, subject to lender guidelines and full file review.
Three things to expect with a vacant unit:
- Condition matters. Many lenders apply minimum property standards to every unit, vacant or not. A unit with a dead furnace or a leaking roof can mean required repairs before closing.
- No lease, no paper rent. On 2-4 unit homes the appraisal often adds a rent schedule. That is market support for value, not proof of income.
- Residual income decides. Residual income is what is left of your monthly income after taxes, housing, debts and a living-cost allowance for your family size and region. In our files it is the controlling test. The 41% debt-to-income figure is a guideline, not a cap. A higher ratio needs residual income well above the table. VA training material also recognizes compensating factors like strong residual income and meaningful savings.
Here is a quick thinking-out-loud point. A file that only works if both units are rented is fragile. If a tenant leaves in month three, you still owe the whole payment. Underwriters know it, and so should you.
Scenario Table: Where Does Your Duplex Land?
These are our general readings, subject to lender guidelines and full file review. They are not approvals.
| Your situation | Generally eligible? | What the lender looks at | Next step |
|---|---|---|---|
| You live in one unit, other is empty | Usually | Income without that rent, condition | Qualify on your income alone |
| Tenant just left, between leases | Usually | Same as above, plus repair needs | Qualify without the rent, or sign a lease first |
| Unit empty for renovation | Possibly | Property standards, repairs | Finish work, or expect repair conditions |
| You moved out, both units empty | Generally no | Occupancy fails | Consider other options |
| You live in neither unit | No | Not your home | Different loan type |
| Five or more units | No | Outside program size | Different loan type |
A Worked Example
Say a veteran with full entitlement owns a duplex and lives in the upstairs unit. Downstairs is empty after a tenant moved out. The veteran wants a cash-out that pays off a conventional loan and pulls out equity, at no more than 100% of appraised value.
The lender leaves the downstairs rent out. The whole new payment goes into debt-to-income. Because the new balance includes the cash-out and the financed funding fee, the payment is higher than the old one. Residual income is the real test, and the file clears only if income carries the full payment.
The funding fee on a cash-out is 2.15% on first use and 3.3% on later use, unless the COE shows an exemption. It can be financed. A veteran receiving compensation for a service-connected disability is exempt.
Also note that the loan must show a net tangible benefit, and seasoning applies if the current loan is already VA-backed. Replacing a non-VA loan with a VA loan counts as a cash-out refinance, even if you take no cash. On the wholesale side, we generally see a decision-score floor of 580, with a full file review beyond that.
If a VA Cash-Out Does Not Fit, What Else Is There?
Three paths: lease up first, wait, or use a different program. If a tenant is about to sign, waiting may turn a vacant-unit file into a documented one. If your own unit is the empty one, a different home loan type may fit, depending on how you use the property. Occupancy decides the leverage, and a non-owner-occupied property does not qualify for VA financing at all.
If you only want a lower rate or a different term on an existing VA loan, the IRRRL is a separate streamline. It refinances an existing VA loan, charges a 0.5% fee unless exempt, needs a net tangible benefit, and cannot produce cash.
What Documents Should You Gather?
A typical vacant-unit file includes:
- Certificate of Eligibility
- Proof you live in the duplex
- Income documents
- Bank statements for reserves, if rent is counted
- Statements for debts being paid off
- Repair records for the empty unit
- Landlord history or a property-manager agreement, if applicable
Lenders’ lists vary a bit, so ask for yours up front. Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Related Reading
If you have already used your benefit, Lendmire’s piece Can You Do a VA Cash-Out in Year One of an Existing VA Loan? covers seasoning in more detail.
Key Terms Defined
Certificate of Eligibility (COE): The VA document that shows your entitlement and any funding fee exemption.
Residual income: The money left each month after taxes, housing costs, debts and a family-size living allowance.
Funding fee: A VA charge that can be financed into the loan and is waived for exempt veterans.
Net tangible benefit: A real, measurable gain the refinance must give you.
Seasoning: A required waiting period tied to your current loan’s payment history.
Reasonable value: The appraiser’s value, which sets the ceiling for the loan.
Frequently Asked Questions
Does a vacant unit disqualify a VA cash-out?
No. VA’s test is that you live in the home you are refinancing. An empty rental unit changes how the lender counts income and may trigger condition checks. It does not make the duplex ineligible by itself.
Can I count the empty unit’s rent to qualify?
Rarely. Existing rental income is generally counted at 75% of a lease unless a higher share is documented, and a vacant unit has no lease. Most lenders qualify you without it, which means the full payment counts against you.
What if I moved out of my unit?
Generally the VA cash-out stops fitting. You must live in the home, and you must be able to certify that truthfully. An active-duty borrower may have special options, and you should ask a loan officer about them before assuming anything.
Does the vacant unit have to pass inspection?
Often, yes. Many lenders apply VA minimum property standards to the whole building. Repairs may be required before closing, so a unit with deficiencies can slow or stop the file.
Is a VA cash-out the same as a streamline refinance?
No. The IRRRL only refinances an existing VA loan and cannot produce cash. The cash-out can pay off any loan type and reaches up to 100% of appraised value, subject to lender guidelines.
If you are weighing a cash-out refinance against keeping the loan you have, Lendmire can help you compare the programs and the equity each one reaches.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage broker that arranges FHA, VA, conventional and jumbo home purchase and refinance financing in 16 states through wholesale lenders. Every option is subject to the lender’s guidelines and full underwriting. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. VA.gov: Cash-out refinance loan
2. VA Pamphlet 26-7, Chapter 4 (older WARMS PDF)
3. VA Lenders Handbook, Chapter 4: Credit Underwriting
This article is part of Lendmire’s VA Loans series — every loan program’s qualification details, guidelines, and scenarios live on the loan options page.
Related reading: How to Qualify for a 2-4 Unit VA Cash-Out on Residual Income Over DTI · VA Cash-Out Requirements for a Fourplex You Live In · Can a VA Cash-Out on a Condo Skip the Appraisal?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.