
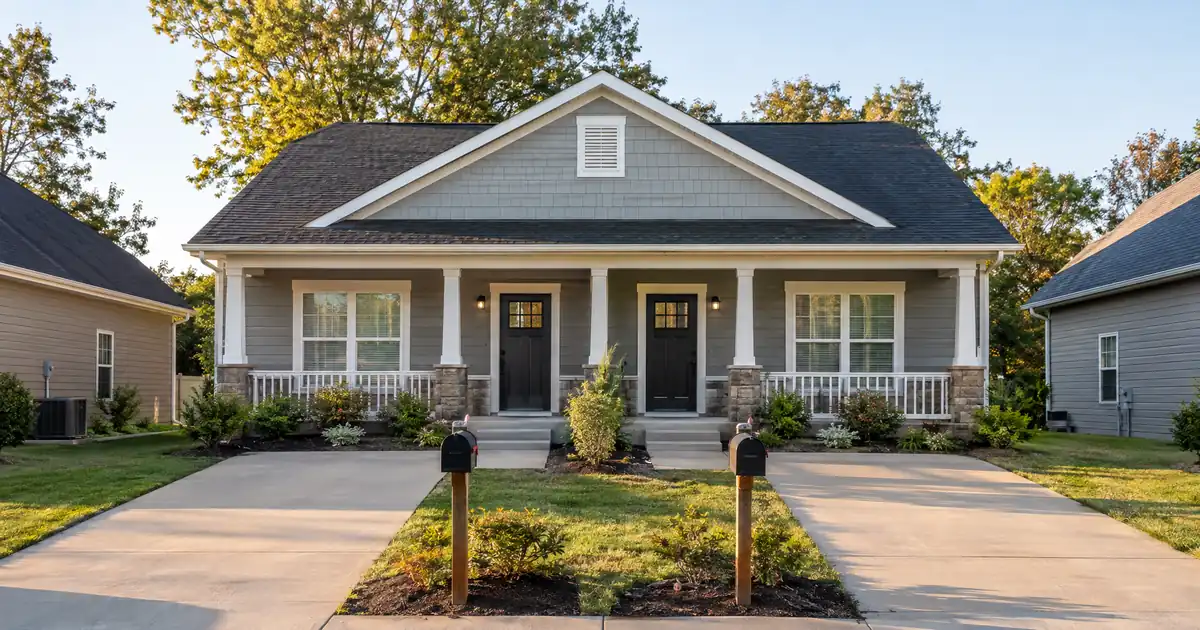
The Quick Read: For a duplex you will live in, FHA fits buyers with thinner savings or a lower credit score. Conventional fits buyers with stronger credit who want mortgage insurance that can end. Both require you to live in one unit. Neither lets the rent from the other unit cover your payment dollar for dollar.
House hacking means buying a small multi-unit building, living in one unit, and renting the other. A duplex is the simplest version. This article referees the two most common ways to finance it.
FHA payment estimate
Starting assumptions reflect an example price and the FHA minimum investment. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not an FHA loan quote.
Illustrative starting assumptions: a $350,000 price, the FHA minimum investment as the down payment, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not an FHA loan quote; your rate is set by the lender at lock. FHA mortgage insurance follows HUD’s published schedule for the term, leverage and loan size entered; taxes, insurance and dues are editable estimates; closing costs are not included; county loan limits are not checked here. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of FHA, HUD, or the federal government.
Side-by-Side
The table compares the points that actually decide a duplex purchase. Program details are subject to lender guidelines and full file review.
| Factor | FHA | Conventional |
|---|---|---|
| Maximum financing | Up to 96.5% of value | Varies by file and unit count |
| Minimum investment | 3.5% at a 580+ score | Depends on the automated finding |
| Credit floor | 580 through the wholesale programs Lendmire uses | Often higher; varies by lender |
| Mortgage insurance | Upfront and annual premium | Private insurance, can be removed |
| Occupancy | You live in one unit | You live in one unit |
| Rental income | Counted at a reduced share | Counted at a reduced share |
| Documentation | Your income, plus appraiser’s rent schedule | Your income, plus appraiser’s rent schedule |
| Loan limits | County limits apply | National conforming limits apply |
Here is how to read it. FHA wins on entry cost and flexibility. Conventional wins on long-run insurance cost for borrowers who qualify well.
Who Each Loan Is Really For
FHA suits the buyer who has a modest down payment and a credit profile that is solid but not stellar. Across the wholesale programs we place files with, FHA can reach 96.5% financing with a 3.5% minimum investment from a 580 decision score. Seller or interested-party contributions can reach 6% of the price. A non-occupant co-borrower is also allowed.
Conventional suits the buyer with stronger credit and a bit more cash. The insurance is private, and it is not permanent. For a buyer who plans to hold the duplex for a decade, that matters.
Neither loan is an investor product. Both are owner-occupied mortgages. If you only want to own a rental and not live in it, these are the wrong tools. Occupancy decides the leverage.
How Both Loans Treat a Duplex
FHA single-family programs cover one- to four-unit properties that are your principal residence, per HUD’s Handbook 4000.1 eligibility rules. A duplex qualifies if you live in one unit.
That same handbook adds a rule for bigger buildings. Three- and four-unit properties must pass a self-sufficiency test, where the property’s net rent has to cover the full housing payment. A duplex skips that test. This is the main reason many FHA house hackers stop at two units.
Rent counts, but only part of it. Lenders do not credit you with every rental dollar. They apply a haircut for vacancy and upkeep, and the appraiser’s market rent figure drives the number when you have no rental history. The appraiser documents that rent on a small-income-property report, which is more involved than a single-family appraisal.
Conventional loans treat rent much the same way. The rent counts at a reduced share, and your full mortgage payment still sits in your debt-to-income ratio. Conventional rules also do not allow you to count rent from the unit you occupy. Fannie Mae’s guidance, updated in its 2025 selling guide announcement, spells out which rental income is allowed.
So on a duplex, you qualify mainly on your own income. The rent helps. It does not replace you.
Mortgage Insurance: The Real Fork
This is where the two paths split.
FHA charges an upfront premium of 1.75% of the base loan, usually financed into the balance. It also charges an annual premium that runs between 0.15% and 0.75% of the balance, depending on term, loan amount, and LTV. On a thirty-year loan above 90% LTV, the annual premium lasts for the whole term. At 90% LTV or below, it ends after eleven years.
Those are program facts, not prices. The point is the shape. A low down payment on FHA usually means insurance for the life of the loan, unless you refinance out of it.
Conventional works differently. Private mortgage insurance varies with your credit and down payment. It carries no upfront premium of the FHA kind. And you have rights to end it. The CFPB explains that for many mortgages you can ask your servicer to cancel once the balance is scheduled to reach 80% of the home’s original value. The CFPB also notes that FHA borrowers should ask their servicer, because the rules differ.
Here’s the catch. A strong-credit buyer often pays less over time on conventional. A borrower whose credit would price poorly on conventional can come out ahead on FHA, because FHA’s premium schedule does not shift with credit score.
When FHA Is the Better Fit
FHA tends to be the better fit when:
- Your cash is the limiting factor, and 3.5% down is the realistic number.
- Your credit score sits in the lower range, near the 580 floor the wholesale programs start at.
- Your debt-to-income ratio is tight. FHA’s base ratios are 31/43, and documented compensating factors can stretch to 40/50 at the top tier. The automated finding governs most files.
- You want to keep a duplex rather than a three- or four-unit building, and avoid the self-sufficiency test.
- A family member could join as a non-occupant co-borrower.
Honestly, the cost of FHA shows up later, not at closing. If you plan to live in the building a few years and then sell, the insurance matters less. If you plan to hold for decades, it matters more.
Property condition is the other FHA risk. FHA appraisal standards apply to the building. An older duplex with peeling paint, a failing roof, or safety hazards can stall a deal until repairs are made. Budget for that before you fall in love with a fixer.
When Conventional Is the Better Fit
Conventional tends to be the better fit when:
- Your credit is strong, so private insurance prices well.
- You can put down more than the minimum. A larger down payment can shrink or remove insurance.
- You want insurance that can be cancelled without a refinance.
- The county’s FHA loan limit is tight for the price you need. FHA limits are set by county and change every year, while conventional limits follow a separate national schedule. HUD ties FHA limits to the FHFA conforming limit, with a floor and a ceiling.
- You may later convert the building to a full rental and want a cleaner path out.
One caution on leverage. Owner-occupied multi-unit conventional financing is available with a low-to-moderate down payment, but the exact tiers depend on the automated underwriting finding and the unit count. Do not assume the numbers you saw for a single-family home carry over. Fannie Mae’s eligibility matrix sets different caps by occupancy and transaction type, and it is much tighter on cash-out refinances and investment purchases.
A Duplex Run Through Both Paths
Picture a buyer eyeing a duplex where the second unit rents for a solid amount. Run it both ways, in percentages and plain terms.
On FHA, the buyer puts down 3.5% and finances up to 96.5%. The upfront premium is added to the balance. The lender counts a reduced share of the appraiser’s market rent as income. The buyer’s own paychecks still carry the file. Reserves for a duplex are lighter than for a three- or four-unit building.
On conventional, the buyer puts down more, possibly 5% to 20% depending on the finding. There is no upfront insurance premium. Private insurance may apply and can be cancelled later. The rent also counts at a reduced share, and the full payment stays in the debt-to-income math.
Which one costs less each month? It depends on credit score, down payment, and insurance pricing. For a buyer with a middling score, FHA often comes out ahead. For a buyer with a strong score and 10% or more down, conventional often does. This is a genuine toss-up for borrowers in the middle, and a broker comparing both on your actual file will settle it.
Holding Period and Exit Plan
Think about how long you will stay before you choose.
Both loans require you to live in the building. You are signing an occupancy commitment. After you move out, many buyers keep the duplex and rent both units, and that can be done within the occupancy rules. What you cannot do is buy with owner-occupant leverage and never move in.
If you stay for years, conventional’s removable insurance usually pays off. If you may sell within a few years, FHA’s lower entry cost can make more sense.
There is also a way out of FHA insurance. Many buyers refinance from FHA to conventional once they have built equity. Lendmire’s piece FHA Cash-Out vs Conventional Cash-Out When You Already Have an FHA Loan walks through that decision. For FHA refinances, the Streamline needs no appraisal and only a limited credit review. It requires a net tangible benefit, and the premium continues. An FHA cash-out reaches 80% LTV on a home owned and occupied for 12 months before the case number. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
Common Mistakes
- Counting all the rent. Lenders count a reduced share. Plan your budget with that in mind.
- Ignoring vacancy. An empty unit still leaves you with the full payment.
- Assuming a duplex must pass the self-sufficiency test. It applies to three- and four-unit FHA properties, not duplexes.
- Skipping the county limit check. FHA limits are county-based, so look yours up before you shop.
- Underestimating repairs. Older small multifamily buildings can fail an FHA appraisal on condition.
- Treating occupancy as optional. Both programs require you to live there.
If you are weighing the FHA route more broadly, Lendmire’s FHA loan programs page covers the mechanics in more depth.
Key Terms Defined
House hacking: buying a small multi-unit home, living in one unit, and renting out the rest.
Minimum required investment: the cash you must put into the purchase, at least 3.5% of the adjusted value for FHA.
Mortgage insurance: a charge that protects the lender if you default. FHA’s goes to the government. Conventional’s goes to a private insurer.
Debt-to-income ratio: your monthly debts divided by your monthly income.
Self-sufficiency test: an FHA rule for three- and four-unit homes requiring the property’s net rent to cover the housing payment.
Frequently Asked Questions
Can I use FHA on a duplex if I plan to rent out the other unit?
Yes. FHA is built for this. You must live in one unit as your principal residence. The other unit can be rented, and a reduced share of its rent can count toward qualifying, subject to lender guidelines.
Does the rent fully offset my mortgage payment?
No. Lenders credit only part of the rent, and your own income and debts still drive the decision. On a duplex, there is no property-level test that replaces your income.
Is FHA mortgage insurance permanent?
Not always. On a thirty-year loan above 90% LTV, the annual premium lasts for the term. At 90% or below, it ends after eleven years. A refinance into a conventional loan can also end it. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Can I buy a duplex with a lower credit score?
FHA is usually the more forgiving option. The wholesale programs Lendmire places FHA loans with start at a 580 decision score. Conventional lenders often set a higher floor, and file approval is subject to full review.
Which loan is better if I may sell in a few years?
FHA can make sense, because the lower cash needed at purchase matters more than long-run insurance. If you plan to hold for many years and your credit is strong, conventional often costs less over time.
If you are buying a home and want to see whether an FHA loan fits your file, Lendmire can help you compare the options and what each one asks of the file.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage broker licensed for consumer lending in 16 states. Lendmire arranges FHA, VA, conventional and jumbo purchase and refinance loans through wholesale lenders; every file is underwritten by the lender under the applicable program guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HUD Handbook 4000.1 drafting table (property eligibility, self-sufficiency)
2. Fannie Mae Selling Guide Announcement SEL-2025-08
3. CFPB: When can I remove private mortgage insurance (PMI) from my loan?
4. HUD 2026 FHA loan limits announcement
5. Fannie Mae Eligibility Matrix
This article is part of Lendmire’s FHA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can a Homeowner With an FHA Loan Do an FHA Cash-Out in Texas? · Can You Get an FHA Loan With Minimum Down at a Lower Credit Tier? · Can You Get an FHA Loan With a High DTI After a Conventional Denial?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.