
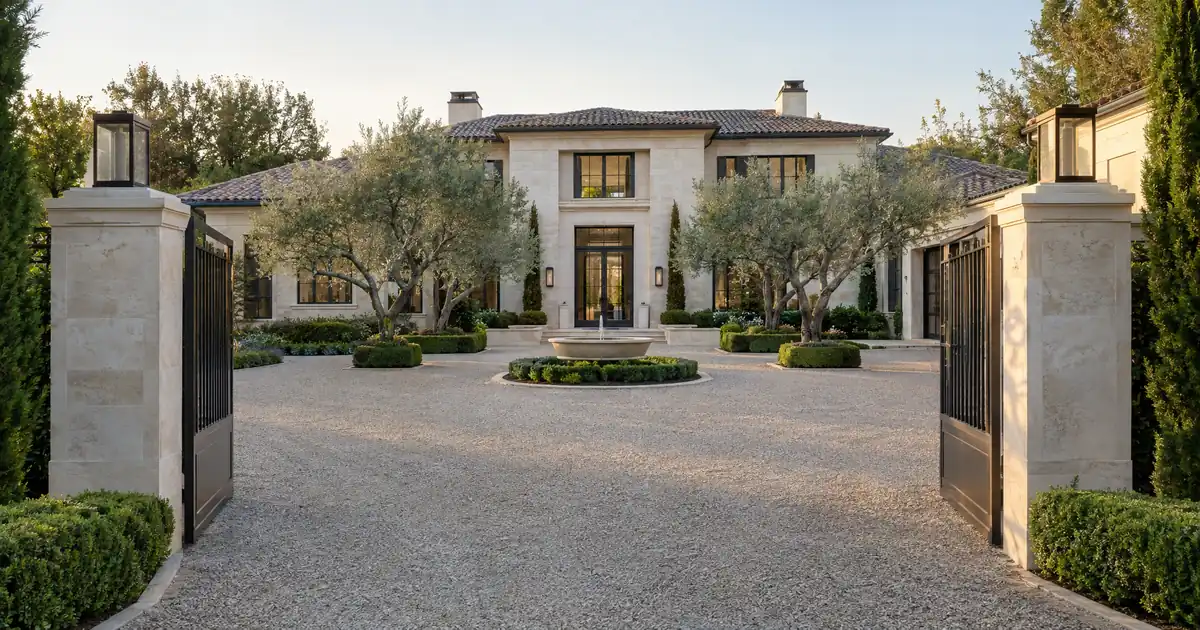
Second-Home Financing In Steamboat Springs — The Quick Read: A genuine second home in Steamboat Springs — one you’ll actually use part of the year — cannot be financed with a DSCR loan, because DSCR programs qualify a property’s rental income, not the owner’s own cash flow. For a business owner whose traditional personal-income documentation understate real income, the practical path is a bank-statement loan, which is reviewed against deposits instead of a W-2 or adjusted gross income. Get the occupancy call wrong and the file can unravel late, so it’s worth nailing down before you write an offer.
Key Takeaways
- A second home is defined by part-time personal use and your exclusive control over who stays there — not by distance from your primary residence.
- Rental income generally can’t help you qualify for a second-home loan, even if the property could clearly produce it.
- Business owners with strong deposits but light taxable income typically qualify through 12 or 24 months of bank statements instead of traditional personal-income documentation.
- Steamboat’s short-term rental overlay zones and licensing rules can reclassify a property from “second home” to “investment property” on the lending side, independent of how the local ordinance treats it.
- Loan sizing in this space runs through two overlapping programs — one topping out near $6,000,000 and a second carrying larger files on its own leverage ladder to $30,000,000, with everything above $4,000,000 reviewed case by case.
What Actually Counts as a Second Home?
Occupancy — not price, not location — is what separates a second home from an investment property, and getting this wrong is the single most common mistake self-employed buyers make in a resort market like Steamboat.
The industry-wide framework for sorting properties into principal residence, second home, or investment property comes from Fannie Mae’s Selling Guide, and even though bank-statement and DSCR loans never touch Fannie Mae directly, non-QM lenders lean on the same vocabulary. Under that framework, a second home is a one-unit property you’ll occupy part of the year, suitable for year-round use, under your exclusive control, and not part of a rental pool. An investment property, by contrast, is one you own but never occupy at all.
Here’s the part that trips people up: if the property could realistically generate rental income, most lenders still won’t let that income help you qualify for a second-home loan. The two categories sit on opposite ends of the same spectrum, and mixing them up mid-transaction is a fast way to blow up a closing.
One myth worth killing early — distance doesn’t decide this anymore. A 2025 update to Fannie Mae’s second-home guidelines eliminated the old “100-mile rule,” so a mountain property two hours from your primary residence can still qualify as a genuine second home as long as personal use makes logical sense.
| Occupancy Type | Who Occupies It | Can Rental Income Help Qualify? | Typical Loan Path |
|---|---|---|---|
| Primary residence | You, full-time | N/A | Bank statement / conventional |
| Second home | You, part-time | Generally no | Bank statement |
| Investment property | Renters only | Yes, via property cash flow | DSCR |
How Underwriting Actually Treats a Bank-Statement Buyer
Underwriting on a bank-statement file starts with deposits. It doesn’t use traditional personal-income documents. Here’s how it works: the lender adds up eligible deposits over 12 or 24 months. It strips out transfers and other non-income credits. If the deposits come from a business account, the lender applies an expense ratio. Then it divides by the number of statement months. This gives a monthly income figure.
This solves a real structural problem. A business owner can have strong deposits and solid credit. But years of legitimate write-offs — home office, vehicle depreciation, equipment, meals — can shrink adjusted gross income to a number no conventional underwriter will touch. Bank-statement underwriting sidesteps that problem entirely. It works from the cash that actually moves through the accounts.
The mechanics differ depending on which account you use. Personal bank-statement review looks at eligible deposits into your personal accounts and works out which of those can reasonably be treated as income. Business bank-statement review starts from gross business deposits, but gross deposits aren’t the same as personal income — the lender has to account for what it costs to run the business before arriving at an usable figure.
Across the wholesale network Lendmire places files through, lenders generally use a standardized expense-ratio approach with a few fixed bands. Exact percentages vary by lender and program guideline. A service business with no employees gets lower ratios. A business with a small staff gets moderate ratios. A business with more employees, or any product-based business, gets higher ratios. An accountant-provided ratio can replace the fixed bands. A profit-and-loss method is also available for files where it fits better — this method is capped at a set share of gross revenue. One detail matters more than people expect: transfers from your own business into your personal account count at full value, not a discounted percentage. This helps owner-operators who pay themselves irregularly.
Statements have to be consecutive. A transaction history summary from the bank never substitutes for actual statements — underwriters want the real documents, month by month.
A genuine Steamboat second home used partly for personal enjoyment is a consumer-purpose transaction. So standard mortgage disclosure and Ability-to-Repay rules apply, the same way they would to any owner-occupied purchase. That’s a normal part of buying a home you’ll use. It’s not a reason to avoid the bank-statement path.
Key Terms Defined
Occupancy means how a property is actually used — full-time residence, part-time personal use, or pure rental — and it’s the single fact that determines which loan category applies.
Bank-statement loan is a mortgage that qualifies a borrower using deposits from personal or business bank statements instead of traditional income documentation or traditional employment income documentation.
DSCR loan qualifies a property based on whether its rental income covers the mortgage payment, expressed as a coverage ratio — rent divided by the total monthly obligation — rather than qualifying the borrower’s personal income at all.
Interest-only period is a stretch of the loan term where payments cover interest only, not principal, which lowers the required monthly outlay during that window but doesn’t reduce the balance.
Asset allowance is a qualification path that converts liquid assets into an income figure by dividing the asset balance by a set number of months, used when a borrower’s cash flow alone doesn’t tell the full story.
Sizing and Leverage: What a Business Owner Can Actually Borrow
Loan sizing on this side of the business runs from $300,000 up to $30,000,000, split across two overlapping wholesale programs, and leverage steps down as the loan gets bigger — a pattern that’s true across nearly every non-QM lender’s guidelines, not just one shop’s.
The first program is a portfolio non-QM bank-statement product that carries files to $6,000,000. The second is a bank portfolio program built for larger, twelve-month-statement files, running on its own ladder up to $30,000,000: 65% loan-to-value to $5,000,000, 60% to $10,000,000, and 55% up to $30,000,000, with interest-only available at 60% or the band’s ceiling, whichever is lower. That bank ladder starts working above $4,000,000 and overlaps the portfolio program up to $6,000,000 — above that point it stands alone.
On a second home specifically, leverage tops out around 85% purchase in the $300,000-to-$1,000,000 range with credit in the low 700s, stepping down to roughly 80% through the $1,000,000-to-$2,500,000 range, then to the mid-70s and lower as the loan crosses $2,500,000 and moves toward $4,000,000. Above $4,000,000, every file gets reviewed case by case before it’s even submitted — that’s not boilerplate, it’s how the program actually works at that size. Second-home leverage generally runs about five points lower than the equivalent primary-residence band at every size, which reflects the reduced verification of owner-occupancy that comes with part-time use.
Credit floors sit at 660 on the portfolio program and 680 on the bank program, climbing to a firm 700 above the super-jumbo threshold. Debt-to-income can run as high as 50% on most files. Reserve requirements scale with loan size — three months of payments up to $500,000, six months up to $1,500,000, and nine months above that, plus two additional months for each other financed property, capped at twelve. First-time investors are typically asked for a full twelve months regardless of loan size.
There’s also an asset-based path worth knowing about if income documentation is thin even by bank-statement standards. An asset allowance divides liquid assets by 36, 60, or 84 months to generate a qualifying income figure, and an assets-only path requires liquidity equal to the loan amount plus closing costs with no debt-to-income calculation at all. Retirement accounts count at 70%, rising to 80% once you’re past 59½; business funds, gifts, and unvested stock generally don’t count toward either path.
Where the Second-Home Rule Breaks in Steamboat
The clean occupancy split between second home and investment property gets messy fast the moment short-term rental use enters the picture — and Steamboat’s own regulatory structure is exactly the kind of thing that forces the question.
It’s unlawful to operate a short-term rental inside city limits without a license. This follows the City Council’s 2022 overhaul of the municipal code, which created an STR Overlay Zone and Licensing Program. The city is split into zones with different caps. One zone allows unrestricted licensing. Others are capped or closed. Outside city limits, unincorporated Routt County flips the default. It generally prohibits rentals under thirty days without a special permit.
That local structure directly touches how a file gets underwritten. If your plan is to occupy the Steamboat property part of the year and rent it out the rest of the time on Airbnb or VRBO, most lenders will treat that as investment-property use, not second-home use, regardless of your personal-use intent — because a management agreement or booking-platform arrangement hands control of occupancy to someone else. That reclassification changes leverage, reserves, and pricing across the board.
The appraisal itself reinforces this line. When rental income qualifies a DSCR loan, the appraiser uses a standardized rent schedule — Form 1007 for a one-unit property. This form calls for an actual monthly-lease market rent. It’s not a nightly rate multiplied by thirty. Appraisal-industry guidance is explicit on this point: doing the math that way ignores personal-property costs, business expenses, and vacancy patterns baked into a real short-term rental operation, according to trade coverage from McKissock Learning. That’s part of why lenders financing short-term-rental collateral generally skip the 1007 process entirely. Instead, they lean on platform booking data — a different rent basis than a traditional long-term lease in the same market.
A DSCR path becomes the right conversation once the plan is genuinely rental — not occasional personal use dressed up as an investment. Investors building out a portfolio of pure rentals in a market like this generally move to DSCR after the second or third property, since there’s no equivalent to a ten-property agency cap on the non-QM side. Lendmire’s complete DSCR loans guide walks through how that qualification runs on the property’s own income rather than the owner’s.
Nonconforming legacy STR status is worth flagging too. Some existing Steamboat rentals were grandfathered when the 2022 ordinance passed, as part of a broader strategy to phase out short-term rentals in certain residential neighborhoods over time. A buyer relying on that status should confirm the license actually transfers with the sale rather than assuming it does — licenses tied to inactivity can lapse.
Running the Numbers: A Business-Owner Scenario
Picture a founder with a service business generating solid personal-account deposits but an adjusted gross income that a conventional underwriter would reject outright, thanks to legitimate deductions. She wants a Steamboat property she’ll use eight to ten weeks a year and keep off any rental pool the rest of the time.
Because the intended use is genuine part-time occupancy under her exclusive control, this is a second-home purchase, not a DSCR file — rental income, even if the property could produce it, wouldn’t be counted toward qualification anyway under most lender guidelines. Her qualifying income comes from 24 months of personal bank statements, with eligible deposits reviewed and non-income transfers stripped out. At a purchase price in the low-$1,000,000s, second-home leverage on most files in that band runs around 80% with credit in the high 600s to low 700s, subject to full underwriting and lender guidelines — never a guarantee, and always confirmed at application.
Now flip the scenario. Say a different business owner buys a comparable property with the explicit intent of running it as a licensed short-term rental and never staying there personally. That’s a pure investment purchase, and it moves onto the DSCR track — qualification runs off the property’s own rent coverage rather than the buyer’s deposits, with the appraisal (or, more likely for a licensed STR, platform booking data) setting the income figure that drives the coverage ratio.
Local market conditions matter to how that second scenario pencils. Recent local reporting describes the Steamboat market as the most balanced it’s been in years heading into the most recent selling season, with single-family median prices near $1,000,000, rising inventory, and longer time on market — a shift from the tighter conditions of prior years, per a local market report. That’s useful context, not a national trend — the mechanics above apply the same way in any market, but the price level and rent comparables that feed a DSCR coverage ratio are entirely local and need to be pulled fresh for the specific property.
Short-term rental rules can vary by city, county, HOA, and property type, so investors should confirm local rules before relying on projected rental income in any coverage calculation.
Common Missteps Worth Avoiding
A few misconceptions come up often enough with business-owner buyers that they’re worth naming directly.
“I’ll just close it as DSCR and use it myself sometimes.” The zero-occupancy certification a DSCR loan requires is a firm commitment, not a formality — occasional personal use doesn’t fit inside it.
“An appraiser can multiply the nightly Airbnb rate by thirty to set my rent.” That approach is explicitly disfavored under the governing appraisal guidance, because it skips vacancy, business expenses, and personal-property costs baked into short-term operations.
“Bank-statement loans are the same as 2006-era stated income.” The modern version still requires actual bank statements, deposit-level review, and — on a consumer-purpose second home — full Ability-to-Repay compliance the same as any owner-occupied mortgage.
Tax treatment can depend on how the property is used and titled, so investors should keep clean records and talk to a qualified tax professional before relying on any deduction assumption.
Frequently Asked Questions
Can I use rental income to qualify for a bigger second home in Steamboat?
Generally, no. Under the framework most lenders follow, rental income doesn’t count toward second-home qualification even if the property could clearly produce it. If the plan includes meaningful rental income, that points toward an investment-property purchase and a DSCR structure instead.
Does a management company or co-host arrangement change how the loan is classified?
It can shift the classification. If a management agreement gives someone else control over who occupies the property or when it’s rented, many lenders will treat the file as an investment property rather than a second home, even if you also plan to use it personally.
How many months of bank statements does qualifying actually require?
Most files run on 12 or 24 consecutive months of personal or business statements, with an expense ratio applied to business deposits before the income figure is calculated. Twelve-month files are used on the larger bank portfolio program; the smaller portfolio product typically works with either window depending on the file.
What happens if my loan amount is above $4,000,000?
Everything above that threshold gets reviewed case by case before submission — leverage, documentation depth, and reserves all get evaluated on the specific file rather than off a published grid. It’s a real underwriting step, not a formality.
Is Steamboat Springs financing available everywhere, or only in certain states?
Consumer mortgage lending through this program is currently licensed in 16 states, including Colorado. Availability, terms, and eligibility depend on the specific property, borrower profile, and lender guidelines at the time of application.
Are you weighing a second-home purchase against an investment-property play in a resort market like Steamboat? Lendmire can help. We’ll compare bank-statement and DSCR structures side by side, based on how you actually plan to use the property, your documentation, and your leverage goals.
For current guidelines and terms, see Lendmire’s super jumbo bank statement loan programs page.
About Lendmire
As a non-QM mortgage broker (NMLS# 2371349), Lendmire facilitates DSCR investor loans across 40 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income instead of personal income documentation, subject to lender guidelines, serving LLC-structured portfolios and self-employed borrowers who don’t fit conventional boxes. A two-time Scotsman Guide Top Mortgage Workplace (2025, 2026).
Lendmire’s Top Mortgage Workplace recognition is documented by Scotsman Guide 2025 Top Mortgage Workplace and Scotsman Guide 2026 Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Selling Guide – Occupancy Types
2. Steamboat Springs Official Website – Rules and Regulations
3. Fannie Mae Form 1007 (official form)
4. McKissock Learning – Form 1007 & STR Appraisals
5. Real Estate in Steamboat – Market Report
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.


