
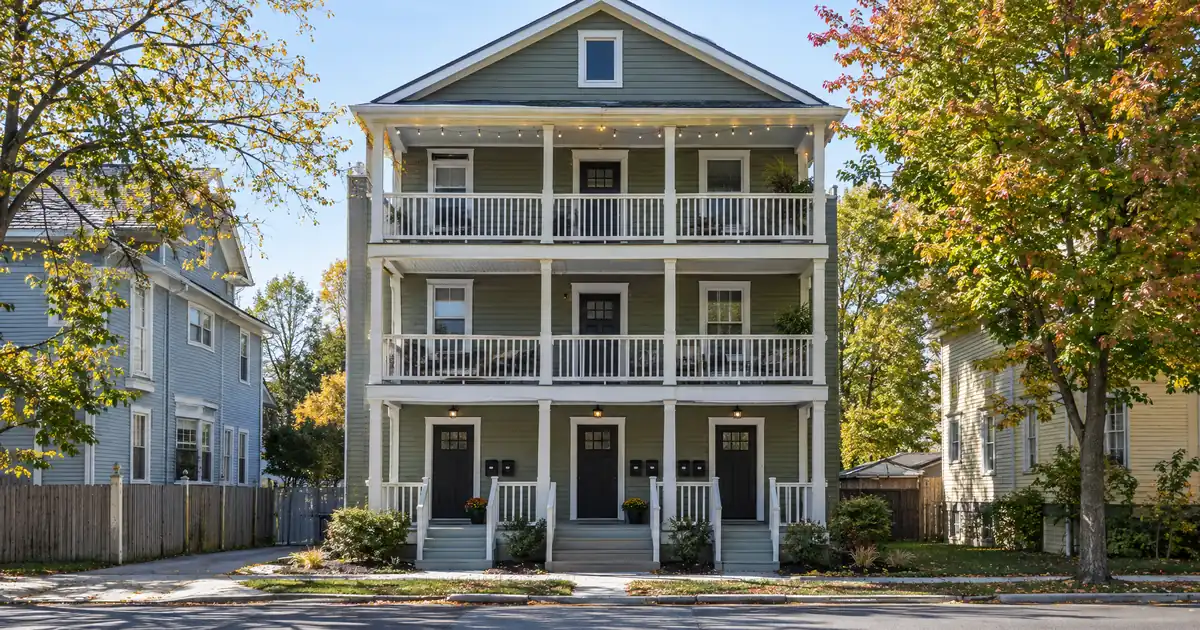
The Quick Read: It can work, but it depends on your credit score, the way the file is underwritten, and how many units the building has. DTI (debt-to-income) is your monthly debts divided by your gross monthly income. FHA has no single hard ceiling on it. On a duplex, rent from the unit you don’t live in can help your ratios. On a triplex or fourplex, the building’s own rent must also pass a separate test.
Why a High DTI Isn’t an Automatic “No” on FHA
FHA is built to be flexible. The base ratio pair is 31/43. That means your housing payment is about 31% of gross income and your total monthly debts about 43%. Those numbers apply when the file has no compensating factors.
FHA payment estimate
Starting assumptions reflect an example price and the FHA minimum investment. Replace them with your own figures.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not an FHA loan quote.
Illustrative starting assumptions: a $350,000 price, the FHA minimum investment as the down payment, a thirty-year term at the current Freddie Mac benchmark, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not an FHA loan quote; your rate is set by the lender at lock. FHA mortgage insurance follows HUD’s published schedule for the term, leverage and loan size entered; taxes, insurance and dues are editable estimates; closing costs are not included; county loan limits are not checked here. Licensed in sixteen states for consumer mortgages. Lendmire is not affiliated with or acting on behalf of FHA, HUD, or the federal government.
Compensating factors are documented strengths that offset a stretched ratio. Cash reserves are one. A small payment jump from your current rent is another. Across the wholesale programs Lendmire places FHA files with, documented factors can reach a 40/50 pair at the top credit tier. The automated finding governs most files, and the manual matrix comes into play when it doesn’t.
Here’s the catch. Those higher ratios depend on a decision score of 580 or higher. The wholesale programs Lendmire works with start at 580. Below that, HUD (the agency that runs FHA) holds manual files to the base 31/43 pair and a bigger minimum investment, and compensating factors don’t lift those ratios. HUD says so in Mortgagee Letter 2026-11. Its FHA Resource Center repeats the point.
So the score comes first. A high DTI with a 580+ score is a conversation. A high DTI with a score under 580 is usually a different path.
How FHA Works on a 2–4 Unit Home
FHA finances one- to four-unit homes. You must live in one unit as your principal residence. That is the owner-occupant rule, and it separates this from a purchase of rental property. A non-occupant co-borrower is allowed on the loan.
The core purchase terms on the FHA loan programs Lendmire arranges:
- Maximum financing is 96.5% of the lesser of price or appraised value.
- The minimum investment is 3.5%, at a score of 580 or higher.
- Seller or interested-party contributions can run up to 6% of the price.
- County loan limits apply, and they rise with unit count.
Mortgage insurance comes with the loan. There is an upfront premium of 1.75% of the base loan, which can be financed. There is also an annual premium between 0.15% and 0.75% of the balance. It depends on term, loan amount and LTV (loan-to-value, the loan as a share of the home’s value). On a thirty-year loan above 90% LTV, the annual premium lasts for the term. At or below 90%, it ends after eleven years.
With a stretched DTI, that premium matters. It is part of your monthly housing cost, so it goes into the ratio.
Where Rent Enters the DTI Math
The unit you live in produces no rent. The other units do. For a two- to four-unit home, FHA lets the lender count rental income from the other units toward qualifying. It does not count all of it. Lenders generally credit a portion of the appraiser’s market rent, not what you hope to charge. The exact treatment follows the lender’s guidelines, so ask for it in writing on your file.
Two things to know:
1. The appraiser sets the number. The appraisal reports market rent for each unit. Your lease, your listing and your hopeful estimate don’t override it.
2. Rent helps the ratios, but it doesn’t erase debt. Your car loan, student loan and card payments still count in full.
For many buyers, this is the main lever. A file that is too stretched as a single-family purchase can look much better as a duplex. The building brings its own income to the table.
Worked Example: One Buyer, Four Buildings
This is an illustration with no dollar figures. It is not a prediction for any file. Picture a buyer with a 640 score, steady traditional employment income and a total ratio well past 43% on a single-family purchase.
| Building | What changes | Likely effect on the file |
|---|---|---|
| Single-family | No rent to count | Ratio stays stretched |
| Duplex | One rented unit adds counted income | Ratio improves, no rent test |
| Triplex | Two rented units, plus a rent test | Ratio improves, second gate applies |
| Fourplex | Three rented units, plus a rent test | Best ratio help, strictest property test |
The buyer’s income doesn’t change. Only the building does. That’s why the same person can get a different answer on a different property.
The Two Gates on a Triplex or Fourplex
A duplex has one gate: you. A triplex or fourplex has two, and they are separate pass/fail checks.
Gate one is your DTI, as described above.
Gate two is the self-sufficiency test. The test asks whether the building can pay for itself. The lender takes the appraiser’s market rent for all units, including yours. It subtracts a vacancy and maintenance allowance. Then it checks that the full housing payment doesn’t exceed what is left.
Duplexes are exempt. Triplexes and fourplexes are not.
The gates fail independently. A strong-income buyer can pass the DTI and still fail the building test if appraised rents come in low. A building with strong rents can still fail on a buyer with heavy debt. Passing one doesn’t carry the other.
That is the practical reason to check the building with a loan officer before you make an offer. Rents are an appraiser’s estimate. You don’t learn them until the appraisal, unless someone checks first.
| Check | Tests | Applies to | Link to high DTI |
|---|---|---|---|
| DTI | Your income against your debts | All units | The high-DTI problem itself |
| Rent counted | Market rent from other units | 2–4 units | Can lower your ratios |
| Self-sufficiency | Building rent against full payment | 3–4 units | Separate gate |
| Reserves | Cash left after closing | More common at 3–4 units | Compensating factor |
| Occupancy | You live in one unit | All units | Required |
Automated or Manual Review?
Most files start with an automated underwriting system. It looks at the whole file and doesn’t use one published DTI cutoff. If it returns “Approve,” you’re usually done with this question. If it returns “Refer,” a human underwriter applies the manual matrix.
HUD has also long required manual underwriting when a lower score is paired with a total ratio above 43%, even if the automated system approves. Check the current rule with your loan officer. HUD’s Handbook 4000.1 is the authoritative source.
Manual underwriting asks for more paper. It also asks for documented compensating factors. For a house-hacker, the strongest ones tend to be:
- Verified cash reserves left after closing
- A housing payment close to what you pay in rent today
- A long, steady job history
- Little or no discretionary debt
- Rent from the other units, backed by the appraisal
A quick word on reserves. On a three- or four-unit purchase, lenders often want verified cash left after closing. The amount is set by the lender, so ask. That cash generally has to be your own, not borrowed or gifted.
Why One Lender’s “No” May Not Be the Final Word
Agencies set the floor. Lenders can add their own rules on top. Those are called overlays. One lender may stop at a score the agency would allow. Another may not.
If you are turned down, ask whether the reason is an FHA rule or a lender overlay. Brokers are useful here because they can place a file with a different lender. It is not a guarantee. Each lender reviews the file on its own terms, and every program figure is subject to lender guidelines and full file review.
If Your DTI Is Still Too High
Treat it like a short decision tree. Start at the top.
- Score under 580? Lift the score first. Credit repair can matter more than any other fix.
- Score 580 or higher, ratio still stretched? Pay down installment or revolving debt. Each payment you remove helps the ratio directly.
- Debt is already low? Look at a different building. A duplex versus a fourplex changes the rent and the property test.
- Income is the limit? A co-borrower may help. A non-occupant co-borrower is allowed, but their score and debts come into the file too.
- Appraised rent came in low? Ask the appraiser’s report what comparables it used. Then talk with your loan officer about the next step.
- Test fails on a three- or four-unit? Ask about a duplex, or about a different owner-occupant program.
When a lender explains a denial, read the reason closely. “Ratio too high” and “property didn’t meet the rent test” send you in different directions.
If you already own a home and want to use its equity, Lendmire’s piece Can a 2-4 Unit Primary Home With a High DTI Get an FHA Cash-Out? covers that lane.
Where 43% Comes From
Many buyers think 43% is a federal cap. It isn’t. The CFPB’s assessment of its ability-to-repay rule describes 43% as a threshold from the original Qualified Mortgage rule. The bureau also said borrowers above it shouldn’t be shut out of responsible credit. FHA runs its own ratio matrix, and the two don’t match.
You may also see big numbers online, like “FHA allows 56%” or “up to 57%.” Those figures appear on lender and broker sites. They are not a HUD rule you can count on. Your file’s ratios come from the automated finding or the manual matrix, and from the lender’s own guidelines.
The Tradeoffs Nobody Mentions
A fourplex can look like free housing. Be honest about the risks.
- Vacancy. An empty unit hits your budget first, and your payment stays the same.
- Stacked costs. Mortgage insurance, taxes, insurance and repairs all sit on a bigger building.
- Stretch risk. A ratio that passes on paper still has to fit your life. Lenders can approve a file you’d find tight.
- Landlord duties. You become the owner-occupant next door.
Some buyers are better off with a duplex. Less rent to count, but less to carry.
What to Prepare
A multi-unit file with a high DTI goes better with paper ready:
- Recent pay stubs and two years of traditional personal-income documentation or W-2s, as your lender asks
- Bank statements that show reserves and the source of your down payment
- A list of every monthly debt, with current balances
- Any current lease and rent history on the building, if it is tenant-occupied
- A written explanation for any credit blemishes
- A plan for which unit you will occupy
Tax treatment can depend on your situation; borrowers should speak with a qualified tax professional before relying on any deduction or credit.
Key Terms Defined
DTI (debt-to-income ratio): Your monthly debt payments divided by your gross monthly income. A “front” ratio counts housing only; a “back” ratio counts all debts.
Compensating factor: A documented strength, like reserves or a steady job history, that supports a ratio above the base pair.
Manual underwriting: A human underwriter reviews the file against the written matrix instead of relying on the automated finding.
Self-sufficiency test: A rent test for three- and four-unit homes. The building’s net rent must cover the full housing payment.
Reserves: Verified cash you still hold after closing.
Overlay: A lender’s own rule that is stricter than the agency’s.
Frequently Asked Questions
Can the rent from my own unit count toward qualifying?
No. Only rent from the units you don’t occupy counts, and the lender uses a share of the appraiser’s market rent. Your own unit is part of the self-sufficiency test on three- and four-unit homes, but not the ratio offset.
Is a duplex easier than a fourplex?
Often, yes. A duplex skips the self-sufficiency test, so you pass only the borrower gate. A fourplex gives more rent to count but adds the second gate and more reserve questions.
Can a first-time landlord with a high DTI qualify?
It can work, and being a first-time landlord isn’t a bar on its own. The lender reviews the same ratios and rent figures. With no landlord history, strong reserves and a payment close to your current rent carry more weight.
What if the appraisal rent comes in low?
It lowers the income the lender can count. On a three- or four-unit home it can also cause the building to fail its rent test. Ask your loan officer to check likely rents before you make an offer.
Can a co-borrower help?
Sometimes. A non-occupant co-borrower is allowed, and their income can support the file. Their debts and score come in too, so a weak score can hurt more than the added income helps.
Next Step
If you are buying a home and want to see whether an FHA loan fits your file, Lendmire can help you compare the options and what each one asks of the file. Run the building both ways, as a duplex and as a larger property. Only the numbers on your own file can say which one passes.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage serving homeowners and home buyers in 16 states. FHA, VA, conventional and jumbo purchase and refinance loans are arranged through wholesale lending channels; Lendmire brokers the financing and the lender underwrites each application. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. HUD Mortgagee Letter 2026-11
2. HUD FHA Resource Center: manual underwriting ratios
3. HUD Handbook 4000.1 information page
4. CFPB: CFPB Ability to Repay Qualified Mortgage Assessment Report
This article is part of Lendmire’s FHA loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can You Get an FHA Cash-Out on Acreage in a High-Cost State? · How Much an FHA Cash-Out Allows for Debt Consolidation at High DTI · Can a Homeowner With an FHA Loan Do an FHA Cash-Out in Texas?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.