
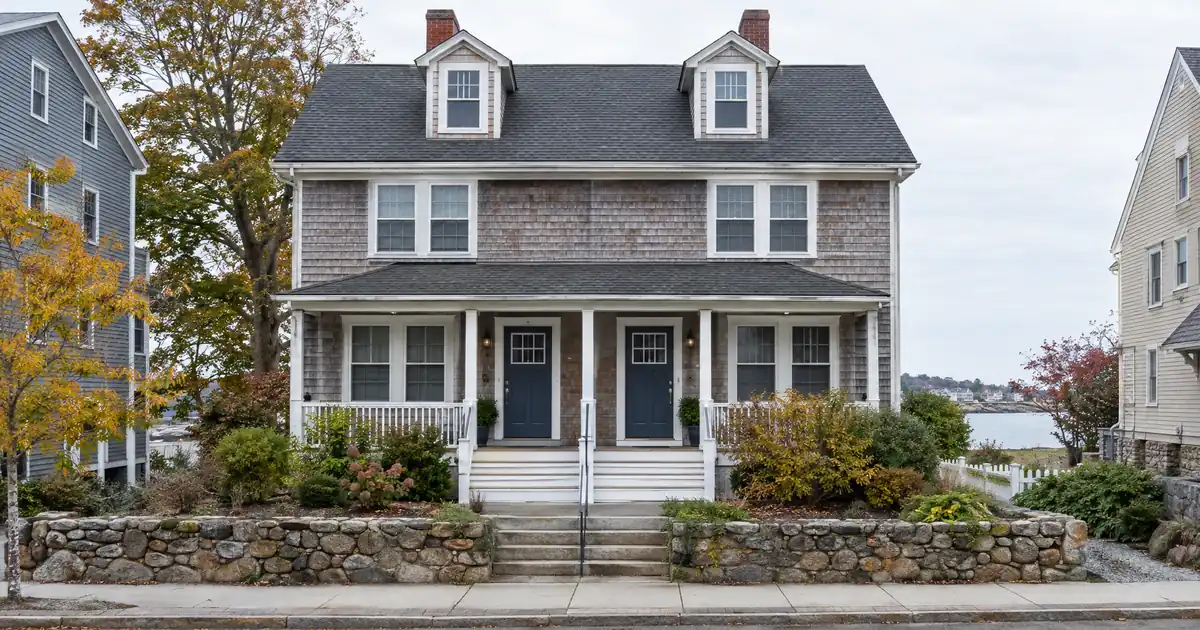
Picture an investor who owns a two-family a short walk from the harbor. It was bought years ago and has been fully rented ever since. Both leases are current, the entity paperwork is clean, and a second building is waiting on a deposit. The loan on the first property is small next to what the property would now appraise for. The question is how much of that gap can be pulled out through a DSCR cash out refinance without crushing the coverage number. The answer depends far more on which Gloucester neighborhood the building sits in than on the loan product.
DSCR Cash-Out Calculator
Run the cash-out numbers in Gloucester, MA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
Cash-out on a rental in Gloucester, Massachusetts is underwritten primarily on the property’s rental income measured against its full monthly obligation, which favors multi-unit buildings where several rents stack against one price, and Redfin shows a $699K median multi-family listing price in Central Gloucester.
- Central Gloucester is a more affordable multi-family entry among the city’s submarkets.
- Single-unit rentals near the city median rent tend to land far below 1.00 coverage.
- Cash-out LTV tops out at 75%, with roughly 6 months of seasoning from title recording.
- Expect about 6 months of PITIA in reserves, and appraisal support matters more than headline appreciation.
Gloucester Market Snapshot
A quick read on the Gloucester investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Cap rates | 7.4% cap rate (single listing) (Redfin, Central Gloucester) |
| Employment | 35,000 BILH employees (Beverly Hospital, Addison) |
| Vacancy | 0% (AffordableHousingOnline) |
Central Gloucester: Where the Equity Is Building
Central Gloucester is the strongest cash-out submarket in the city, and it isn’t close. Redfin’s neighborhood page puts the median sale price at $658K, up 18.5% year over year, on a small sample. The same neighborhood carries a Walk Score of 79 and the MBTA station. Six multi-family homes were listed at a $699K median asking price, against a citywide multi-family median of $959K across seven listings on Redfin’s citywide multi-family page.
That gap matters for an owner already sitting on a downtown two-family. A building bought at an earlier basis has likely picked up the appreciation. It also sits in the one part of town where rents stack against a price the rent can still carry. Redfin’s rental page shows a Central Gloucester median rent of $2,700, which is an all-unit median and not a 2-4 unit figure. No rent source in the research isolates small multifamily, so any coverage math here is a model and not a market fact.
One seller-advertised Central listing quoted a 7.4% cap rate on about $262,920 of gross annual income. Treat it as one seller’s marketing number, not a market cap rate. It does show that buildings with several units and documented leases exist in this pocket, and those files are the ones lenders review most easily.
What Does a 75% Cash-Out Look Like on a Central Duplex?
Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
On a modeled Central Gloucester two-family valued near the $699K median multi-family listing, two units at the $2,700 Central median would produce about $5,400 of gross monthly rent. That is a modeled assumption, not a quoted lease. At the 75% cash-out LTV ceiling, and counting taxes and insurance in the full obligation, coverage lands in the neighborhood of 1.2x. That clears the 1.00 baseline that most standard DSCR programs are built around, subject to lender guidelines and the property review.
Now run the same model on a single-family or condo rental. Rent near $3,000 against an $800K value produces coverage of roughly 0.6x with taxes and insurance included, and that is a long way from the 1.00 baseline. Some lenders review sub-1.00 files, but those usually carry lower leverage, stronger credit, more reserves or different pricing. The structures that may apply are a sub-1.00 program, an interest-only structure or a smaller cash-out request. Each is reviewed subject to lender guidelines, credit approval and property review.
The equity available is not a fixed figure. It depends on rent used for lender review, the full monthly obligation, reserves and the 75% ceiling, and the rent side limits it first. A cash-out request that pushes past what the rent supports will not be rescued by a big appraisal. For the mechanics of that calculation, the DSCR qualification mechanics page walks through rent versus PITIA.
West Gloucester: Higher Rents, Higher Basis
West Gloucester posts the highest rent in the city and a much heavier price tag. Redfin shows a median sale price of $830K, up 12.1% year over year, and a median rent of $3,200. The neighborhood has an MBTA stop and suits commuter households.
The tradeoff is easy to see. Two units at $3,200 stack up to more monthly rent than Central offers, but the value being borrowed against rises almost as fast. A modeled duplex there tends to cover in the low 1.1s to 1.2 range at 75% LTV with taxes and insurance included. That is workable, with less cushion than Central. If a West Gloucester owner is comparing that to a Central refinance, the cushion shrinks quickly if rents come in under the modeled figure. The flip point is a building with two well-documented leases at or above the West median. Then the higher rents can carry it, and the cash-out proceeds can go toward a Central purchase where the entry price is lower. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Skip the Postcard Neighborhoods
East Gloucester and Magnolia are appreciation stories, not cash-flow ones. Redfin’s East Gloucester page shows an average house price of $1.25M on a small sample, with a median rent of $2,950. Magnolia’s median sale price was $802K, up 15.4% over the three months ending May. Rocky Neck is tourism-oriented and priced accordingly.
Run two units at the East median against a value near that $1.25M average and coverage falls well below 1.00 even before leverage is trimmed. A cash-out there would need lower leverage or a sub-1.00 structure, and the underlying question is whether the owner is holding for appreciation. That is a legitimate strategy, but it is a different one from extracting equity to buy the next cash-flowing building. An investor using an East Gloucester property to fund purchases elsewhere should look at the rent-to-value gap before asking for the maximum proceeds.
Before You Trust the Appraisal Headline
Gloucester’s citywide price data conflicts across sources, and the honest move is to underwrite against the conservative end. Zillow’s smoother index puts the average home value at $791,623, up only 1.9% over the past year. Redfin’s housing market page shows a $844K median with a 29.9% annual jump, while its price per square foot is down 23.8%. Movoto reports a $942,450 median, and Redfin’s separate city page shows a $699,537 median sale price, down 6.7%. Only 44 homes sold citywide in May.
Those numbers are not all measuring the same thing. A median driven by which houses happened to sell that month can overstate value, and an appraiser working from few comps may not support the headline. Cash-out proceeds built on the +29.9% figure are a risk. Proceeds built on a value nearer the Zillow index leave room if the appraisal comes in short.
Working DSCR brokers see a recurring pattern in thin-inventory coastal markets like this one: the owner arrives with a headline appreciation number from a listing portal, and the appraisal lands closer to the last two or three comparable sales. Files that hold up best come with a conservative value assumption and coverage that still clears at that lower figure. Lease copies, entity documents, title and property details ready for lender review also help.
Seasoning matters here too. Cash-out programs typically look for about 6 months of ownership measured from title recording. An investor who closed recently and expects to refinance at a big markup should confirm how the lender treats value in that window, since program rules differ.
Who Fills the Units
Rental demand in Gloucester is deep but sits on a modest income base, and it comes from more than one employer. Renters make up about 37% of households, according to the city’s draft Housing Needs Assessment. Median renter household income is $43,466 against $121,558 for owners. The advocacy group Housing 4 All Gloucester reports that 48% of renters were cost burdened.
Those figures cut both ways. They point to steady demand for small multi-unit buildings. They also mean rent growth has a ceiling. Zumper shows a median rent of $2,675, up 7% over the last year, but underwriting rents well above the local affordability band can invite turnover, and an appraiser may discount them. HUD Fair Market Rents, which one aggregator lists from $2,359 to $3,894 depending on unit size, offer a reference band for what a lender may accept.
Employment anchors sit behind that demand. Addison Gilbert Hospital is a 79-bed hospital within Beth Israel Lahey Health, a system with more than 35,000 employees. Varian Semiconductor stayed Gloucester-based after Applied Materials acquired it. Gorton’s of Gloucester is headquartered in the city, and NOAA Fisheries’ Greater Atlantic Regional Fisheries Office is here. No current headcounts were found for the local employers, so this is a picture of tenant types and not a payroll count. The city had 29,729 residents at the last decennial count. The same housing assessment notes that 1,718 homes were bought by investors over recent decades, so rented and multi-unit comps should exist for an appraiser to work from.
Sequencing the Proceeds
The cash-out only makes sense when the next deal covers on its own. A Central Gloucester owner pulling proceeds at 75% LTV and buying another two-family in the same $699K tier can model the new building against the same coverage math. Pulling equity into a market where the numbers don’t pencil at current pricing is a different decision. It is worth stress-testing before committing. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Program guidance for this kind of file is fairly consistent, subject to lender guidelines. Credit tiers run from a 620 floor up through 660, 680 and 700. Reserves typically run about 6 months of PITIA, rising to about 9 months above $1,500,000 in loan size. Standard programs go up to $3,000,000, and smaller balances route through select lenders in the network. If the property is held in an LLC, that is generally workable subject to lender program eligibility. The cash-out refinance details page covers the structure, and Lendmire’s refinance programs cover the options for rate-and-term files. Investors weighing this against a conventional refinance can compare the tradeoffs between DSCR and conventional financing. Conventional may be the cheaper path for one personally held rental with strong traditional employment income. DSCR becomes the practical lane when the borrower is self-employed, holds property in an entity or has several financed properties.
Investors can review Lendmire’s Massachusetts DSCR loan programs or call 828-256-2183 to talk through the file. Brokers work from lease copies and a conservative value assumption, then see whether coverage clears at 75% or needs a smaller ask. Verify current local rental rules, taxes and insurance with qualified local professionals. Program details change, so confirm current parameters before relying on any figure here.
Frequently Asked Questions
Why does Central Gloucester work better for cash-out than East Gloucester?
It comes down to how much rent stacks against the value. Rents in Central Gloucester sit at a much more workable level relative to its sale prices, while East Gloucester’s rents sit far lower relative to its much higher values. Two units in Central can land above 1.00 on a modeled basis at a moderate loan-to-value, but the same setup in East typically falls well below 1.00, subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Gloucester, MA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Can a single-family rental in Gloucester support a large cash-out?
Usually not at maximum leverage. Rents near $2,700 to $3,000 against values above $800K produce coverage far under 1.00, roughly 0.6x with taxes and insurance counted. A lender may review a sub-1.00 structure with lower leverage or more reserves, subject to guidelines. Multi-unit buildings are the better fit.
Should I underwrite to Redfin’s 29.9% jump or Zillow’s 1.9%?
Underwrite closer to the conservative end. Redfin’s figure comes from a month-to-month median with only 44 sales in May, and its price per square foot is down 23.8%. Zillow’s smoother index shows modest growth. An appraiser working from few comps may not support the headline number.
How long do I have to own a Gloucester property before a cash-out?
Programs typically look for about 6 months of ownership, measured from title recording. Some lenders treat recently purchased properties differently, so confirm the seasoning rule before assuming the appraised value will be used.
Does the local renter income base limit how much rent I can underwrite?
Yes, it can. Renter household incomes in Gloucester sit at a modest level according to the city’s draft housing assessment, so rents well above the local median invite turnover. Underwriting near market medians is safer than assuming a jump, even when rents have risen noticeably over the past year.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. DSCR eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized by Scotsman Guide in 2025 and named a 2026 Scotsman Guide Top Mortgage Workplace.
The real choice for a Central Gloucester owner is between two moves. One is to pull toward the 75% ceiling now and redeploy into another downtown two-family, accepting that a short appraisal or soft rent would squeeze coverage on both buildings. The other is to hold the leverage lower, keep the cushion above 1.2x, and accept that the equity stays parked while a thin-inventory harbor city keeps its small multi-unit stock hard to find.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Central Gloucester multi-family homes for sale
2. Beverly Hospital: Addison Gilbert Hospital
4. Redfin: Central Gloucester housing market
5. Redfin’s citywide multi-family page
6. Redfin: Gloucester rental market
7. Redfin — West Gloucester Housing Market
8. Redfin — East Gloucester Housing Market
9. Zillow: Gloucester home values
10. $844K median with a 29.9% annual jump
12. Zumper: Gloucester rent research
13. Applied Materials acquired it
14. Wikipedia — Gloucester, Massachusetts
15. recognized by Scotsman Guide in 2025
16. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Massachusetts
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.