
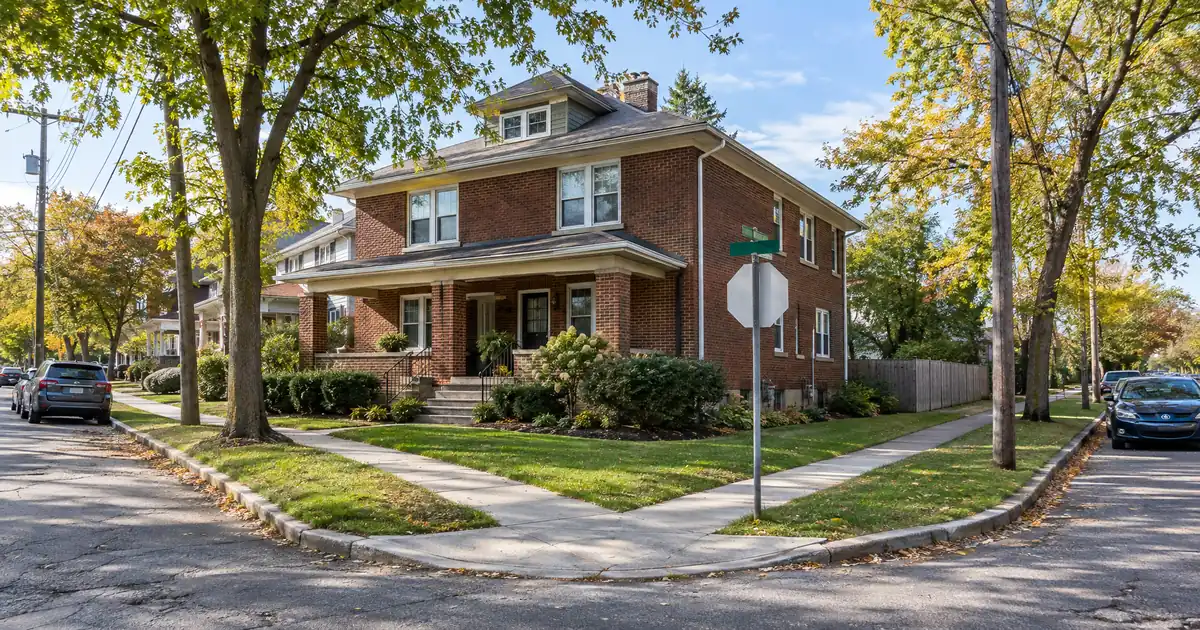
Picture an investor holding a single-family rental in Annehurst, bought several years ago at a price that now looks modest against today’s appraisals. The loan balance is small, the tenant is stable, and the equity sits idle. The question is how much of it can come out, and whether the property still covers its debt once it does.
The Quick Read: A cash-out refinance on a Westerville, Ohio rental is underwritten primarily on the property’s rent measured against its full monthly obligation, with the loan sized to a 75 percent ceiling after about six months of ownership from title recording, and proceeds set by appraisal, reserves and coverage rather than by personal income documents.
DSCR Cash-Out Calculator
Run the cash-out numbers in Westerville, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Modeled coverage at 75 percent LTV on a typical Westerville house, with full taxes and insurance included, typically lands well under 1.00, meaning the rent does not fully cover the monthly obligation at that leverage.
- Zillow reports that Westerville home values have edged up over the past year.
- Local property manager RL Property Management reports that single-family rents have held firm.
- Vertiv is adding jobs at its Westerville headquarters, per the Westerville Area Chamber of Commerce.
- Trimming leverage toward 50 percent improves modeled coverage, though the result depends on the specific property, its rent and the program.
Lendmire Research built this analysis around one question: where does a seasoned Westerville rental still clear debt coverage after equity comes out? The short answer is that the equity is real and the rent is thin against it. Everything below is about managing that tension. Program figures are typical guidance and subject to lender guidelines.
Westerville Market Snapshot
A quick read on the Westerville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $452K median list (Movoto) |
| Typical rents | $1,364 median gross (Luxe Home Team Uptown blog) |
| University enrollment | About 3,100 students (City of Westerville) |
| Population | 38,645 population (Census Reporter) |
| Employment | 210 local jobs (westervillechamber.com — Westerville Area Chamber) |
Westerville Is an Equity Market, Not a Cash-Flow Market
Westerville rewards holding, not buying. Prices have run ahead of rents, which is good news for an owner refinancing and harder news for anyone buying now.
Per Census Bureau QuickFacts, the city has 38,645 residents across 12.6 square miles, with a median age of 40.7. It is a northeast Columbus suburb straddling Franklin and Delaware counties. RL Property Management puts ownership at about 74 percent, and a Columbus Prime Realty analysis puts renters at 22.4 percent. That is a small rental pool. It is also a selective one, where condition matters more than it does in a renter-heavy market.
Zillow’s average home value is the canonical price figure here. Julie & Company’s local market report shows a higher median of $492,278, up 7.0 percent, but monthly agent medians use a thinner sample and swing hard. Movoto’s median list price sits at $452K, down 3 percent from a year earlier. Read together, the picture is flat to modest appreciation. Base cash-out projections on the index, not on a single hot month.
Rents tell the other half. Niche lists median rent at $1,364, while RL Property Management’s RentCafe-based figure for houses is about $2,233, with listings ranging from roughly $1,100 to $3,800. Houses command a large premium over apartments here. Investors are buying and holding the house product.
Gross yield estimates disagree. RL Property Management calculates 6.5 to 6.6 percent, and Columbus Prime Realty’s rental basics analysis lands at 4.6 to 5.35 percent before expenses. A lender’s underwriter will likely land near the lower band. Test coverage there.
What Does the Coverage Math Look Like at 75 Percent?
At the 75 percent LTV ceiling, a typical Westerville house models to roughly 0.8x, below the 1.00 baseline, once taxes and insurance are counted. Lowering leverage to about 50 percent lifts the number to around 1.05 to 1.10.
Run the numbers on a modeled house. These are assumptions for illustration, not market data: an appraised value equal to Zillow’s $411,803 average, rent equal to the roughly $2,233 average, and a 30-year fixed structure. Coverage is rent divided by full monthly obligation (principal, interest, taxes, insurance and any HOA dues), modeled with Ohio-average tax and insurance loads. Every band below includes taxes and insurance.
| LTV on refinance | Modeled coverage | Read |
|---|---|---|
| 75 percent | ~0.8x | Below 1.00 |
| 60 percent | ~0.95x | Borderline |
| 50 percent | ~1.05-1.10x | Clears baseline |
A 1.00x baseline is common because rent covers the payment at that level. Some lenders review lower or no-ratio scenarios, but those usually bring stronger compensating factors, lower leverage, different pricing or more cash retained. Exact eligibility depends on lender guidelines, credit profile, reserves and property review.
So a sub-1.00 file at full leverage has options a lender would review. A sub-1.00 program is one, interest-only structuring is another, and reducing the loan request is the third, and it is the one the table shows. The cost of that third path is less cash out. That trade-off, more cash versus more coverage, is the whole game in this market.
DSCR files in markets like this one typically look the same. The appraised value is strong, the rent is solid but not extraordinary, and the payoff balance is low enough that even a moderate loan request produces meaningful proceeds. The files that work usually pick a leverage level that clears coverage rather than chasing the ceiling. Investors who want to see the mechanics can read the guide “The Refi Options”.
The Seasoning Clock and Appraisal Room
Cash-out eligibility generally requires about six months of ownership measured from title recording, and the tight Westerville market tends to help the appraisal side once that clock runs.
Julie & Company’s June report shows just 1.0 month of housing supply and an average of 14 days on market. Its May report showed homes selling at just over 101 percent of original list price, though that report itself warns that percentage changes can look dramatic on small samples. Tight inventory means recent comps are available and generally supportive.
The same tightness makes buying below market hard. Equity here comes mostly from time held, not from a discounted purchase. That favors the investor who already owns and is now deciding how much to pull out.
The other appraisal risk is property type. Westerville is dominated by single-family homes, with townhomes and condos alongside. Duplexes and quadplexes turn up occasionally, mostly near Uptown. Multi-unit comps are sparse, so a two-to-four-unit cash-out can face thinner comparable support than a house. A duplex listed near Uptown around $415,000 shows the scale, and that figure is anecdotal, not a dataset.
Where Cash-Out Candidates Cluster
Three corridors matter most for seasoned rentals, each tied to a different tenant base. None has a reliable neighborhood-level price or rent dataset, so this section is qualitative and the city-level figures above carry the math.
Westar and the Polaris-adjacent corridor. This is the strongest demand story. The Westar Business District already houses Vertiv, DHL Supply Chain and The Marzetti Company. The Chamber reports Vertiv plans to hire over 700 additional employees in Ohio, including 210 at the Westerville global headquarters. The adjacent 88-acre East of Africa Road development is a $30+ million city investment. Housing stock here is newer, and about 61 percent of apartment communities citywide were built since 2000. Newer houses typically sit at the upper end of the local rent range, which helps coverage.
Uptown and the Otterbein area. Uptown is the city’s civic and educational core, with a historic district of 57 contributing structures. Otterbein University enrolls about 3,100 students, which adds a small but consistent rental demand layer among graduate students and faculty. Older homes near Uptown carry more maintenance exposure, which can hurt appraisal condition adjustments. Uptown is also where the scarce small multifamily sits.
Schrock Road, Cleveland Avenue and Huber Village. Older stock with quick interstate access to Columbus, Easton and Polaris. Vertiv facilities and Mount Carmel St. Ann’s sit along or near the Cleveland Avenue corridor. Mount Carmel Health System reports more than 10,000 employees system-wide, though that figure is not Westerville-only. This corridor is the likeliest place for a lower price point, but no source confirms it. Treat it as a hypothesis to test with comps.
Annehurst and Huber Ridge offer established lots and tree-lined streets, and Genoa on the Hoover Reservoir side draws outdoor-oriented renters. Maxtown and the Inniswood and Cooper Road area sit near Mount Carmel Medical Group, so healthcare workers are a plausible tenant pool. These are worth screening, not worth assuming.
Skip the Executive-Home Pockets
Highland Lakes and Medallion Estates are golf and executive-home areas where luxury homes run above $1.5 million. Rent will not carry those values. Coverage would sit far below 1.00 at any meaningful leverage. Stay out.
The median household income in Westerville is $109,404, per Point2Homes, while median renter household income is $59,760. That gap suggests tenants renting houses skew toward higher-earning households than the renter median implies, which supports the single-family rental product but does not lift rents on executive-priced stock.
Putting the Proceeds to Work
Cash-out proceeds equal roughly the appraised value times the LTV percentage, minus the existing payoff and closing costs, subject to reserves of about six months of obligation and a credit floor of 620. Standard programs reach loan amounts up to $3,000,000, and smaller balances route through select lenders in the network. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Those proceeds only matter if they fund the next deal. In Westerville, that next deal is probably not a second Westerville house at market price, where coverage is thin. Consider three routes.
DSCR vs. conventional financing
Two common ways to finance an investment property in Westerville, OH. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
- Cash-flow targets outside the city. Adjacent Columbus submarkets may support stronger multi-unit rent-to-value, though the research did not verify it.
- Value-add in Westerville. Older stock near Schrock Road or Uptown can improve rent through renovation, lifting coverage.
- Debt reduction. Retiring higher-cost debt elsewhere in a portfolio can improve overall coverage more than buying.
Entity-owned properties may qualify, subject to lender program eligibility. Investors reviewing options can see Lendmire’s refi programs or the DSCR loan options for Ohio investors. Anyone comparing structures against a traditional loan can read the guide “Where DSCR and Conventional Diverge”. Investors can reach the team at 828-256-2183. Verify current local rental rules, taxes and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Westerville, Ohio?
The property’s rent must cover its full monthly obligation at roughly 1.00x or better on most files, and the loan is capped at 75 percent LTV. Borrowers generally need about six months of title seasoning, a credit score at or above 620 and reserves near six months. In Westerville, coverage at full leverage often falls short, so many files reduce the loan request.
What are the requirements for an investment property loan in Westerville, Ohio?
Lenders review the property’s rental income, appraised value, borrower credit and reserves. Ineligible property types include manufactured homes, log homes and barndominiums. Loan amounts run up to $3,000,000 on standard programs, and all terms are subject to lender guidelines, credit approval and property review.
Does Westerville’s low renter share hurt a cash-out refinance?
Not directly. Lenders underwrite the individual property’s rent, not the city’s renter share. A small tenant pool does make condition matter more, and Westerville’s roughly 74 percent ownership limits comparable rentals. A well-maintained house with documented rent generally reads better than a stale lease on an older property.
How much equity can a Westerville investor realistically pull out?
It depends on appraisal, payoff, reserves and the 75 percent ceiling, and it is not a guaranteed figure. Modeled coverage on a typical house drops below 1.00 at the ceiling, so many investors choose lower leverage to keep the file clearing coverage. Zillow’s 1.7 percent annual change suggests modest recent appreciation.
The Real Choice
The Westerville owner faces a binary. One option is to pull equity near the 75 percent ceiling, taking maximum proceeds for the next deal while accepting sub-1.00 coverage and a program or structure that a lender must be willing to review. The other is to lower the loan request toward 50 percent, clearing the coverage baseline cleanly but leaving a meaningful share of a tight, appreciating market’s equity in a property that yields modestly. Neither is wrong. One buys capital, the other buys cushion.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets, meaning 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders and is not a direct lender. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and earned a 2025 Scotsman Guide Top Mortgage Workplace designation.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Westerville
2. RL Property Management, Westerville rental guide
3. Westerville Area Chamber of Commerce
4. Movoto
6. City of Westerville, Colleges and Universities
9. Julie & Company, Westerville market report
10. Niche, Westerville real estate
11. Columbus Prime Realty, Westerville rental basics
12. Mount Carmel Health System
13. Point2Homes, Westerville demographics
15. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Westerville Ohio · DSCR Cash Out Refinance Columbus Ohio · DSCR Cash Out Refinance Powell Ohio
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.