
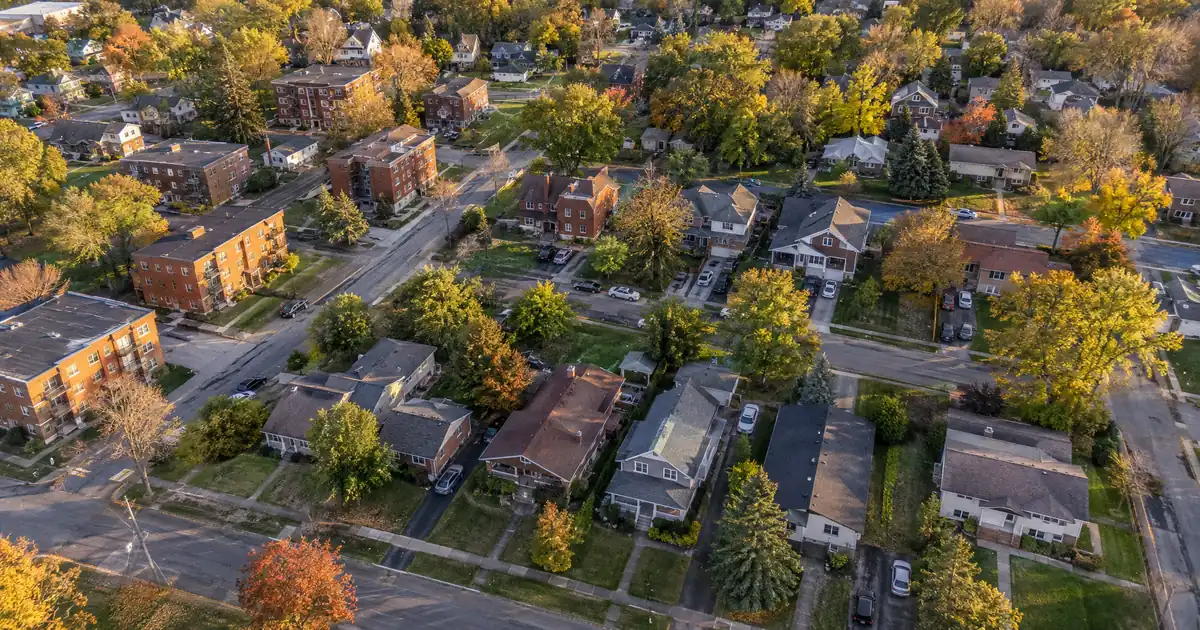
The appraisal is where cash-out plans shrink. An investor buys a rental, waits out seasoning, watches comps climb, then learns the lender will advance against 75 percent of value at most, and only if rent covers the full monthly obligation. That friction defines a DSCR cash out refinance in Grove City, Ohio, a Franklin County suburb where values and rents don’t line up the way a spreadsheet would like. Lendmire Research ran the numbers. Single doors struggle. Stacked doors work.
The Quick Read: A DSCR cash-out refinance in Grove City, Ohio is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the sequence is: confirm ownership seasoning, order the appraisal, test coverage at the 75 percent ceiling, then size proceeds to what the ratio and reserves allow, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Grove City, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family rent-to-price runs near 0.5 percent, per Zumper rents against Zillow values.
- Duplex stacking is the coverage lever. One door rarely clears 1.00 at the leverage cap.
- The North Meadows Drive and Stringtown Road hospital corridor anchors tenant demand.
- Seasoning runs about 6 months from title recording before cash-out is on the table.
- Sold comps and index values diverge, so appraisal outcome is the swing factor.
Grove City Market Snapshot
A quick read on the Grove City investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $398K median (Homes.com Grove City) |
| Recent appreciation | +8.8% (Redfin Grove City Housing Market) |
| Employment | 285 jobs (CityScene, OhioHealth and Mount) |
The Hospital Corridor Is Where the Tenant Base Sits
The strongest rental demand in Grove City sits along North Meadows Drive and Stringtown Road, where two hospital campuses were built in the same stretch. That is an unusually concentrated medical build-out for a suburb of roughly 45,000 people. Nurses, technicians, and residents rent 2-3 bedroom homes, and they rent them year-round.
Mount Carmel Grove City is a teaching hospital and the headquarters for the system’s graduate medical education program. Gresham Smith describes it as a 214-bed, 500,000-square-foot facility with a medical office building. Bed counts vary by source, so treat the figure as approximate. OhioHealth’s Grove City Methodist Hospital and surgery center sit on Stringtown Road, and a VA outpatient clinic moved to North Meadows Drive.
Headcount is where the sourcing gets thin. A CityScene piece written before the hospital opened projected Mount Carmel’s local staff rising from 110 to more than 1,600. It was a projection, not a payroll count. Mount Carmel’s system-wide figure, more than 8,200 colleagues across five hospitals, comes from its own press release and is not a Grove City number. Read the corridor as a durable anchor, not a measured one.
Older, secondary sources also name T. Marzetti, Walmart distribution, Tosoh America, and FedEx Ground among local employers. Use them as names, not headcounts. The City’s annual financial report carries a current principal-employers table on its finance page, and an investor building a lender narrative should pull the numbers from there.
The Coverage Problem, in Plain Numbers
Rent covers less of the debt in Grove City than in most Midwest rental markets. Zumper puts average rent at $1,549, up 10 percent year over year. Zillow’s average home value is $325,077, up 2.1 percent. Divide one by the other and you get roughly 0.5 percent per month. That is arithmetic from two sources, not a published statistic, and it sits well below the old 1 percent rule.
Rent sources disagree. RentCafe shows an average of $1,520, up 0.64 percent, and $1,557 for a 2-bedroom and $2,194 for a 3-bedroom. It covers only buildings with 50 or more units, so it skews toward newer complexes. Zumper’s listing data leans the other way. The honest read is that rents are somewhere between flat and rising fast, and a lender’s appraiser will want lease evidence, not averages.
Now the modeled math. These are assumptions, not market data: a $325,000 single-family value, a $1,549 rent, a 30-year amortization, and full taxes and insurance at Ohio averages. At the 75 percent cash-out ceiling, the coverage ratio lands around 0.7, including taxes and insurance. Drop leverage to 50 percent and it still sits just under 1.00. Not close enough.
Sub-1.00 files aren’t dead, but they need a different structure. A lender may review a sub-1.00 program, an interest-only period, or a lower loan-to-value with more equity left in the deal. Each carries different pricing, reserve, and leverage terms, and eligibility depends on lender guidelines, credit, and property review. The standard benchmark for most programs is 1.00, the point where rent covers the full monthly obligation. Below it, expect compensating factors to be part of the conversation.
Why Duplexes Do the Heavy Lifting
Two doors on one payment change the ratio. A Downtown Grove City duplex listing on Redfin shows two 2-bed, 1.5-bath units leased at $1,200 and $1,100, or $2,300 combined. That is one listing, not a market statistic, and the article does not average it. But it shows the structure. Two in-place rents can carry an obligation that a single rent near $1,549 cannot.
Model it. Assume a $300,000 appraised value (a modeled figure, not a listing price), the $2,300 combined rent, and the same amortization and full taxes and insurance. At 75 percent LTV, coverage lands around 1.1. Clear, but not roomy. A small change in appraised value or rent moves the number quickly enough to matter. (Higher rents on renewal are upside. Don’t underwrite them as income.)
Those in-place rents sit below the RentCafe and Zumper averages. That gap is either upside or a warning. Underwrite to lease-in-place and treat the difference as room to grow.
Inventory is the catch. Homes.com showed six multi-family homes for sale, priced from $230,000 to $725,000, with one older three-rental property carrying prior rents of $850 and $900 on two 2-bedroom units and a 3-bedroom needing a kitchen renovation. Six listings means shallow comps. It also means an appraiser has few nearby sales to lean on, which limits how much cash-out the value can support. This is a market where the duplex you own is more useful than the duplex you’re hoping to find.
Manufactured homes, log homes, and barndominiums fall outside these DSCR programs, so they are not part of the cash-out analysis.
What Will the Appraiser Actually Say?
Appraisal is the uncertain variable, because the published price signals disagree. Zillow’s average is about $325,000. Redfin’s most recent published median sale price is $385,000, up 8.8 percent year over year, at $203 per square foot. Homes.com shows a $398,000 median as of its latest update, with a separate $370,000 median up 4 percent, and does not explain the gap. Averages, medians, and sold prices measure different things.
Appraisers use sold comps. That means an appraised value on a cash-out could come in above index-based estimates such as Zillow’s, if the comparables are clean. The reverse can also happen. Redfin shows homes sitting 50 days on average, versus 38 the prior year, while Homes.com shows 32 days. When sources conflict on speed of sale, a local MLS comp pull tells you more than any of them.
Price tiers help frame the range. Realty Ohio lists entry-level homes at $220,000 to $300,000, updated single-family at $300,000 to $430,000, and new construction at $375,000 to $700,000 and up. It is a brokerage marketing page, so treat the ranges as directional.
The appreciation story is appreciation-led, not yield-led. New-build communities carry the higher price points, and in-place duplex rents are far below new-build economics. Older multi-unit or workforce single-family stock bought at a lower basis is where rent upside and price growth can support a refinance. New builds rely on appreciation and rarely on coverage.
Beulah Park, the Town Center, and the Affordable Pockets
Beulah Park is a former racetrack turned residential and retail district, and it’s the highest-rent area on Apartments.com‘s neighborhood ranking. Per Columbus Underground, Beulah Crossing adds two three-story buildings with 40 urban-style apartments over ground-floor retail. It’s local color more than a small-landlord play. Large-scale projects compete with, rather than resemble, the duplex on a side street.
The Historic Town Center, with walkable streets and older housing, is where small multifamily is most plausible. No sourced price or rent data exists for it, so no figures here. The affordable pockets are Indian Trails, Hennigans Grove and Keller Farms, which Zumper shows with some of the lower average rents in the area. Apartments.com lists Holt-Alkire among the more affordable neighborhoods as well. Lower rents there typically pair with lower values, which is the profile that gets rent-to-price closer to workable, but neighborhood-level values aren’t in the research, so an investor should pull them.
Pinnacle, a large newer subdivision, sits on the other end. Newer stock means higher basis and, on the numbers above, thinner coverage.
Seasoning, Leverage, and Where Proceeds Go
Most DSCR cash-out programs ask for about 6 months of ownership measured from title recording, and a 75 percent LTV ceiling, which is lower than the 80 percent purchase figure. Pricing and available terms vary by lender, borrower profile, property type, and full underwriting review. Standard programs go up to $3,000,000, and smaller balances route through select lenders. All of it is guidance, subject to lender guidelines, and the cash out is never a guaranteed figure. Equity available depends on rent used for lender review, PITIA, reserves, and the ceiling. Details are in the cash-out qualification details.
Here’s where the article’s central tension lands. Grove City’s growth is in values, not in rent-to-price, so the equity is often there before the coverage is. An investor who bought an older duplex and let it season may see appraised value climb enough to support a meaningful cash-out. An investor holding a single-family at average rent may see the coverage ratio, not the equity, as the constraint.
The deal desk pattern in markets like this one is consistent. The cleaner files from a documentation standpoint tend to be multi-unit properties with signed leases and rent rolls that match the appraiser’s rent schedule. The common friction point is a mismatch between the lease-in-place and the market rent the appraiser assigns, especially on older stock with below-market tenants. Files that arrive with lease copies and a clear plan for the proceeds generally give a lender less to question.
Borrowers holding title in an LLC should note that entity-titled loans are subject to lender program eligibility. For a plain-language look at how this differs from a bank refinance, see the guide “Where DSCR and Conventional Diverge”, and for more on the mechanics, Lendmire’s primer on DSCR loans covers the ratio in detail.
Watch the Supply
New units are clustering near the hospital campus and the Town Center. Per WOSU, the Columbus Metropolitan Housing Authority opened the 82-unit Cobblestone Manor, an income-restricted development, and the city already has 188 federally subsidized apartments. Reporting syndicated by AOL says CMHA plans more than 200 additional units near the hospital and more than 100 townhomes near I-270. Income-restricted units mostly serve a different renter pool.
The market-rate side is the one to watch. The 10TV report on the proposed Broadway Live mixed-use project cited 150 market-rate units. Its status may have changed, so treat it as proposed. Market-rate additions in those pockets could compete with small-landlord rentals. Underwrite rent growth and lease-up conservatively there, and remember that a cash-out on a refinanced rental is only as good as the rent an appraiser will support.
Population growth argues the other way. Wikipedia reports Grove City at 41,252 in the 2020 Census and an estimated 45,180 more recently, with median household income of $93,161. RentCafe counts 4,997 renter-occupied households against 12,486 owner-occupied, a 29 percent renter share. A renter pool that size is real but not deep, which is the argument for owning stock in the corridors where employment sits. For official demographics, see U.S. Census Bureau QuickFacts. Location matters too: the City of Grove City notes access from U.S. 62, I-71, I-270, and SR-665, which keeps Columbus-metro commuters in the tenant pool.
Investors should verify current local rental rules, taxes, and insurance with qualified local professionals before committing to a refinance plan.
Frequently Asked Questions
How much equity can a Grove City investor realistically pull out?
Not a fixed number. The 75 percent LTV ceiling sets the top, but coverage sets the actual limit. At average single-family rents the ratio falls short of 1.00 at that leverage, so proceeds shrink or the loan needs a different structure. Duplexes with signed leases give more room.
DSCR vs. conventional financing
Two common ways to finance an investment property in Grove City, OH. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Does the hospital corridor justify a rent premium?
It justifies steadier demand, not necessarily a higher rent. Mount Carmel and OhioHealth campuses support year-round 2-3 bedroom demand near North Meadows Drive and Stringtown Road, but the research has no sourced rent figure for those pockets. An appraiser will price the rent from comparables.
Why do Grove City price sources disagree so much?
They measure different things. Zillow reports an index average near $325,000, Redfin a median sale price of $385,000, and Homes.com a $398,000 median alongside a $370,000 one. Appraisals rest on sold comps, so the appraised value may land above an index estimate when the comparables are clean.
Is a duplex worth the thin inventory?
Often, yes, if you already own one. Only about six multi-family listings showed up, so new purchases are hard to find, but existing duplexes carry the strongest coverage math in the city. A modeled duplex at 75 percent LTV lands around 1.1. Comps are shallow, which limits the appraisal.
When can a recent purchase be refinanced for cash-out?
Typically after about 6 months of ownership measured from title recording, per current program guidelines. Recent renovation spending and lease documentation both affect what a lender will accept, so timing depends on the specific file and lender review.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
The Bottom Line on Grove City
Next to Columbus proper, Grove City is the better place to refinance and the harder place to buy for yield: the equity is here, the coverage is not. Right now the math favors owners of older duplexes near the hospital corridor over anyone chasing new-build appreciation in the suburbs.
For broader investor-financing rules and property-type coverage across the state, see Ohio DSCR loans.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s traditional personal-income documentation, is central to lender review, an approach that suits self-employed operators and portfolios beyond four financed properties. The firm is recognized by Scotsman Guide as a 2026 Top Workplace and is a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zumper
2. Zillow
3. Homes.com
4. Redfin Grove City Housing Market
5. CityScene
9. grovecityohio.gov — Finance page
10. RentCafe
11. Redfin
12. Realty Ohio
13. Apartments.com
15. WOSU
16. 10TV
17. Grove City
18. U.S. Census Bureau QuickFacts
20. recognized by Scotsman Guide as a 2026 Top Workplace
21. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Marion, Ohio: How the Cash-Out Math Clears in Marion · Cash Out Refinance Investment Property in Westerville, Ohio: Can My Rent Cover the New Loan? · DSCR Cash Out Refinance in Akron, Ohio: Will Akron Rents Cover a Cash-Out Loan on Older Duplexes?
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.