
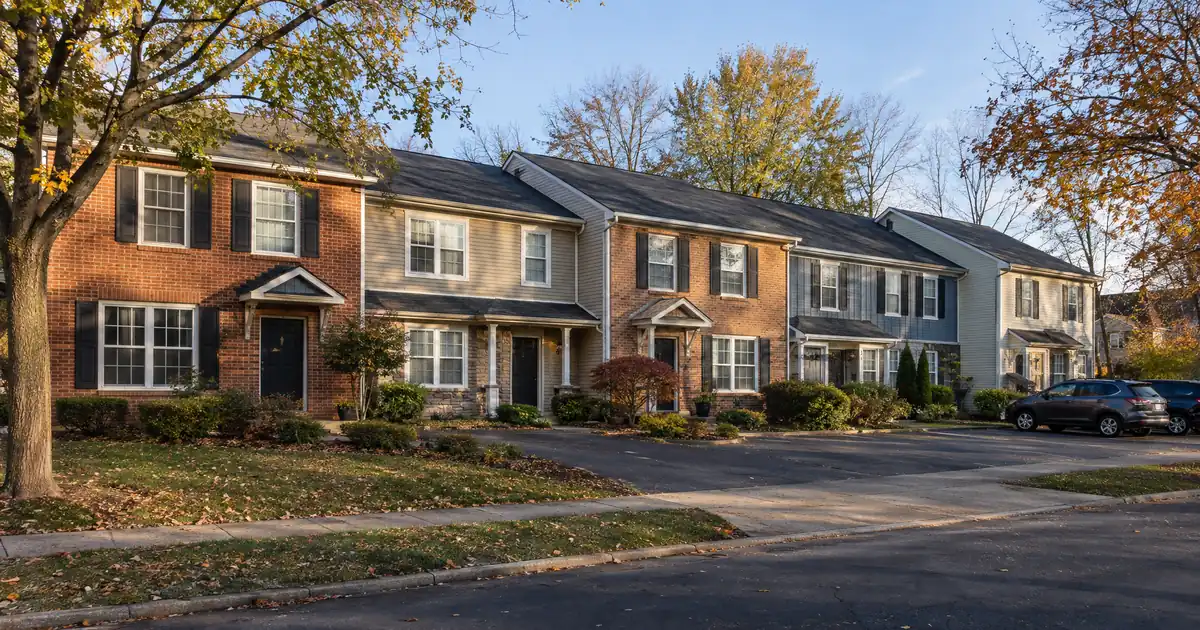
An out-of-state investor scrolling Hilliard listings sees a Columbus suburb with a median-priced home in the mid-$400,000s, a city that calls itself an Intelligent Community, and Amazon Web Services data centers on Hayden Run. The first two make it look like a safe appreciation play. The third looks like a demand story. What the screen usually hides is the supply pipeline and the thin rent-to-price math. Those two things decide whether a cash-out refinance here makes sense.
For Hilliard, Ohio rental property financing, Lendmire helps arrange DSCR loans through lenders operating in 41 markets, including Washington, D.C. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. This article is about the investor who already owns in Hilliard and wants to pull equity out, not the one still shopping for a first purchase.
DSCR Cash-Out Calculator
Run the cash-out numbers in Hilliard, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on a Hilliard, Ohio investment property is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds limited by a 75 percent loan-to-value ceiling and roughly six months of ownership seasoning from title recording.
- Hilliard is the most active new-apartment submarket in Columbus, which pressures nearby rents.
- Median-price single-family rents cover debt service thinly, often under 1.00x including taxes and insurance.
- Only about 31 percent of households rent, and small multifamily is scarce.
- Supply is forecast to ease, which may firm rents for later refinances.
Why the Coverage Math Is Tight Here
Hilliard single-family rentals at median prices typically land below 1.00x coverage once taxes and insurance are in. The equity is real, but rent has not kept pace with price. Cash-out works best on lower-basis properties, and leverage has to be planned around the rent, not the appraisal.
Pricing sources disagree, so here is the range. Resideline puts the six-month median closing price at $455,500, with the middle half of sales between $339,900 and $580,090. A local brokerage using MLS data puts the March city median at $410,000. Zillow’s smoothed index sits lower, at $350,707, up 3.3 percent over the past year. That gap comes from method: Zillow reports an index, the others report actual sales.
Rents are just as scattered. Zumper shows a $1,850 median across all property types, up 6 percent in the last year. Apartment List shows $1,826, down 1.7 percent. RentCafe shows an apartment average of $1,447, with three-bedrooms at $2,010, though that sample covers larger complexes only. Treat the three-bedroom figure as the realistic single-family anchor and nothing more.
Run the numbers on a home near that $410,000 median renting at $1,850 (a modeled assumption, not a property-specific rent). At 75 percent LTV, including taxes and insurance, coverage lands around 0.65x. Shift to a three-bedroom near the bottom of the middle-half price band renting at $2,010, and it climbs to roughly 0.85x. That is an improvement, but it still sits under the 1.00x level that select programs use as a floor.
Sub-1.00 files are not dead, but they get harder. A lender may review a sub-1.00 program, lower leverage, or an interest-only structure, with stronger credit and deeper reserves as compensating factors. Eligibility is subject to lender guidelines, credit approval, and property review. The guide “What Is a DSCR Loan” covers the ratio mechanics, and the guide “Where DSCR and Conventional Diverge” explains how this differs from conventional underwriting and why the rent-to-debt test matters more than personal income here.
The Supply Wave Is the Real Variable
Hilliard is Columbus’ most active apartment development submarket, and that determines how soft rents are when your refinance gets appraised. One Q2 market update puts Hilliard at 16.54 percent of the metro pipeline. Colliers credits the Trabue Road corridor with Hilliard’s 12.27 percent share of development, and an earlier Colliers read had 27.89 percent of the submarket’s units under construction, the highest concentration comparatively. Quarry Trails drives much of that.
New Class A lease-up competes for the same tenants as your single-family rental. Colliers notes that over 68 percent of recently delivered metro properties offer concessions. Underwrite coverage on in-place or market rents, never on new-build asking rents.
The forward look is better than the snapshot, though. Colliers expects starts to drop about 55 percent from the prior year. Realist Capital forecasts deliveries falling 30 percent the following year to about 5,200 units. The same report shows workforce housing (1 and 2 Star) as the only segment with real pricing power, at 8.8 percent vacancy with zero units under construction. Metro-wide effective rent growth is essentially flat at 0.1 percent. That is Columbus-wide, not Hilliard-specific, so read it as direction, not a local fact.
The timing question is genuinely a toss-up. A cash-out closed now is appraised and underwritten against soft rents. Waiting for supply to clear could mean a firmer rent roll, but also a different price environment. An owner sitting on strong equity who needs capital for the next acquisition probably shouldn’t wait on a forecast.
Submarkets: Where Cash-Out Pencils and Where It Doesn’t
No reliable neighborhood-level rent or price data exists for Hilliard, so this is a tenant-profile read, not a pricing table.
Old Hilliard is the best fit for older, smaller homes. The historic core around Main Street and the former rail corridor includes Norwich Street, where homes span different periods and styles, per the city history page. The Heritage Rail-Trail runs 7 miles and ends at Station Park, which gives the area a walkable, trail-adjacent tenant draw. Smaller, older homes mean lower basis, and lower basis is where coverage improves. Appraisals are the catch: comps in a historic district are uneven.
The Cemetery Road and I-270 corridor works for commuter-renter demand. The Hilliard Community Plan calls the area around the interchange, including Hilliard’s portion of Mill Run, the city’s economic engine, with infill and redevelopment opportunities. Apartments.com cites a COTA Park and Ride there and 15 to 25 minute drives to Downtown, Ohio State, and Dublin’s corporate campuses. That’s a listing-site claim, so treat it as color. Retail proximity and interstate access make it a defensible long-term hold.
Trabue Road and Quarry Trails is the cautionary note. Great for tenants shopping new product, rough for anyone holding older stock next door. If the property sits within the lease-up shadow of new apartments, expect concession pressure and cap your underwritten rent accordingly.
Skip Heritage Preserve for DSCR. Its 405 homes were originally priced from $300,000 to over $700,000, per a resident site, and it’s owner-occupier territory. The rent-to-value ratio won’t carry a cash-out. The Big Darby edge is also out: the watershed plan limits density, so there’s no multi-unit play there.
Property Type: Single-Family Dominates, Small Multifamily Is Rare
The housing mix tells you where coverage can come from. NeighborhoodScout shows single-family detached at 64.86 percent of housing units and duplexes, converted homes, and small apartment buildings at just 5.77 percent. RentCafe puts renter-occupied households at 31 percent, or 4,224 households, against 9,618 owner-occupied.
Two-to-four unit properties would help coverage by stacking rent against a single mortgage. The problem is that comps are thin, so appraisals are harder, and no sourced Hilliard 2-4 unit rent or price data was found. An owner who already holds one should treat it as the strongest cash-out candidate in the city. An investor who doesn’t shouldn’t assume one is easy to find.
Experience matters here. Working DSCR brokers see a recurring pattern in suburban markets with heavy new apartment supply: the appraisal comes in strong on the owner’s equity, but the rent schedule gets haircut in the coverage calculation, so the loan size that works is smaller than the equity suggests. Files that anticipate this, with lower leverage chosen up front and reserves documented early, tend to move through lender review with fewer surprises.
What Cash-Out Looks Like on a Hilliard Hold
The 75 percent cap and the six-month clock. Cash-out refinances on investment property top out at 75 percent LTV. That is a hard ceiling, not the 80 percent seen on purchases. Seasoning generally runs about six months of ownership measured from title recording. Credit tiers typically start at a 620 floor, with better positioning at 660, 680, and 700. Reserves generally run about six months of PITIA, stepping to about nine months on balances above $1,500,000. Standard programs go up to $3,000,000, with smaller balances routed through select lenders in the network. Proceeds depend on rent used for lender review, the full obligation, reserves, and that 75 percent ceiling, so don’t plan around a number until the file is reviewed. Properties held in an LLC are reviewed subject to lender program eligibility. Manufactured homes, log homes, and barndominiums fall outside these programs.
Appreciation versus coverage. Prices have been climbing. The city median rose 5.2 percent over the last full year, per the local brokerage report, with a 99.6 percent sale-to-list ratio and 32 days on market in March. Redfin’s earlier snapshot showed a $421,000 median, down 5.8 percent year over year, with about 41 days on market, so the picture isn’t one-directional. The tension is that equity builds faster than rent, which means the loan size supported by rent can lag the loan size supported by value. Price position matters: product toward the lower end of that $339,900 to $580,090 band carries the more favorable rent-to-price ratio. Treat that as a hypothesis to test against comps, not as sourced rent data.
What the proceeds do. The usual use is the next acquisition, ideally a lower-basis or multi-unit property where coverage clears 1.00x. Refinancing a thin-coverage Hilliard SFR to fund a stronger-cash-flow hold elsewhere is a common structure. Compare the refi options, including rate-and-term and cash-out refinancing, before choosing a route, and review DSCR loan options for Ohio investors for the state-level picture. Local rental rules, taxes, and insurance vary, so verify them with qualified local professionals.
What’s Actually Driving Demand?
Hilliard’s job base is broad but not a mass tenant source. The City of Hilliard Economic Development page counts 1,200 companies and names Amazon Web Services, Advanced Drainage Systems, and Foresee Power. The city’s Q4 financial overview lists top employers by income-tax withholding, including Honda of America, Cardinal Health, a large national bank, Nationwide Mutual Insurance, OhioHealth Physician Group, Nationwide Children’s Hospital, and The Ohio State University. No headcounts, no ranking.
Data Commons puts population at 38,832 with a median age of 35.8. Advanced Drainage Systems’ new headquarters occupies 98,350 square feet at the TruePointe development, per Colliers’ office research. That’s office space, not employee count.
The AWS cluster deserves honest framing. DatacenterDynamics reports five buildings at the Hayden Run site, and Amazon describes a statewide $10 billion plan with up to eight new sites. But Axios Columbus reported that the Franklin and Licking county data centers employ nearly 1,000 workers combined. That’s a skilled-trades and tax-base story, not a tenant wave. Count it as stability, not volume.
The city also holds an Intelligent Community designation, documented by the Intelligent Community Forum, and sits inside the $200 million Route 33 Smart Mobility Corridor. Nice to have. It doesn’t change a rent roll.
Frequently Asked Questions
How much equity can a Hilliard investor pull out?
It depends on rent used for lender review, the full monthly obligation, reserves, and the 75 percent LTV ceiling, so no figure is guaranteed. In Hilliard, the rent often limits the loan size before the value does. A lower-basis property or one with a stronger rent schedule will support more proceeds than a median-priced single-family home.
Does a Hilliard single-family rental clear 1.00x on a cash-out?
Usually not at median pricing. Modeled with taxes and insurance, a home near the city median at 75 percent LTV runs well under 1.00x. Lower leverage, a lower-basis property, or a sub-1.00 program may be reviewed, subject to lender guidelines and credit approval.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Hilliard, OH, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Will the new apartments near Trabue Road hurt my appraisal or rents?
They pressure rents more than appraisals. Heavy lease-up and concessions on new Class A product compete with nearby rentals, so underwrite at in-place or market rents. The appraisal draws on sales comps, which have been steadier.
How long do I need to own before a cash-out refinance?
Programs generally look for about six months of ownership, measured from title recording. Properties bought with renovation capital often need the value-add documented before the appraisal reflects it. Confirm seasoning rules with the program reviewing the file.
Is a duplex or fourplex easier to refinance in Hilliard?
It can help coverage, but small multifamily is only 5.77 percent of housing units, so comps are thin. An owner who already holds one has a valuable asset. An investor hunting for one will find the supply limited.
Watchlist: Three Indicators for the Next Quarter
- Concessions near Trabue Road and Quarry Trails. If lease-up offers ease, the rent pressure on nearby single-family rentals is easing with them.
- Hilliard’s share of the Columbus apartment pipeline. A falling share of units under construction would confirm the forecast supply relief.
- Median sale price against median rent. If rent growth starts closing the gap with price, Hilliard’s thin rent-to-price ratio gets less thin, and cash-out proceeds get larger.
About Lendmire
A DSCR-focused mortgage broker, Lendmire (NMLS# 2371349) places investor financing across 41 markets, 40 states plus Washington, D.C., with DSCR eligibility generally reviewed by the lender on property cash flow instead of traditional personal-income documentation, subject to lender guidelines. Scotsman Guide named Lendmire a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Mortgage Workplace. Investors can reach the team at 828-256-2183 or compare DSCR options.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Resideline Hilliard Housing Market
2. $410,000
4. Zumper
6. RentCafe Hilliard Rent Trends
8. Colliers Columbus Multifamily Trends
9. Colliers — Columbus 2025 Multifamily Trends Columbus
10. Realist Capital Columbus Multifamily Analysis
11. Cityofhilliard.com — History
13. Hilliard Community Plan Focus Areas
15. City of Hilliard Economic Development
17. Data Commons
20. Amazon AWS Ohio Investment
21. Axios Columbus
22. Intelligent Community Forum
23. a 2025 Scotsman Guide Top Mortgage Workplace
24. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Hilliard, Ohio: The 2026 DSCR Financing Guide to Old Hilliard · DSCR Cash Out Refinance in Columbus, Ohio: Franklinton Duplex Equity Strategy · Cash Out Refinance Investment Property in Gahanna, Ohio: Pulling Equity in a Flat Creekside Market
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.