
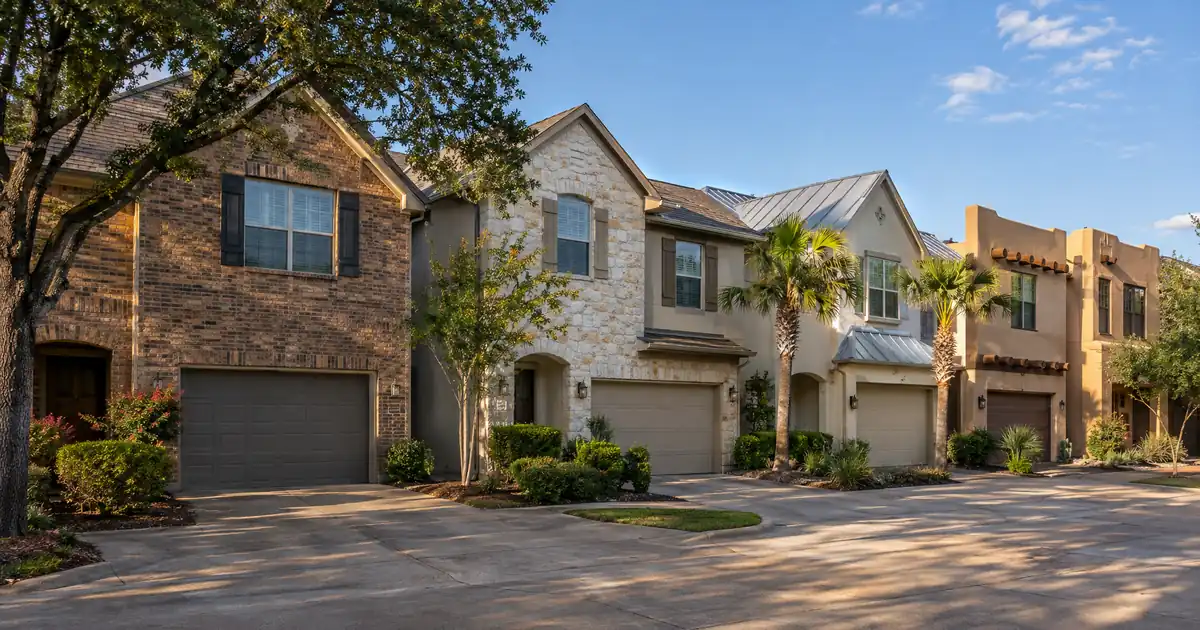
Data USA puts Mesquite’s median property value at $245,700, up 8.48 percent in a single year. Zillow’s home value index shows the opposite direction: an average of $263,551, down 4.1 percent, with homes going pending in about 45 days. Both readings are defensible, and they measure different things. For an investor sitting on a paid-down Mesquite rental, the gap between them is the whole cash-out story. Equity exists, but the appraisal that turns it into usable capital is not a given.
DSCR Cash-Out Calculator
Run the cash-out numbers in Mesquite, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on a Mesquite, Texas rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the new loan limited by a program LTV ceiling once the seasoning period has passed, and reserves held behind it, all subject to lender guidelines.
- Median value is $245,700 per Data USA, but Zillow’s index reads softer, so appraisals deserve stress-testing.
- Rents barely differ across ZIP codes 75149, 75150, and 75181. Entry basis drives coverage.
- Cash-out sizing runs on a 75 percent LTV ceiling, about six months of seasoning, and 1.00 minimum coverage.
- Small-balance stock often sits below national loan minimums, so lender routing matters.
- Apartment concessions across the metro cap how hard investors can push rents.
Mesquite Market Snapshot
A quick read on the Mesquite investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,800 and $2,000 unit rents (Homes.com) |
| University enrollment | ~38,000 students (Texas State Historical) |
| Employment | 2,250 jobs (Mesquite Economic Development) |
| Vacancy | 12.2% (Matthews DFW Multifamily Q1) |
Mesquite Park: Start With the Duplexes
Mesquite Park is the best place in the city to think about equity extraction, because it holds the product type that stacks income on one loan. Homes.com shows a 12-month median sale price of $214,950 there, up 3 percent, with listings averaging 46 days on market. The duplex stock includes single-level buildings with three bedrooms and two baths per side plus a two-car garage. That layout matches what local renters actually want: Point2Homes says three-bedroom units are the largest slice of Mesquite rentals at 32 percent.
Here is the income-stacking example. A renovated duplex listed on Homes.com has one side leased at $1,800 and the other positioned to rent for $2,000. That is $3,800 combined from a single building and a single loan. A single-family house asks one tenant to carry the entire debt. A duplex splits that load across two households, so one vacancy dents coverage instead of zeroing it.
Census-derived figures from City-Data.com back up the price advantage. Mean values run $179,589 for three-to-four-unit structures and $302,341 for five-plus units, against a median gross rent of $1,604. The $108,327 figure for two-unit structures looks distorted by older and owner-occupied stock. Use it as proof that small multifamily is cheaper per building than a house, not as a deal benchmark.
Honestly, whether Mesquite Park duplexes beat a well-bought 3/2 house is close to a toss-up. The duplex wins on income diversification. The house wins on liquidity if you ever sell. An owner planning to hold and recycle equity into the next purchase usually favors the duplex.
What a Cash-Out Actually Sizes To
Cash-out proceeds are set by three things: appraised value, the coverage the rent produces, and the reserves left afterward. Mesquite, Texas investors can have DSCR scenarios reviewed through lender programs that Lendmire (NMLS# 2371349) helps place across 41 markets, including Washington, D.C. Lendmire is a DSCR-focused mortgage broker. It arranges these loans through wholesale channels, and lenders make the approval decisions.
The parameters on a cash-out are tighter than on a purchase. Typical guidelines, subject to lender overlays, look like this:
| Factor | Cash-Out Refinance | Notes |
|---|---|---|
| Max LTV | 75 percent | Hard ceiling, lower than purchase |
| Seasoning | About 6 months | Measured from title recording |
| Minimum coverage | 1.00 | Rent vs. full PITIA |
| Credit floor | 620 | Better tiers improve options |
| Reserves | About 6 months PITIA | Higher above $1,500,000 |
Coverage is monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. LLC-titled properties are common on these files, subject to lender program eligibility. The new loan first pays off the existing lien, so usable proceeds are what remains of 75 percent of value after that payoff. That is why pulling equity with a DSCR cash-out works best on a property with a low balance, and why the investor refinance breakdown is worth reading before you order an appraisal.
Modeled Coverage on a Typical House
Run the numbers on a modeled 3/2 house. These are assumptions, not sourced market data. Take a $2,035 monthly rent, which sits in the middle of the range of live 3/2 listings across Mesquite’s three ZIP codes per a Movoto listing snapshot (directional only, no sale prices). Model a 75 percent cash-out at a value near the Data USA median of $245,700, including taxes and insurance at Texas averages. Coverage lands in the low-1.2 range.
Now change one input. At Zillow’s higher $263,551 valuation, the same rent covers a bigger loan and the ratio slips to roughly 1.1x. Drop the rent to the low end of that listing spread, $1,740, and coverage sits just under 1.00 on full PITIA. That last case is where the file gets harder. Some lenders may review sub-1.00 scenarios through a sub-1.00 program or an interest-only structure, but those paths typically mean reduced leverage, stronger credit, and more cash left in the deal. Approval remains subject to lender guidelines, credit review, and the property itself. A borrower who wants a real cushion can also just ask for less than the maximum.
The same modeled house makes the duplex case clearer. Stack $3,800 of rent against a building valued near the Mesquite Park median and coverage clears 2.0x on full PITIA. The fixed costs of a duplex are spread over twice the income.
DSCR files in markets like this one typically look like a paid-down or lightly leveraged workforce rental, a rent schedule built from a handful of comparable listings, and an appraisal that is the real swing factor. The stronger files usually pair a conservative rent figure with a stated plan for the proceeds, such as a down payment on the next property. Files get stuck when the borrower assumed a value that the appraiser’s comps did not support. For a primer on the mechanics, see the guide “What Is a DSCR Loan”.
Two Value Readings, One City?
Mesquite’s value signals conflict, and a cash-out borrower should plan around the lower one. Census-based data shows values climbing. Zillow’s index is soft. Neither is wrong, since one is a lagging median and the other a current index, but an appraiser will price the property off recent closed sales, not either headline number.
Rents are more encouraging. Zumper reports a citywide median of $1,779, up 5.7 percent year over year, with houses at $2,195, three-bedrooms at $2,035, and apartments at $1,214. The gap between house and apartment rents is the tailwind for investors: single-family and duplex product rents at a premium to the apartment stock next door.
Here’s the tension. Rents are rising while values are flat to down, which helps the coverage ratio but not the LTV math. Plan the refinance around today’s appraised value, not the appreciation you expected when you bought. If the appraisal disappoints, coverage may still clear 1.00 but the cash-out shrinks. Owners with a low original basis and several years of hold are the ones who still get meaningful proceeds.
The Corridors Around the Core
I-30 and Eastfield. This corridor pulls three renter groups: students, healthcare workers, and hourly employees. Dallas College’s Eastfield Campus sits on 244 acres at I-30 and Motley Drive. Niche counts 3,157 full-time and 13,348 part-time undergraduates. Enrollment sources conflict, so think roughly 14,000 to 16,000, mostly part-time. Part-time students don’t sign the same leases as residential-college undergraduates, so treat this as steady workforce demand, not a dorm-overflow play. Baylor Scott & White runs a Family Health Center at 1575 Interstate 30, and Dallas Regional Medical Center is also based in the city.
Downtown Mesquite. The historic core is revitalizing, with murals and a new Front Street Station, and the rodeo grounds nearby give it identity. Price data is thin, so it is a corridor to watch, not one to underwrite yet. (The rodeo, for the record, is a civic identity and not a rental driver.)
Gus Thomasson and the Town East corridor. This is the retail hub. Mesquite Economic Development says Town East Mall supports 2,250 jobs. That helps, but retail wages cap what tenants can pay.
Southeast and the I-20 industrial belt. Logistics jobs are growing around Mesquite Metro Airport and Trinity Pointe. Economic development lists industrial space from 75,000 to 3,000,000 square feet near the airport and north of I-20. Housing and rent data for this pocket wasn’t found, so treat it as employment context.
Meadowdale and Ironhorse. Older, established areas with apartments and duplexes. Rent data is anecdotal, so the analysis stops there.
Skip the Fresh-Build Basis
Newer pockets like Valleybrooke offer four-bedroom, two-bath builds. Movoto’s citywide median list price of $359K at $171 per square foot is likely skewed by new construction. New builds carry a higher entry basis, and rents don’t rise to match it. Coverage compresses and the cash-out cushion thins, so this is where the cash-flow math is weakest. Buy new for low maintenance, not for DSCR strength. Cash-out is a different question. A new build with little equity has nothing to extract.
Who Actually Rents Here
The tenant base is hourly logistics and manufacturing workers, and the City of Mesquite names the anchors: Ashley Furniture, PepsiCo, FedEx Ground, Walmart, UPS, Canadian Solar, Mesquite ISD, and Town East Mall. The Economic Development office calls UPS’s customer center the longtime largest private-sector employer, PepsiCo runs the largest bottling plant in North America, and Canadian Solar operates its first U.S. manufacturing facility. A Texas House resolution (HR 972) describes an Ashley expansion to a 1,577,000-square-foot facility with more than 300 additional jobs. Mesquite ISD, per the Texas State Historical Association, enrolls around 38,000 students across 51 campuses.
The demographics fit a rental thesis. The economic development office reports 3 percent unemployment, 3,995 businesses, and average household income of $90,080. RentCafe shows 37 percent of households renting, about 18,793 of them. Data USA puts the average commute at 32.1 minutes, so most workers travel out, which keeps Mesquite a bedroom-and-warehouse market and not a job center of its own. It is a stable demand base but not a high-income one. Workforce wages limit how much rent a tenant can absorb, which is why coverage in this city comes from low basis, not from rent growth.
The Small-Balance Wrinkle
Mesquite’s affordability has a financing side effect. Sub-$200,000 investment stock often falls below the loan floors of many national programs, and that is a real issue for small-balance cash-outs. Standard programs go up to $3,000,000, but smaller balances typically route through select lenders in the network. It is worth confirming minimums before you order an appraisal. Investors comparing paths can weigh how conventional loans differ from DSCR loans on investor purchases and refinances. Details on the state program are on the page for DSCR loan options for Texas investors.
If you’re weighing a scenario, request a review at request a scenario review or call 828-256-2183. Review details are subject to lender overlays.
The Blind Spot: Apartment Supply Sets the Rent Ceiling
The biggest risk for DSCR-financed Mesquite investors is not the property. It is the apartment market around it. Matthews reports DFW multifamily vacancy at 12.2 percent, with net absorption of 5.1K units trailing deliveries of 7.3K. The worst pressure sits in northern suburbs like Frisco/Prosper and Allen/McKinney, not the inner-ring east side where Mesquite sits. Still, the Dallas Fed notes concessions of six to eight weeks of free rent, up to 10 to 12 weeks in some Texas submarkets. Those are metro-level figures, and neither source breaks out Mesquite.
DSCR vs. conventional financing
Two common ways to finance an investment property in Mesquite, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The practical impact is indirect. Small rentals compete with concession-heavy apartments, and an appraiser’s rent schedule may come in below listing rents. Underwrite conservative rents, not the top of the asking range. Mesquite’s soft values and rising asking rents can pull apart if metro supply keeps outrunning demand, so verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Mesquite, Texas?
The property’s rent has to cover its full monthly obligation, with 1.00 as the typical minimum, and the new loan is generally capped at 75 percent of appraised value. Most files also need about six months of ownership, a credit score of at least 620, and roughly six months of PITIA in reserves. Outcomes depend on lender guidelines and property review.
What are the requirements for an investment property loan in Mesquite, Texas, on a small balance?
Coverage, credit, and reserves work the same as elsewhere, but loan minimums are the sticking point. Lower-priced Mesquite properties can fall below the floors of many national programs, so smaller balances route through select lenders. Ask about minimums before ordering an appraisal.
Does Mesquite’s soft home-value trend hurt a cash-out appraisal?
It can, because a softer trend may pull an appraiser’s comps below what an owner expects. Sources also disagree on direction, with one index showing values down and another showing an increase, which adds uncertainty to any single estimate. Plan the refinance around current appraised value, and consider requesting less than the maximum cash-out to keep a coverage cushion. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Is a duplex or a 3/2 house better for a Mesquite cash-out?
Duplexes spread the debt across two rent streams, which keeps coverage steadier if one side goes vacant. Three-bedroom houses are the most common rental layout and are easier to sell. Investors recycling equity into the next deal tend to favor duplexes.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. The firm is recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Zillow Home Values: Mesquite
3. Homes.com
4. Texas State Historical Association: Mesquite
5. Mesquite Economic Development
6. Matthews: DFW Multifamily Report
7. Homes.com: Mesquite Park multifamily
8. Point2Homes
10. Zumper: Mesquite rent research
11. Niche
13. City of Mesquite: About Mesquite
14. Mesquite Economic Development: Top Employers
15. HR 972
16. RentCafe
17. Dallas Fed: Southwest Economy
18. a 2026 Scotsman Guide Top Mortgage Workplace
19. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Mesquite, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.