
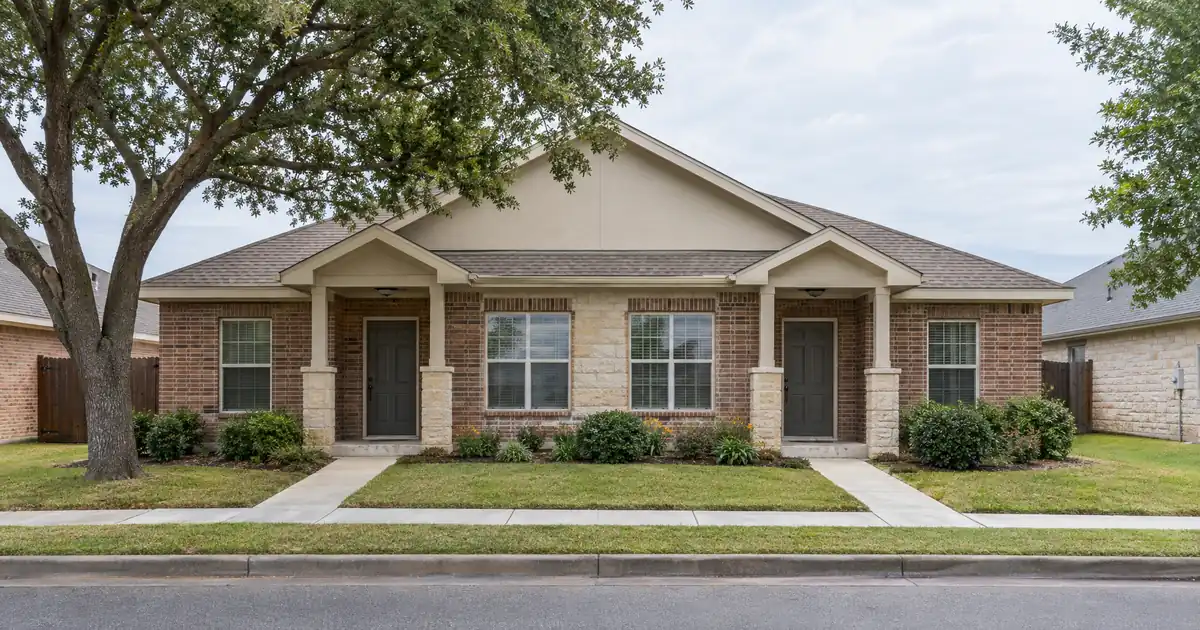
An out-of-state investor scrolling Killeen listings sees the price first. Zillow’s value index sits near $220,742, and the Apartment List median rent is $1,073. Cheap houses beside one of the biggest Army posts in the country looks like an easy yield story. What that investor usually misses is that a low price and a low rent travel together, and a DSCR cash out refinance in Killeen, Texas lives or dies on how many doors sit under one loan, not on how cheap the house looks. Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, arranges these refinances for investors who already own here and want to pull equity out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Killeen, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance in Killeen, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation, including taxes and insurance. The file also has to fit within the lender’s leverage cap, seasoning window, and reserve requirements, which vary by program and by borrower.
- Killeen’s median rent runs $1,073 to $1,200 depending on the portal, so houses carry thin coverage.
- Duplexes and fourplexes stack several rents on one loan, which is where coverage improves.
- Cash-out is capped at 75 percent LTV, with about six months of seasoning typical.
- Price signals conflict, so underwrite on current comps rather than assumed appreciation.
Killeen Market Snapshot
A quick read on the Killeen investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $525–$595 unit rents (Soldiers of Real Estate listings) |
| Recent appreciation | +6.5% yoy (Homevets Realty) |
| University enrollment | +13.7% enrollment activity (Central Texas College) |
| Employment | 159,692 jobs (Killeen Daily Herald) |
North Killeen and Downtown: Cheap Basis, Thin Doors
North Killeen is the lowest-cost, lowest-rent corner of the city, and it is where small multi-unit buildings cluster. Apartment List describes Rancier Street as the primary boundary of north Killeen, with many north-side rentals sitting on it. Rent.com puts a one-bedroom here near $500, and near $575 downtown, where Central Texas College draws tenants.
Those rents tell you what the cash-out math is up against. Per-door income is small, so a refinance only works when the building has enough doors and the basis is low enough that combined rent covers the full monthly obligation. One six-unit listing in the area shows unit rents of $525, $575, and $590 with an asking price near $475,000, and two of its six units were vacant. Listing claims, not sold comps. Treat them as an illustration of low per-door rents, nothing more.
Run the numbers on that kind of building as a modeled assumption: six doors at roughly $575 each, a $475,000 value, and a refinance at 75 percent LTV. Including taxes and insurance, coverage lands around 1.05, which is thin. A modest rent dip or a vacant unit at appraisal pushes it below 1.00. Some lenders will review a sub-1.00 file, but typically with reduced leverage, stronger credit, and more reserves, and approval depends on lender guidelines and property review. If an investor is reaching for sub-1.00 because the building’s rents don’t support a standard lender review, that points to the price paid, not to the loan type.
Honestly, this is the genuine tension in north-side stock: the cheap basis is the appeal, and it is also the reason a single vacancy matters so much.
West Killeen and the Clear Creek Corridor
West Killeen along Clear Creek carries newer duplexes and higher rents, and it also carries the market’s clearest oversupply signal. Apartment List notes that duplexes around Clear Creek are newer, with more amenities than much of the area’s single-family and apartment stock. AdventHealth Central Texas, with more than 300 physicians across 43 specialties, sits on South Clear Creek Road and anchors employment nearby.
Here’s the catch. The City of Killeen reports a net 1,307 dwelling units added since the start of 2024, including 539 multifamily units, and KDH News reports an 182-unit, 19-building apartment project slated for west Killeen. New product competes directly with newer duplexes. Investors refinancing there should expect concession pressure and should underwrite rent from a fresh survey, not from what the unit fetched a year ago.
The tradeoff runs both ways. West-side rents sit well above north-side rents, so coverage can look healthier on paper, but the basis is higher and the newest supply is aimed at exactly these tenants. North Killeen competes on price. West Killeen competes on amenities against a growing pipeline. Neither is a free pass.
Does the Coverage Number Clear on a House?
On a single-family house, coverage in Killeen typically lands near 1.00 and often slightly under it. Rentometer shows three-bedroom rents near $1,494 and four-plus-bedroom rents near $1,812 across property types. Set a $229,000 median sale price, the Texas REALTORS figure relayed by Homevets Realty, against those rents, and the rent-to-price ratio is thin. Modeled at 75 percent LTV including taxes and insurance, a three-bedroom at about $1,494 covers at roughly 0.95 to 1.00. A four-bedroom at the higher rent reaches the low 1.1s.
| Factor | Single-family house | Duplex or fourplex |
|---|---|---|
| Rent per loan | One rent | Several rents stacked |
| Modeled coverage | Near 1.00 or below | Depends on price paid |
| Vacancy impact | All or nothing | Partial |
| Cash-out leverage | Up to 75 percent | Often tighter, varies |
That is why the housing stock matters. A local Realtor’s investor page says the Fort Hood-area multifamily inventory is mostly duplexes and fourplexes, with few triplexes. That is one agent’s view, so hold it loosely. Combined rent against one loan is what can lift coverage, though no neutral dataset exists for duplex or fourplex sold prices here, so the rent-to-price ratio has to be verified building by building. Seasoning, maximum LTV, and minimum coverage also vary by lender and unit count, and two-to-four-unit properties often carry tighter leverage than one-unit properties.
Rents by unit size also matter. The agent’s view that three-bedroom units rent best matches Rentometer’s bedroom-count spread, and a two-three mix of unit sizes is the fourplex configuration he describes.
Appreciation Is Mixed, So Underwrite Flat
Killeen’s price signals conflict, and a cash-out plan that depends on growth is a plan built on the wrong number. Zillow’s index is down 1.0 percent over the past year, while the Texas REALTORS median sale price reached $229,000, up 6.5 percent. Those measure different things. Zillow models values across all home types, while the median reflects whichever homes happened to sell. Redfin’s own housing page showed a decline of 9.53 percent at one point, and a broker blog quoting Redfin reports 69 days on market versus 63 a year earlier.
Read together: flat to modest, not a trend. Appraisers in a balanced market are unlikely to hand out aggressive value bumps, and Homevets’ data shows about 82 percent of sales under $300,000, so comps are plentiful in that band. That helps appraisal reliability. It doesn’t help a growth thesis.
For an investor who bought a few years back, the practical read is simple. The new loan is capped at 75 percent of appraised value, the existing balance gets paid first, and whatever remains is proceeds, if any. Rate-and-term is the better answer when the equity gap is small. A file typically needs about six months of ownership measured from title recording, credit generally at or above a 620 floor with better tiers at 660, 680, and 700, and reserves around six months of PITIA. Loan amounts go up to $3,000,000 on standard programs, and the smaller balances common in Killeen route through select lenders in the network. All of it is subject to lender guidelines and property review.
Working DSCR brokers see a recurring pattern in low-basis, military-adjacent markets: the appraisal comes in near the purchase-era value, the coverage number lands within a tenth of 1.00 on either side, and the deciding factor is whether the rent schedule is documented with leases rather than asking rents. Files that carry a current lease for every occupied door, and a market-rent survey for any vacant one, tend to move through lender review with fewer questions.
Fort Hood Is the Engine (and the Concentration Risk)
Fort Hood, also called Fort Cavazos in sources, is the demand base, and it is also a single point of concentration. The Texas Comptroller study as reported by the Killeen Daily Herald puts the installation’s economic output near $37.87 billion, with 4,453 appropriated civilian employees and 11,087 full-time contract staff. The Fort Hood Sentinel quotes the installation’s spokesperson calling military pay reliable and consistent. Steady income is good for rent collection.
The supply of tenants replenishes itself too. Grand Central Texas reports about 462 people transitioning out of the military each quarter, with over 40 percent saying they prefer to stay in Central Texas. Central Texas College reported enrollment activity up 13.7 percent at its most recent spring check, and Carl R. Darnall Army Medical Center adds a military healthcare employer on post. About 51 percent of Killeen’s households, or 30,211, are renter-occupied. Resident employment is spread across retail (8,455), health care (7,502), and education (5,809), per Data USA.
Now the skeptical part. Military demand swings with deployments and PCS cycles, and rents across portals read flat to soft: Apartment List is down 2.4 percent, Zumper down 8 percent, and Apartments.com showing a small rise. Sources disagree, so model a vacancy allowance rather than full occupancy. Killeen’s population is also contested, with the city estimating 164,027 and the Census Bureau reporting 160,616 for mid-2024. Either way, the base is large enough to support a rental market. It just isn’t a growth engine you can bank on.
Where the Proceeds Should Go
Cash-out proceeds are only as good as the next deal they fund. Pulling equity to buy another duplex or fourplex in Killeen, where door count and basis are the variables, makes the argument straightforward. Pulling equity to chase yield in a market where coverage doesn’t clear at current pricing is a different decision, and worth stress-testing first. Portfolio owners who already carry four or more financed properties will find the conventional lane has mostly run out, and DSCR becomes the practical path. A W-2 investor with one rental may be better served by the comparison of DSCR and conventional financing, since a conventional cash-out may cost less if personal income cleanly supports it.
While DSCR lenders active in Central Texas apply tighter sub-1.00 guidelines, Lendmire’s network includes select lenders that review sub-1.00 files case by case, typically with lower leverage and stronger credit. For LLC-held buildings, eligibility is subject to lender program requirements. Start with Lendmire’s primer on DSCR loans for how coverage is calculated, read the equity-extraction mechanics and refinance details, and see Lendmire’s Texas DSCR platform for the state overview. Investors who want a file reviewed can request a quote or call 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
Can a single Killeen house support a DSCR cash-out refinance?
Sometimes, but the margin is thin. Modeled at 75 percent LTV with taxes and insurance included, a three-bedroom near the local rent range covers at roughly 0.95 to 1.00. Four-bedroom rents can push into the low 1.1s. A house below 1.00 may still be reviewed through select sub-1.00 programs, subject to lender guidelines, lower leverage, and stronger credit.
Why do duplexes and fourplexes matter more here than in other Texas cities?
Local agents describe Fort Hood-area multifamily as mostly duplexes and fourplexes, and per-door rents are low. Stacking several rents under one loan is what can lift coverage above a single house. Because no neutral price data exists for these buildings, coverage has to be checked against the actual price and a rent survey.
DSCR vs. conventional financing
Two common ways to finance an investment property in Killeen, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Should I count on appreciation to create the equity for a cash-out?
No. Zillow’s index is down 1.0 percent year over year, while the Texas REALTORS median is up 6.5 percent, and the two measure different things. The safer approach is to underwrite on current rent and sale comps. Cash-out is capped at 75 percent LTV, and the proceeds depend on the payoff balance and the appraisal.
How does military turnover affect underwriting?
Turnover from PCS moves supports steady leasing but calls for realistic vacancy planning. Lenders review the rent schedule, so current leases for occupied units and a market-rent survey for vacant ones help. Coverage cushions above 1.00 matter more here than in a market with long, stable tenancies.
Is North Killeen or West Killeen better for a refinance?
It depends on the investor. North Killeen offers the lowest basis but also the lowest rents, so coverage is sensitive to a single vacancy. West Killeen shows higher rents but faces new apartment supply. Neither wins outright, and the choice tracks how much vacancy risk the investor can absorb.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. Lendmire was recognized by Scotsman Guide as a 2026 Top Workplace and as a 2025 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $220,742
3. Zumper — Rent Research Killeen TX
4. soldiersofrealestate.com — Fort Hood
5. Texas REALTORS figure relayed by Homevets Realty
8. Rent.com
10. City of Killeen
11. KDH News
12. Rentometer
13. Redfin — Killeen Housing Market
16. Carl R. Darnall Army Medical Center
17. renter-occupied
18. Data USA
19. recognized by Scotsman Guide as a 2026 Top Workplace
20. a 2025 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Killeen, TX · Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.