
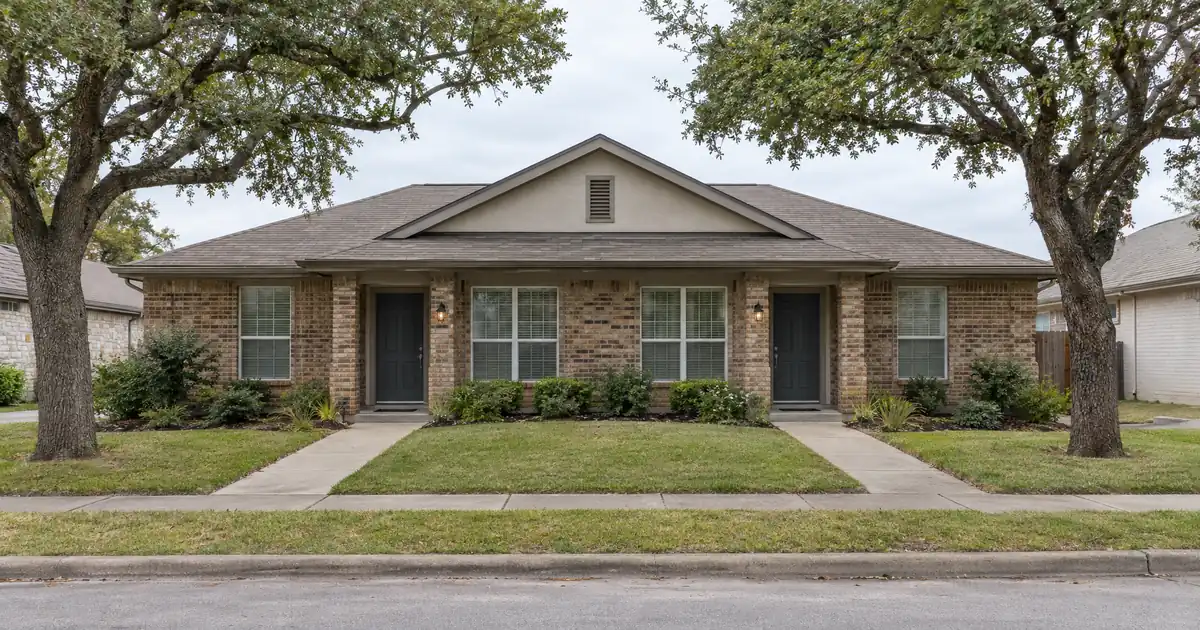
The southwest side of Bedford, the 76022 ZIP along the Bedford–Euless Road corridor, is where a cash out refinance on an investment property gets its most honest test. Entry prices there are the most accessible in the city, the renter share is higher than in the north, and the vacancy picture is noisier. An investor sitting on equity in a 76022 rental has to ask one question before any other: does the rent still cover the new loan once the balance goes up? Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. For real estate investors in Bedford, Texas, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C.
DSCR Cash-Out Calculator
Run the cash-out numbers in Bedford, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on an investment property in Bedford, Texas is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds sized by a loan-to-value ceiling, a seasoning period, and reserves, all subject to lender guidelines and property review.
- Redfin shows a $382K median sale price, up 3.3% year over year. Zumper puts median house rent at $2,485, so gross rent-to-price is roughly 0.65% (computed).
- ACS-based data shows 76021 vacancy at 3.67% against 10.42% in 76022.
- Cash-out is capped at 75% LTV after about six months of seasoning; the coverage ratio usually binds first.
Bedford Market Snapshot
A quick read on the Bedford investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 156 sales in may (Redfin Bedford Housing Market) |
| Typical rents | $1,502 (Zip-codes.com, ZIP 76021) |
| Recent appreciation | +3.3% yoy (Redfin Bedford Housing Market) |
| Employment | 1,300+ employees (GuideStar, Texas Health HEB) |
| Vacancy | 3.67% (Zip-codes.com, ZIP 76021) |
Why the Median Price Is the Wrong Collateral
At the citywide median, the coverage ratio is the constraint, not the LTV cap. Redfin’s $382K median sale price against Zumper’s $2,485 median house rent works out to a gross monthly rent-to-price of about 0.65%. That is arithmetic on two sourced figures, not a published Bedford ratio. Well short of the 1% rule.
Run the numbers on a modeled basis, with full PITIA (principal, interest, taxes, and insurance) at Texas-average tax and insurance loads. A rental appraised near the $382K median, refinanced at the 75% ceiling and renting at $2,485, lands in the low 0.9s on coverage. At the $2,350 three-bedroom rent Zumper also reports, it drops a little further. Below the 1.00 benchmark that most standard programs are built around. Pull leverage back toward 70% and the same property sits near 1.0. The 75% cap is a ceiling, not a target, and on median-priced Bedford stock the coverage number sets the real loan size.
Some lenders review sub-1.00 files, usually with lower leverage, stronger compensating factors, different pricing, or more cash in. Whether a given file fits depends on lender guidelines, credit profile, reserves, and property review. Structuring options include a sub-1.00 program or an interest-only structure, framed as options a lender would review rather than assumptions.
Now the cheaper end. Movoto snapshots show small three-bedroom homes in 76022 listed in the $200Ks, well under the median (Movoto, illustrative listings, not medians). Model a home appraised near $280K with an assumed $2,000 rent, and the coverage runs around 1.05 at 75% LTV including taxes and insurance. The rent assumption is an input, not a market fact. Rents are fairly flat across price tiers here, so the lower-basis house clears the coverage test more easily than the median one. Condition decides the outcome, and a Form 1007 rent schedule will say so. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Two ZIPs, One Rent Level
Bedford’s two ZIP codes rent almost identically, so the coverage advantage belongs to the lower-priced stock, not to a “better” ZIP. ACS-based figures show median gross rent near $1,502 in 76021 and $1,500 in 76022. The 76021 median home value is $374,400 on the same data.
Vacancy splits them. The 76021 figure is 3.67%; the 76022 figure is 10.42%, with 52.47% of 76022 housing renter-occupied against 48.25% in 76021. ACS vacancy includes seasonal and for-sale units, so it is not a rental-only rate, and 10.42% sits close to the national figure that source cites. Treat it as a directional flag. It is the only sourced vacancy signal for Bedford, and lender rent-loss assumptions on a 76022 file should be underwritten more conservatively than on a 76021 file.
Demand in 76022 has a real anchor. GuideStar’s profile of Texas Health Harris Methodist Hospital Hurst-Euless-Bedford reports more than 1,300 employees and more than 670 physicians on staff, and lists it as a Level III Trauma Center. The campus is in 76022. Nurses and allied staff make a stable tenant base for nearby rentals, though that is an inference from the employment data, not a measured rent premium.
The 76021 side, along the Harwood corridor and the Colleyville border, shows up in a neighborhood-level blog as higher-priced, larger-lot housing with scarce rental inventory. That source is commercial and unverified, so take it qualitatively: owner-occupant-style product, weaker on rent-to-price. Skip it for cash-out plans that depend on rent coverage.
Product Fit: Thin Multifamily, Townhomes, and 1980s Stock
Bedford’s rental stock is mostly small-complex apartments and older buildings, with very little of the duplex and fourplex product that normally helps DSCR math. RentCafe puts 74% of rentals in complexes under 50 units, 12% in larger buildings, and 13% in single-family rentals. Point2Homes shows 40% of rental units built between 1980 and 1989. Expect roofs, HVAC, and foundations to draw attention at appraisal.
Small multifamily is a scarcity play, not a volume play. A Zillow duplex and triplex search for Bedford showed no homes for sale at the time of search, and Apartments.com listed only three duplexes for rent as of the May snapshot. Point-in-time snapshots, but the message is consistent. A multi-unit owner has few comps for rent schedules and appraisals, and sourcing the next one likely means looking in Hurst, Euless, or North Richland Hills.
Townhomes fill the gap. Apartments.com townhome listings show an average rent of $2,000, ranging from $1,345 to $2,750, with Bedford Meadows and Shady Brook among the named areas. That rent is close to single-family levels at typically lower basis. The catch is HOA dues. They count in full PITIA and can quietly pull a 1.1 file down toward 1.0.
One more flag: the apartment benchmark and the house benchmark are different animals. RentCafe’s $1,338 average is a complex number, down 0.64% year over year, while Zumper’s house median is $2,485. Sources disagree because their property mixes differ, so anchor the pro forma on the appraisal’s rent schedule, not a portal.
Appreciation Isn’t Doing the Work
Bedford is a cash-flow-and-renovation market, and cash-out sizing should reflect that. Redfin shows a 3.3% year-over-year price gain and homes sitting 26 days on average, with 156 sales in May. One blog describes the market as essentially flat after several years of rapid appreciation, and a multifamily sponsor’s market note characterizes Bedford as a mature Mid-Cities market where value comes from execution and renovation rather than new development or population growth. Both are qualitative, and one is promotional. The direction still matches Redfin.
Consider a scenario. An investor owns a 76022 house bought years ago with a balance now equal to about 50% of appraised value. The 75% ceiling leaves roughly 25 points of value as gross proceeds, before reserves, costs, and the coverage test cut into it. If rent only supports 1.0 at 70% leverage, the usable number is smaller, closer to 20 points. The calculator on the site converts percentages into dollars. The point is that a flat market won’t rescue a thin file. Equity built by renovating a 1980s house and lifting its appraised value, supported by rent comps, is the more realistic source of extractable cash. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Seasoning is the other gate. Most programs look for about six months of ownership measured from title recording, so a recent purchase with a light rehab sometimes sits just outside the window. Reserves run about six months of PITIA on most files, more on larger balances. Credit tiers step up across 620, 660, 680, and 700, with 620 as the floor, and pricing improves as the score climbs. Standard programs go up to $3,000,000, though Bedford balances will rarely approach that. Smaller balances route through select lenders in the network. All of this is subject to lender guidelines. For the mechanics, see cash-out refinance details, and for rate-and-term alternatives, the refinance side.
Where Cash-Outs Stall
Bedford cash-out files rarely fail on the big idea. They stall on documents. A short list of the usual friction points:
- Rent support. A Form 1007 or lease copies showing the rent the math assumes. If the lease is below market, the lender may use the lower figure.
- Seasoning proof. The recorded title date, plus the original closing statement, especially when a property was acquired in an entity name.
- Insurance declarations. Current, matching the vesting and the loan amount requested.
- HOA or townhome documentation. Dues, budgets, and any condo or PUD questionnaire.
- Condition items. On 1980s stock, appraisers flag roofs, HVAC, and foundations, and the file can pick up repair conditions before it moves forward.
- Entity paperwork. For LLC-titled properties, vesting documents and operating agreements, depending on program guidelines.
The common friction point in markets like this one, where rents are flat and the stock is older, is a mismatch between the rent the borrower expects and the rent the appraiser’s schedule supports. Cleaner files, from a documentation standpoint, tend to arrive with the lease, the prior closing statement, and a current insurance quote already in the folder. Files that come in short on any of the three tend to re-open questions late, and the coverage number gets re-run each time the inputs move. That is how a file at 1.08 becomes a file at 1.01.
Real estate investors in Bedford can talk through the numbers on a specific property, or reach Lendmire at 828-256-2183. State-level program context sits on the page for DSCR loans in Texas.
What Does the Cash Go Into Next?
Proceeds are only as good as the next acquisition’s coverage, and Bedford’s demand base supports holding but not reaching. Data USA shows health care and social assistance as the largest industry at 3,130 workers, followed by transportation and warehousing at 2,780 and educational services at 2,739. The local economy employs 26.2k people, and employment fell 2.08% from one year to the next. A dip, not a collapse, and a caution for anyone underwriting growth.
The employer list is concentrated. Per the city’s annual report as summarized on Wikipedia, the top employers include Texas Health Resources at 1,480, Carter BloodCare at 961, and HEB ISD at 796 (verify against the primary report before quoting). Bedford had 49,928 residents and 21,693 households at the last Census count. Point2Homes reports median household income of $83,971. Those numbers describe a steady renter pool, not a boom. Half of households rent, per RentCafe’s count of 10,206.
The stronger redeployment play might be buying the next asset at lower basis, in adjacent Mid-Cities submarkets, than recycling proceeds into another median-priced Bedford house, though investors who prefer to stay local will argue for the 76022 corridor. Either way, size the next purchase with the same full-PITIA coverage test. Investors should verify current local rental rules, taxes, and insurance with qualified local professionals before committing. For the wider comparison, the guide “Where DSCR and Conventional Diverge” covers why property-income underwriting matters for self-employed and entity-held borrowers, and Lendmire’s DSCR guide covers the basics.
Frequently Asked Questions
Can a median-priced Bedford rental support a full 75% LTV cash-out?
Usually not on rent alone. Modeled with full PITIA, a home near the $382K median with a $2,485 house rent lands in the low 0.9s at 75% and near 1.0 around 70%. Lower-basis homes in 76022 tend to clear more easily. Outcomes depend on lender guidelines, credit, and reserves.
DSCR vs. conventional financing
Two common ways to finance an investment property in Bedford, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How does the six-month seasoning rule affect a recent Bedford purchase?
The clock generally starts at title recording, not at contract or rehab completion. An investor who bought a dated 76022 house and renovated it may need to wait out the window before pulling proceeds. Keep the recorded deed and closing statement in the file.
Does the vacancy gap between 76021 and 76022 change underwriting?
It can change the investor’s own assumptions even if the lender uses the appraiser’s rent schedule. The ACS-based figures show 3.67% in 76021 and 10.42% in 76022, though ACS vacancy includes non-rental units. Stress-test 76022 files with more cushion.
Are duplexes easier to refinance in Bedford?
Two units can strengthen coverage in theory, but supply is thin. Few comps make rent schedules and appraisals harder to support, so a multi-unit cash-out here can need more documentation, not less.
What about townhomes in Bedford Meadows or Shady Brook?
They are a reasonable fit at roughly $2,000 average rent, but HOA dues feed directly into PITIA and into condo or PUD review. Confirm dues and project eligibility before modeling.
Last Word on Bedford
If you only take one thing from this piece, it’s this: in Bedford, where rents sit near 0.65% of a $382K median price and appreciation is modest, the coverage ratio rather than the 75% LTV cap decides how much equity you can pull, so the cash-out that works is on the lower-basis 76022 house, not the median one. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines — which works for self-employed investors, LLC operators, and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin
2. Zumper
3. Zip-Codes.com — Zip Code Zip Code
4. Zip-Codes.com — Zip Code Zip Code
5. Texas Health Harris Methodist Hospital Hurst-Euless-Bedford
6. Movoto
7. RentCafe
8. Point2Homes
10. Apartments.com townhome listings
11. Data USA
12. Wikipedia
13. Point2Homes
14. 2025
15. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Bedford, Texas: The 2026 DSCR Refinance Guide to Harwood Road · Cash Out Refinance Investment Property in Euless TX · DSCR Cash Out Refinance in Euless, Texas: The 2026 DSCR Cash-Out Guide to the SH 183 Corridor
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.