
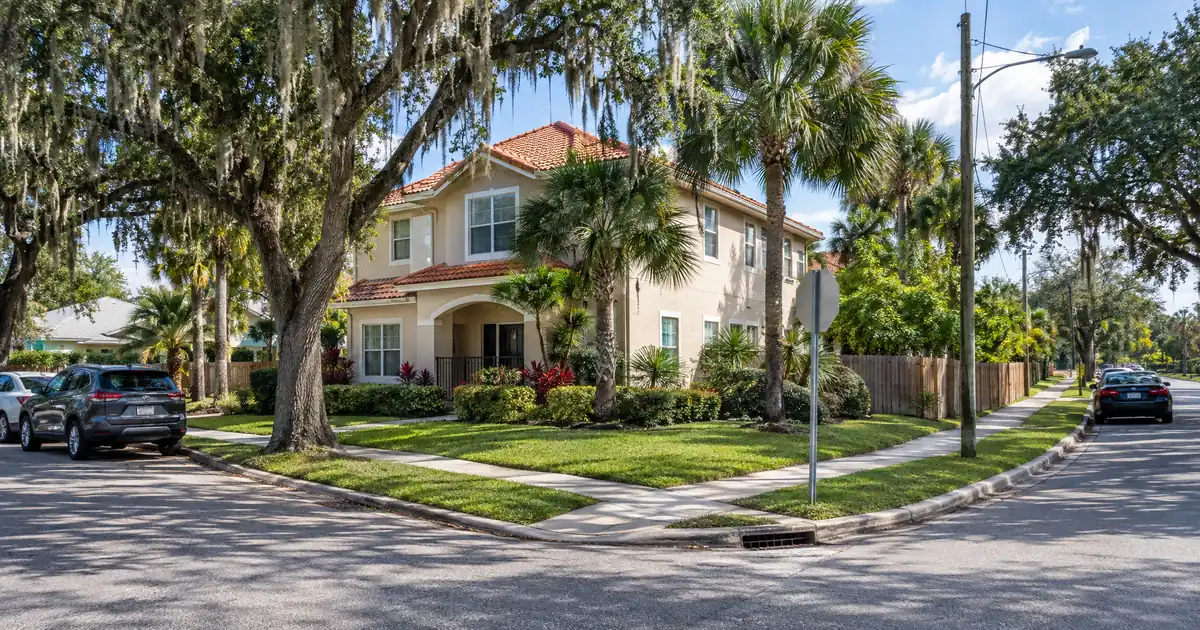
Kissimmee values are drifting the wrong way for anyone counting on appreciation. Zillow puts the average home value at $355,971, down 3.2 percent over the past year, and Apartment List shows median rent at $1,398, down 2.8 percent year over year. Over the next 6 to 18 months, cash-out files here will be won or lost on rent evidence and buy-in basis, not market lift. This is a DSCR cash out refinance market for owners who already hold a rental and want to pull equity into the next deal. It is not a purchase market.
TL;DR: A DSCR cash-out refinance in Kissimmee, Florida is underwritten primarily on the property’s rental income measured against its full monthly obligation, then capped by appraised value and leverage limits, with seasoning and reserves documented before the file goes to the lender.
DSCR Cash-Out Calculator
Run the cash-out numbers in Kissimmee, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out LTV tops out at 75 percent, and seasoning runs about 6 months from title recording.
- Buenaventura Lakes and Poinciana carry the long-term rent data. The resort belt does not.
- Values are soft: Zillow shows a 3.2 percent one-year decline.
- Duplexes tend to clear coverage more comfortably than single-family rentals at similar prices.
Kissimmee Market Snapshot
A quick read on the Kissimmee investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | 12,000+ valencia students (Choose Osceola) |
| Population | 84,767 population (Census Reporter (ACS 2024 5-yr)) |
| Employment | 17,780 combined top-5 employees (WFTV / Orlando Business Journal) |
| Vacancy | 10%+ ltr in pockets (MaxLife Realty Vacancy) |
What Changed for Equity in Kissimmee
Equity here is thinner than the purchase-era narrative suggests, and the sources disagree on how thin. Redfin shows a $349K median over the trailing three months, up 1.5 percent year over year, with homes sitting 58 days on average. Zillow is negative on the year. Momentum Realty’s MLS-based page shows a $392,000 median sale price, down 3.7 percent, with about 23 percent of Osceola listings carrying a price cut. Different methods, different mix. Don’t average them.
Read together, the market is flat to slightly soft. Cash-out proceeds come off appraised value, so a borrower who assumed the property gained value since purchase can land with less equity than planned. Deals bought below market or improved after purchase carry the refinance thesis. Market lift does not.
Seasoning, LTV and Reserves: The Mechanical Part
The cash-out ceiling is 75 percent LTV. That is a hard cap on the network’s programs, and it sits below the purchase ceiling. Seasoning is about 6 months of ownership, measured from title recording, so the settlement statement or recorded deed is what proves it. Files that assume seasoning away get kicked back.
Other parameters worth knowing, all subject to lender guidelines and varying by borrower and property:
- Coverage: 1.00 is the standard benchmark, rent measured against full principal, interest, taxes and insurance.
- Credit: tiers start at a 620 floor, with better positioning at 660, 680 and 700.
- Reserves: about 6 months of the monthly obligation, documented with statements.
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed to select lenders.
Cash-out proceeds are not a guaranteed figure. They depend on rent used for lender review, the full monthly obligation, reserves and the 75 percent ceiling. For entity-titled properties, LLC vesting is subject to lender program eligibility, so pull the operating agreement and EIN letter before the file goes in. Lendmire’s DSCR cash-out refinance page covers the structure, and Lendmire’s refi programs show how rate-and-term and cash-out differ. For the qualification basics, see the guide “What Is a DSCR Loan”. Florida-specific guidance lives on the hub page for DSCR loans in Florida.
Buenaventura Lakes: The Workforce Core
Buenaventura Lakes (ZIP 34743) is the strongest long-term-rental submarket for this kind of file. It is an older workforce suburb, with homes built between 1975 and 2006, about 30 minutes from Orlando’s airport and theme parks. RentCafe’s listing snapshot shows 3-bedroom houses averaging $2,344, with a top of $3,307 and starting points near $1,800. It is undated, so treat it as a range, not a comp.
Run the numbers on a modeled BVL house bought near the city median with 75 percent leverage and rent at that $2,344 average. Including taxes and insurance, coverage hovers right around 1.0. Not a cushion. Pull rent toward the low end of the range and the number slips under 1.00.
A newer benchmark helps here. Summerwell BVL, a build-to-rent community, lists 3 to 4 bedroom townhomes from $2,450 to $2,720. That is new product, so it sets a ceiling rather than a floor for older stock. Appraisers pick comps, and an older house is rarely priced like a new build.
Poinciana: Better Yield, Thinner Margin?
Poinciana (ZIP 34758 and 34759) is the cheap end of the city, and the rent evidence conflicts. RentCafe shows an average Poinciana rental home at $1,800, with a range of $1,365 to $2,250. True North Managed puts the Poinciana average near $1,400 and groups it among the metro’s higher gross-yield areas, at 8 to 10 percent, with more hands-on management. Likely different property mixes.
Model a Poinciana house near $295,000 (the low end one brokerage blog cites from Stellar MLS, so directional only) at 75 percent leverage with rent at $1,800. Including taxes and insurance, coverage lands just under 1.00. Use True North’s $1,400 and it drops well below.
Sub-1.00 files are not dead ends, but they are different files. A lender may review a sub-1.00 program, a lower LTV, an interest-only structure or a larger reserve position. Each of those changes leverage or pricing, and eligibility depends on credit, reserves and the property review. The stronger play might be a Poinciana duplex over a Poinciana house, though a borrower who prefers simpler management could argue the other way.
Duplexes Change the Coverage Math
The second unit is what lifts a coverage number. A 2021-built duplex listing in Kissimmee shows two 3-bed, 2-bath units at about 1,290 square feet each with proven rent of $1,850 a unit, or $3,700 combined. A Poinciana-area duplex is listed at $505,000 for 6 bed and 4 bath. Model it at 75 percent leverage with two units at the roughly $1,800 Poinciana average. Including taxes and insurance, coverage sits around 1.1. That is an illustration using modeled rent, not a quoted deal.
Two cautions. First, 2-to-4-unit stock is thin. Homes.com listings show most of it in Poinciana and downtown, plus an outlier 16-unit portfolio of four quadplexes. Comps will be sparse, and the appraiser may stretch for them. Second, unit mix matters as much as price. The same listing data shows a downtown Historic District duplex with two 1-bed units grossing $2,000 a month, a very different rent profile from a Poinciana 3/2 duplex. Underwrite each property on its own leases.
Where Cash-Out Files Stall
The appraisal rent schedule is the most common failure point. Lease evidence and the appraiser’s market-rent figure have to reconcile. When they don’t, the lender uses the lower number.
Three Kissimmee-specific pressures push that number down:
- New supply. True North Managed says Osceola County accounted for 59 percent of Orlando’s apartment deliveries in a recent year, and that absorption kept pace on workforce demand. Still, new apartments compete with 1 and 2 bedroom units and older stock.
- Conversion landlords. MaxLife Realty reports pockets of Kissimmee running 10 percent or more long-term rental vacancy, with converted product bid down in the same subdivisions. It is a brokerage blog with no stated methodology, so attribute it and verify locally.
- Metro vacancy. The Orlando-Kissimmee-Sanford metro shows 9.4 percent rental vacancy. That is a metro figure, not a city one.
DSCR files in markets like this one typically look the same on paper: rent that pencils near the 1.0 benchmark, leverage close to the cap and a value that came in a little soft. The files that hold together carry signed leases with payment history, entity documents already matched to the vesting and reserve statements sourced and seasoned. When the appraisal comes back light, a reconsideration request with recent in-neighborhood sales and condition adjustments is a routine step, not an emergency. Lendmire, a DSCR-focused mortgage broker, structures these files with that packet built before submission. Investors can talk through the numbers before choosing between a refinance and a hold.
Demand Anchors Behind the Rents
Tenant demand comes from jobs, and the county’s job base is tourism, healthcare and education. The WFTV and Orlando Business Journal list of Osceola’s largest employers puts the top five at a combined 17,780 employees: the School District of Osceola County, AdventHealth Celebration and AdventHealth Kissimmee (tied), Disney Destinations, Publix and county government. Wikipedia lists AdventHealth Kissimmee at 3,565 employees in the same ranking year. Valencia College’s Osceola campus sits on US-192 and serves more than 12,000 students, per Choose Osceola.
City-level, Census Reporter lists 84,767 residents, and RentCafe reports 52 percent of households are renter-occupied. RentCafe also shows average apartment rent at $1,809 and 3-bedroom rent at $2,353. Zumper’s all-property median is $2,195, down 5 percent. The figures differ because each source blends property types differently. Use them with attribution.
Skip the Resort Belt for Long-Term Cash-Out
The US-192 corridor, Reunion, ChampionsGate and Celebration are a different product. Celebration is the premium tier, and Apartment List shows it with the metro’s slowest annual rent growth, at negative 3.5 percent. No long-term-rental rent source turned up for the resort communities, so coverage math there rests on thin evidence. Florida Home Group Realty warns that many tourist-adjacent HOA communities restrict rentals. That makes HOA questionnaire completeness and condo certification the file’s gating items, ahead of the numbers. Verify current local rental rules, taxes and insurance with qualified local professionals before underwriting any of it.
Where the Asymmetric Opportunity Sits
The underpriced side of Kissimmee is Poinciana and Buenaventura Lakes small multifamily: 2-to-4-unit stock priced off the same soft market as single-family houses, but carrying two rents. Buy it below market, document the leases and season it. That is the file where a 75 percent cash-out has the best chance of leaving usable capital for the next acquisition.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Kissimmee?
Qualification runs on the property’s rent against its full monthly obligation, with 1.00 as the standard benchmark. Lenders also review credit tier, reserves of about 6 months, seasoning near 6 months from title recording and a property appraisal. Eligibility depends on lender guidelines and the borrower’s overall profile.
What are the requirements for an investment property cash-out loan in Kissimmee, Florida?
Expect a 75 percent LTV ceiling, a 620 credit floor, reserve documentation and lease or rent-schedule evidence. Entity-owned properties need operating documents, subject to lender program eligibility. Loan sizes reach up to $3,000,000 on standard programs, with smaller balances routed through select lenders.
Does soft appreciation in Kissimmee reduce cash-out proceeds?
Yes. Proceeds are capped by appraised value times the 75 percent ceiling, so a flat or falling value shrinks the available equity. Zillow shows a 3.2 percent decline while Redfin shows a 1.5 percent gain, so the appraisal, not a headline median, decides the number.
DSCR vs. conventional financing
Two common ways to finance an investment property in Kissimmee, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Which Kissimmee property type gives the best chance of clearing 1.00 coverage?
Duplexes generally do better than single-family rentals at similar prices, because the second unit adds income without doubling the price. Stock is thin, though, and downtown one-bedroom duplexes rent very differently from Poinciana 3/2 units. Underwrite from actual leases.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on DSCR investor loans. It arranges financing in 41 markets, Washington, D.C. included, through wholesale and investor-lending channels. Lender review centers on the property’s rental income rather than W-2 documentation, subject to lender guidelines, which suits entity-owned and multi-property investors. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and was a top-ranked workplace in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Kissimmee
2. Apartment List, Kissimmee Rent Report
3. Choose Osceola, Higher Education
4. Census Reporter (ACS 2024 5-yr)
5. WFTV, Osceola County’s Largest Employers
7. Redfin, Kissimmee Housing Market
8.
9.
10.
11.
12. one brokerage blog cites from Stellar MLS
13. Redfin — Kissimmee Multi Family Homes for Sale
14.
15.
16. True North Managed says Osceola County accounted for 59 percent of Orlando’s apartment deliveries
17. The Orlando-Kissimmee-Sanford metro shows 9.4 percent rental vacancy
18. Wikipedia lists AdventHealth Kissimmee at 3,565 employees
19. Valencia College, Osceola Campus
20. Census Reporter, Kissimmee Profile
21. RentCafe, Kissimmee Rent Trends
22. Zumper’s all-property median is $2,195, down 5 percent
23.
24. recognized by Scotsman Guide as a 2026 Top Workplace
25. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Kissimmee FL · Investment Property Loans in Kissimmee, FL: The 2026 DSCR Financing Guide to NeoCity · Cash Out Refinance Investment Property in Lake Worth, Florida: Small Multifamily Equity Recycling
Guides: Investment Property Cash-Out Refinance in Kissimmee, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.