
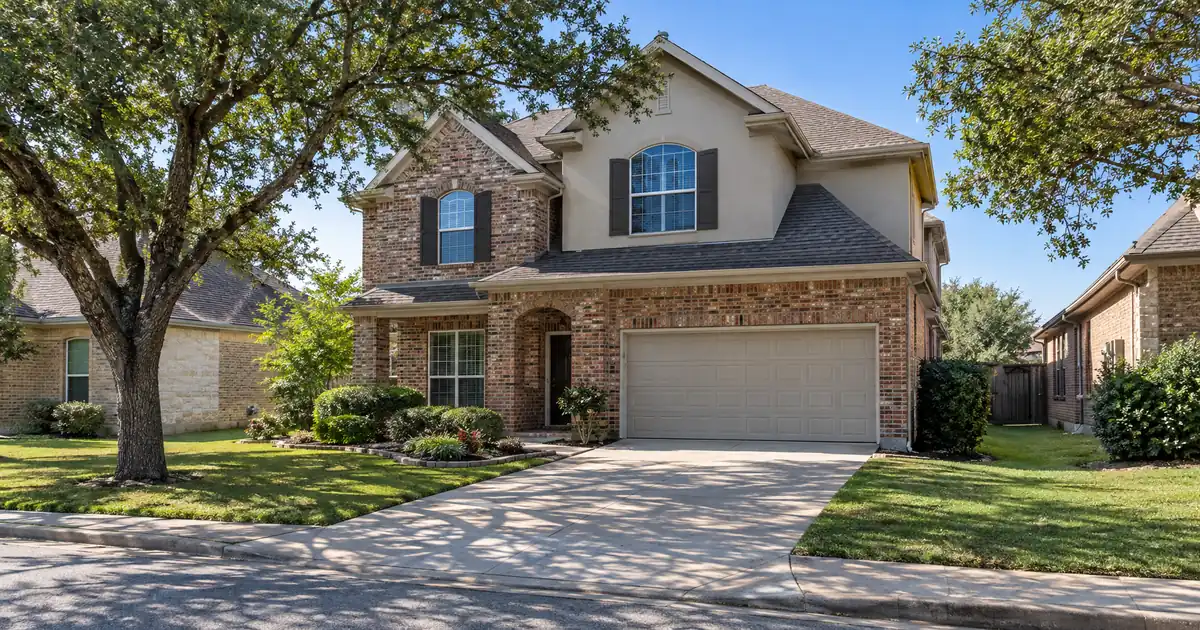
The equity is there. The rent isn’t. That’s the shape of the cash-out file that stalls in this market, and it stalls at the coverage calculation, not at the appraisal. A Southlake, Texas rental can carry a strong value on paper, but the lender still divides rent used for lender review by the full monthly obligation (principal, interest, taxes, insurance, and any HOA dues) and needs the result to land near 1.00x or better. Most of Southlake’s housing stock struggles to get there.
DSCR Cash-Out Calculator
Run the cash-out numbers in Southlake, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on a Southlake, Texas rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with leverage capped at 75 percent of value, about six months of recorded ownership, and documented reserves, so a high appraised value alone does not carry the file.
- Citywide rent runs a small fraction of home value, so modeled coverage at 75 percent leverage lands below 1.0x.
- Townhomes and condos near Town Square are the likeliest place to approach the 1.00 benchmark.
- Reserves step up to about nine months on balances above $1,500,000, which touches many estate-tier files.
- Sales volume is thin: Redfin counted 19 homes sold in one recent November.
Southlake Market Snapshot
A quick read on the Southlake investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $1.3M median (Redfin Southlake Housing Market) |
| Typical rents | $7,418 rent for 4-bed (HAR.com, Southlake) |
| Employment | 13.4K to 13.6K employees (Data USA, Southlake) |
The Rent-to-Value Gap Is the Whole Story
Southlake’s rents are among the highest in Texas, and its prices are higher still. Zumper puts median rent across property types at $6,000, flat over the prior month and year, though that reading is dated. Zillow shows an average home value of $1,313,920, up 2.5 percent over the past year. Divide one by the other and monthly rent runs about 0.46 percent of value. The zip-level numbers from HAR are worse: a $9,199 rent on a four-bedroom house against an average price of $2,550,999 works out near 0.36 percent.
Run the numbers on a modeled basis. At 75 percent LTV, with taxes and insurance included in the full obligation at Texas-average levels, a rent of 0.46 percent of value produces coverage somewhere around 0.6x. Round it down and say it plainly: below 1.00. The 0.36 percent case is worse. These are modeled figures, not sourced market data, and lender programs vary. The direction holds, though.
Averages and medians also differ by source, and Southlake’s mean is skewed by estate sales. Rent figures split too. Niche shows a median above $3,500, while Zumper shows $6,000. Treat every citywide number as directional and price the actual property.
Here’s the catch on sub-1.00 files. A 1.00x baseline is common because rent covers the debt service at that level. Some lenders will review lower ratios, but usually with lower leverage, stronger reserves, or different pricing. Options a lender may review include a sub-1.00 program, an interest-only structure, or a smaller cash-out request. All of it depends on lender guidelines, credit, and property review. Even at materially lower leverage, a typical Southlake house stays tight on the number.
Where the Coverage Number Clears: Town Square
The lowest entry price in the city sits in the townhomes, condos, and smaller homes around Southlake Town Square. One local agent guide puts that band at $500,000 to $700,000, and it’s agent content, so read it as directional. No sourced neighborhood rent median exists for this area.
Consider a modeled case. Say a townhome is worth $600,000 and you assume $4,000 in monthly rent. That’s an assumption, not a cited comp. At 75 percent LTV and including taxes and insurance, coverage lands just under 1.0x. Push the assumed rent up a few hundred dollars and the file clears. Pull it down and the file goes to a lower-leverage conversation. That’s how thin this margin is.
The rent evidence matters more than the value. Listings around Town Square show a wide spread, and the newest luxury apartment building sits well above anything an investor-owned townhome would command. Zillow’s apartment listings show two-bedrooms from $8,164. Don’t use that as a comp. It’s an outlier, and a lender’s rent schedule will not rely on it.
If the townhome has a signed lease, the file is cleaner. If it’s vacant or owner-occupied and being converted, the appraiser’s market-rent opinion carries the coverage figure, and it may come in lighter than the investor expects. Use the DSCR math tool to test both cases before ordering anything. (An appraisal fee spent on a file that can’t clear is money gone.)
Timarron and the 1990s Neighborhoods
Timarron is the golf-anchored master-planned community: about 1,200 acres and 1,550 homes, dating to the early 1990s. One agent page reports closed prices from $650,000 to $2,675,000 with a median sale price of $952,000. Another says homes typically start in the high $700,000s. Sub-area pricing steps down north of Continental Boulevard and east of Byron Nelson, and the executive golf-course homes south of Continental sit at the top.
Much of the stock was built in the 1990s and early 2000s, so many homes need updates. That’s the value-add angle. It’s also where cash-out files get tricky. Renovation spending can lift the appraised value, but the appraiser decides how much of it counts, and the six-month seasoning clock runs from title recording, not from the last permit closing. Files that assume the renovated value on day one are the ones that get cut back.
The older 1990s neighborhoods on the south and west sides (South Ridge Lakes, Myers Meadow, Southlake Woods) are described locally as the closest thing to an entry point. No reliable price or rent figure surfaced for them. Qualitatively, they’re the single-family-rental option that sits below the Timarron golf-course tier, and the coverage math still runs thin. This is a genuine toss-up: lower prices help the ratio, but rents don’t drop in proportion.
Skip the Estate Enclaves
Shady Oaks, Coventry Manor, and Monticello are gated estate enclaves where privacy is the product. A comparable estate-lot area runs $1.4 million to $2 million and up, though that range can’t be tied to one neighborhood. Winding Creek, a boutique enclave of about 45 homes built mostly after 2013, ranges from $1.2 million to $2.1 million.
These are owner-occupied estates with very poor rent-to-value. A DSCR cash-out doesn’t fit them. If a property here is truly rented, the file also trips the reserves step-up: about six months of PITIA on most files, and about nine months when the balance passes $1,500,000. Standard programs run up to $3,000,000. Reserves documentation on a large balance is a real ask, and it’s the line that gets missed.
Appraisal Risk in a Thin-Sales Market
Southlake’s comp pool is small, and that’s the core appraisal risk. Redfin counted 19 homes sold in November, down from 22 a year earlier, with homes averaging 56 days on market and selling about 4 percent below list over the trailing three months. Zillow shows values up. Redfin’s sales-based read is softer. The gap is likely a mix effect from a small monthly sample.
One estate-tier closing can move the median, and a mid-priced house may be appraised off comps that are older, farther away, or in a different price tier. That caps the cash-out value even when list prices look strong. Treat appraisal reconsideration as a routine step: recent in-neighborhood sales, condition adjustments, and a clean list of upgrades with dates. A well-built packet recovers value more often than an angry email does.
The deal desk pattern in markets like this is consistent. The cleaner files from a documentation standpoint have the lease, entity documents, title, and property details in hand before the appraisal is ordered. The common friction point is an investor who set a cash-out target from a listing price or a Zillow estimate, then found the appraisal supported less. Ask for a broker opinion of value first. Then pick the leverage target.
Demand Anchors and Where the Proceeds Go
Tenant demand here tracks corporate employment. Per a dated city employer table on Wikipedia, Sabre Holdings employs 2,550 people, Carroll ISD 1,176, and Verizon Wireless 685. TD Ameritrade’s listed 2,230 is stale, since the firm has since been absorbed into Schwab. Next door in Westlake, Fidelity Investments runs a 332-acre campus. Data USA shows resident employment of 13.6 thousand, led by health care (2,158), professional and technical services (1,936), and finance and insurance (1,687).
Healthcare adds a steady base: Methodist Southlake Medical Center is a 54-bed acute care hospital, and Texas Health Southlake offers 18 surgical specialties. Select Southlake reports 81 percent office occupancy and 95 percent retail occupancy. That supports renters at the top of the market. It does not support workforce-rent underwriting.
The renter base is small. AreaVibes puts renter-occupied households 85 percent below the national average. Supply is thin and the city is nearly built out, so vacancy data doesn’t exist at an usable level.
Which brings up the second half of an equity-extraction plan: where the money goes. Nearby Grapevine apartments start around $1,116 for a one-bedroom and $1,472 for a two-bedroom, and those are apartments, not investor-purchasable houses. The likelier play is pulling proceeds from a Southlake property and deploying them into a higher-yield DFW submarket. The equity-extraction mechanics and rate-and-term and cash-out refi details cover how proceeds are structured. Lendmire’s Texas DSCR loan programs cover the state-level framework. For the general concept, see the guide “What Is a DSCR Loan”, and for the contrast with bank underwriting, the guide “Where DSCR and Conventional Diverge”.
What the Lender Wants in the File
Documentation is where preventable gaps show up. A Southlake cash-out file should have:
1. The recorded deed or settlement statement, which sets the seasoning clock at about six months from title recording.
2. A current lease, or lease evidence, plus a rent schedule that reflects the property’s actual condition.
3. Entity documents if the property sits in an LLC, subject to lender program eligibility.
DSCR vs. conventional financing
Two common ways to finance an investment property in Southlake, TX. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
4. Reserves documentation sized to the balance, since the requirement rises above $1,500,000.
5. A credit profile clearing the program floor of 620, with the tiers moving up from there.
6. Current hazard insurance evidence and the HOA or association details for townhomes and condos.
Equity available depends on rent used for lender review, the full obligation, reserves, and the 75 percent ceiling. It is not a guaranteed cash figure. Investors should verify current local rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR loan in Southlake, Texas?
The property’s rent used for lender review is measured against its full monthly obligation, and the ratio typically needs to reach about 1.00x. Lenders also review credit (floor 620 in the network), reserves of about six months, and ownership seasoning for cash-out. Because Southlake rents are thin against values, expect the file to hinge on the rent evidence and on leverage well below the ceiling. All of it is subject to lender guidelines and property review.
What are the requirements for a cash-out refinance on an investment property in Southlake, Texas?
Cash-out tops out at 75 percent LTV, with about six months of ownership measured from title recording. Standard programs go up to $3,000,000. Reserves run about six months of PITIA, and about nine months above $1,500,000. Coverage still needs to work, and the appraisal sets the value, not the listing.
Can a Southlake investor count on appreciation to fund a cash-out?
No. Zillow shows values up 2.5 percent, while Redfin’s sales data shows a softer market and homes selling about 4 percent below list. The appraisal decides, and with roughly 19 sales in a recent month, one closing can swing the comp set. Set the leverage target after a broker opinion of value.
Why do so few Southlake properties clear 1.00 coverage?
Rent runs roughly 0.36 to 0.46 percent of value per month, while the full obligation at 75 percent LTV runs meaningfully higher. Townhomes near Town Square, at lower price points, come closest. Reaching the benchmark generally takes lower leverage, an interest-only structure, or a sub-1.00 program that is reviewed case by case. Call 828-256-2183 to talk through a specific property.
The Blind Spot in This Market
No neighborhood-level rent source exists for Southlake. There is no vacancy figure and no cap-rate data. The rents that circulate are single listings and luxury apartments, and they make the market look better than a lender’s rent schedule will. Build every file on a documented lease or a conservative appraiser rent opinion, and assume the citywide averages flatter you. That’s the biggest blind spot for DSCR-financed investors here: not the equity, but the rent evidence behind the number.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than the borrower’s W-2 history, a practical fit for LLC-titled portfolios and self-employed investors. All scenarios remain subject to the lender’s review and program guidelines. The firm has been recognized as a 2025 Scotsman Guide Top Workplace and a 2026 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Southlake housing market
4. Zumper, Southlake rent research
5. Zillow, Southlake home values
7. Zillow’s apartment listings
8. Wikipedia, Southlake, Texas
10. Methodist Southlake Medical Center
11. Select Southlake, fast facts
12. AreaVibes
13. a 2025 Scotsman Guide Top Workplace
14. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Southlake Texas: Access Equity Without Income Docs · Cash Out Refinance Investment Property Colleyville Texas · Cash Out Refinance Investment Property Coppell Texas
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.