
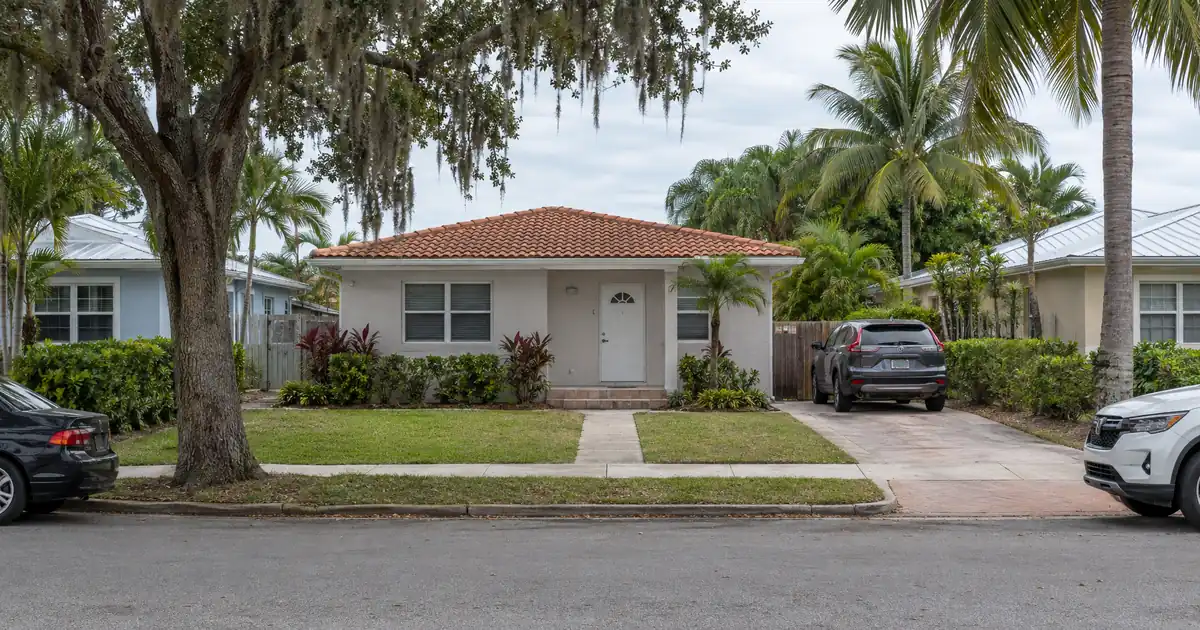
A cash-out refinance comes down to two things the borrower doesn’t control: the appraisal and the lender’s read on the building. Hallandale Beach puts both in play. Zillow shows the average home value at $278,711, down 5.0 percent over the past year. Most of the housing stock is condos and townhomes, where HOA dues and project eligibility get reviewed before anyone sizes a loan.
Lendmire works with Hallandale Beach, Florida investors through a DSCR program footprint spanning 40 states plus Washington, D.C. (NMLS# 2371349). As a DSCR-focused mortgage broker, it places files with wholesale lenders rather than lending directly. The equity-extraction question here is more specific than “can I pull cash out?” It’s whether the appraisal, the building, and the in-place rent all hold up together.
DSCR Cash-Out Calculator
Run the cash-out numbers in Hallandale Beach, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A DSCR cash-out refinance in Hallandale Beach, Florida suits investors who already own condos, townhomes, or scarce small multifamily with seasoned equity and in-place leases. The file is underwritten primarily on the property’s rental income measured against its full monthly obligation, then sized by appraised value under a 75 percent loan-to-value ceiling.
- Condo and townhome listings total 998 at a $310,000 median list price, per PBP Real Estate.
- Zillow shows values down 5.0 percent year over year, which shrinks available proceeds.
- Older stock and the northwest redevelopment corridor offer the best rent-to-value logic.
- Seasoning runs about 6 months from title recording before a cash-out is reviewed.
- Parks at Hallandale adds 398 new units to lease up nearby, per The Real Deal.
Hallandale Beach Market Snapshot
A quick read on the Hallandale Beach investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $2,100–$4,200 asking rents (The Real Deal) |
| Vacancy | 4.6% (Miami Finance Review) |
Condos Are the Market, So Warrantability Is the Underwriting
Hallandale Beach is a condo city that happens to have a few single-family streets. Per PBP Real Estate and BeachesMLS data, the split looks like this:
| Property type | Median list | Sold year-to-date median |
|---|---|---|
| Single-family | $649,900 | $536,500 |
| Condo/townhome | $310,000 | $240,000 |
Single-family has 57 active listings and 48 sales year to date. Condos and townhomes have 998 listings and 446 sales. That 446 figure is the comp pool an appraiser draws from on most refinances here.
It also means the lender’s review of the building matters as much as the borrower’s profile. HOA dues belong in the obligation side of the coverage calculation, and a project with thin reserves or heavy investor concentration can complicate the file. Some programs are more restrictive on condos than others, so confirm eligibility before ordering an appraisal. The side-by-side comparison of DSCR and conventional underwriting shows why this matters: a DSCR file skips the personal-income review, but the property and its project take the full scrutiny.
The Zillow figure and the PBP figures don’t conflict. They measure different slices. Zillow’s $278,711 blends everything, and the PBP numbers split by type. Cite by type, and don’t assume your property sits at the blended number.
What a Five Percent Dip Does to Proceeds
Falling values hit cash-out harder than they hit the headline number, because the existing payoff doesn’t move. Run it as a modeled assumption, in index points rather than dollars. Say the current payoff equals 60 percent of a property’s appraised value. At the 75 percent ceiling, the gross equity available is 15 points of original value. Let the appraisal slip 5 percent, and the ceiling drops to 71.25 points. Available equity falls to 11.25 points, a quarter smaller, before costs and reserves.
That’s the arithmetic behind the caution. Per Redfin, Atlantic Shores shows a $175,000 median over the last three months, down 2.8 percent. Investors who bought near a peak, or who are counting on appreciation to fund the next acquisition, should assume the appraisal may come in flat or lower. Proceeds depend on rent used for lender review, full PITIA, reserves of about 6 months (about 9 above $1.5 million), and the 75 percent cap. They aren’t a guaranteed figure, and eligibility stays subject to lender guidelines. Seasoning is the other gate: about 6 months of ownership, measured from title recording.
The longer story is less gloomy. The Real Deal describes Hallandale Beach as the next Broward County development target, with residential towers, a branded hotel, and an office project underway. One broker there attributes it to rising Miami-Dade and Palm Beach prices pushing buyers north. That’s broker opinion, and a pipeline also means new-build competition. The appreciation case supports holding. It doesn’t support underwriting a cash-out on the assumption that value gains will cover it.
Rents: Underwrite the In-Place Lease
Rent data here is messy, and the mess is the lesson. Zumper puts the citywide average at $2,350, down 1 percent year over year. Reaction Realty Group cites $2,350 to $2,500 with a 2 to 3 percent decline. RentCafe shows $3,096 for buildings of 50 or more units, down 6 percent from $3,294 the year before. That last figure covers institutional mid-rise product, not the small-building stock most individual investors own.
Apartment List shows averages of $1,400 for a studio, $2,047 for a one-bedroom, $2,796 for a two-bedroom, and $4,409 for three or more bedrooms. It flags every unit size as trending down.
Soft rents and soft values together squeeze coverage from both directions. Use signed leases, not pro-forma rents, when sizing a cash-out. On a modeled basis including taxes and insurance, condos with meaningful HOA dues tend to sit near the 1.00 benchmark rather than comfortably above it. Most standard DSCR programs are built around that benchmark. Some lenders review lower-coverage files with lower leverage, stronger credit, or more cash in reserve, but those structures cost something. The refinance details cover how lenders weigh that tradeoff.
Parks at Hallandale: The Supply Wave Next Door
Parks at Hallandale is a 398-unit development on 15.5 acres near Pembroke Road. Per The Real Deal, the first 100 units began welcoming residents in April, with the remaining 298 expected to deliver by summer. Asking rents run from $2,100 to $4,200 across studios through three-bedrooms. The developer’s workforce page shows some units designated at 120 percent of Average Family Income.
Two readings, both true. It signals real renter demand for workforce-priced housing. It also puts about 400 units into lease-up at once, and concessions on new product can pull achievable rents down on older units nearby. Small landlords in the northwest quadrant should underwrite conservatively and avoid anchoring to the new building’s asking numbers.
Where the Numbers Hold: Older Stock and the Northwest Corridor
The strongest rent-to-value logic sits in older, lower-priced stock. The northwest quadrant along the Foster Road corridor is the city’s community redevelopment area, and its own CRA FAQ describes little residential construction there for decades, with an 89-unit City Center project and townhome infill now underway. The CRA paint program offers up to $3,000 for single-family and up to $6,000 for multi-unit dwellings, which tells you the city expects multi-unit stock in this zone. Verify current terms before counting on it.
Reportedly, a few small duplexes sit west of I-95. They’re scarce and unconfirmed in the research, with no reliable rent or price data. For an owner who already holds one, scarcity cuts both ways. Fewer comps means more appraisal variance, but two rent streams stacked against one debt obligation is the cleanest coverage structure in this market. If you own one, get the appraisal scope and comp selection discussed before it’s ordered.
Atlantic Shores is the other entry-price pocket. At a $175,000 median, the rent-to-value ratio should be stronger than in higher-priced neighborhoods, but HOA dues and condo eligibility decide whether that advantage survives underwriting. Near Gulfstream Park, Reaction Realty Group notes that demand stays strong, especially west of the entertainment district. Gulfstream Park (racing, casino, retail, and home of the Florida Derby) is the confirmed local employment anchor, though no headcount was verified. Hospitality and gaming jobs supply mid-wage tenants, which is the profile workforce-priced units serve.
Skip the Waterfront for Cash-Out
Oceanside high-rises and Golden Isles waterfront are the wrong places to chase cash-out proceeds for DSCR purposes. Golden Isles shows a $265,000 median list price per Movoto, though that looks condo-weighted. Waterfront single-family there is a premium product bought for lifestyle, not rent-to-value. Three Islands has a Walk Score of 29, so tenants depend on cars. Nothing wrong with owning there, but these aren’t where the coverage math is strongest, and appraisal variance on unique waterfront properties is wider. Hold them, but don’t count on them to fund the next purchase.
What Deal Desks See in Markets Like This
In condo-dominated coastal markets, the friction point on cash-out files is rarely the borrower. It’s the gap between the rent an owner believes the unit commands and what the lease in place actually shows, plus a condo questionnaire that comes back late. The cleaner files tend to have a signed lease at or near market, a documented HOA dues figure, and an LLC vesting issue resolved before submission. Hold title in an LLC and the file proceeds subject to lender program eligibility. Lendmire’s team sees the most avoidable delay when those three items arrive out of order.
Frequently Asked Questions
Can I pull cash out of a Hallandale Beach condo?
Many programs review condos, but eligibility hinges on the building, not just you. Lenders look at the project’s HOA reserves, investor concentration, and litigation status, and they count HOA dues in the obligation. Some lenders exclude certain condo projects entirely. Confirm the building’s eligibility before paying for an appraisal.
How much does a soft appraisal cut my proceeds?
More than proportionally. With a modeled payoff at 60 percent of value and a 75 percent cap, a 5 percent lower appraisal cuts the available equity by about a quarter. The smaller your equity cushion, the more a modest value decline matters. Sellers who bought recently, or whose prior refinance already pushed leverage up, have the least room.
DSCR vs. conventional financing
Two common ways to finance an investment property in Hallandale Beach, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Should I underwrite to Parks at Hallandale’s asking rents?
No. Those rents reflect new-construction pricing and a building in lease-up. Underwrite to the signed lease on your own unit. If your lease sits well below nearby new-build asking rents, that may be an upside story for renewals, but lenders generally qualify on in-place rent and the appraiser’s market-rent opinion.
Do duplexes west of I-95 work for a DSCR cash-out?
The coverage logic is strong because two rent streams sit against one loan, but the market is thin. Expect limited comps, which can widen the appraiser’s range. Small multifamily here is scarce enough that owners often hold rather than refinance, which is also why few sale comps exist. Discuss appraisal scope with the lender’s team before ordering.
How long do I have to own before cashing out?
About 6 months, measured from the date the title was recorded, on standard programs. Reserves of about 6 months of PITIA are typical, and a credit floor of 620 applies, all subject to lender guidelines. For a full walkthrough, see the refi options and the guide “What Is a DSCR Loan”.
Investors can review Florida DSCR financing or call 828-256-2183 to talk through a specific scenario. Verify current local rental rules, taxes, and insurance with qualified local professionals before you underwrite.
Three Things to Watch Next Quarter
- Lease-up at Parks at Hallandale. If concessions deepen or asking rents drop from the $2,100 to $4,200 band, expect pressure on older-unit renewals nearby.
- Condo sold medians versus list medians. The gap between the $310,000 list and $240,000 sold medians is the discount appraisers are working from. A narrowing gap would signal firmer refinance appraisals.
- Zillow’s year-over-year value trend. A move from down 5.0 percent toward flat would meaningfully widen cash-out capacity for owners who were waiting.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire — NMLS# 2371349 — is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. Lenders commonly review DSCR eligibility around property-level rent rather than personal income documentation, subject to lender guidelines. The brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Lendmire was recognized by Scotsman Guide as a top-ranked workplace in 2026 and recognized by Scotsman Guide in 2025 as a Top Mortgage Workplace. See Lendmire’s 2026 Top Workplace announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Value Index, Hallandale
2. PBP Real Estate, Hallandale Beach market data
3. The Real Deal, Hallandale Beach development
5. Redfin, Atlantic Shores housing market
6. Zumper, Hallandale Beach rent research
7. RentCafe, Hallandale Beach rent trends
9. parksathallandale.com — Developer’s workforce page
10. Hallandale Beach CRA residential programs
11. Gulfstream Park
12. Movoto
13. Scotsman Guide — Top Workplaces 2026
14. recognized by Scotsman Guide in 2025
15. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Hallandale Beach, Florida · DSCR Cash Out Refinance in Sunny Isles Beach, Florida: The 2026 DSCR Guide to Collins Avenue · DSCR Cash Out Refinance in Deerfield Beach, Florida: Equity Is Thin, Duplex Rents Are Not
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.