
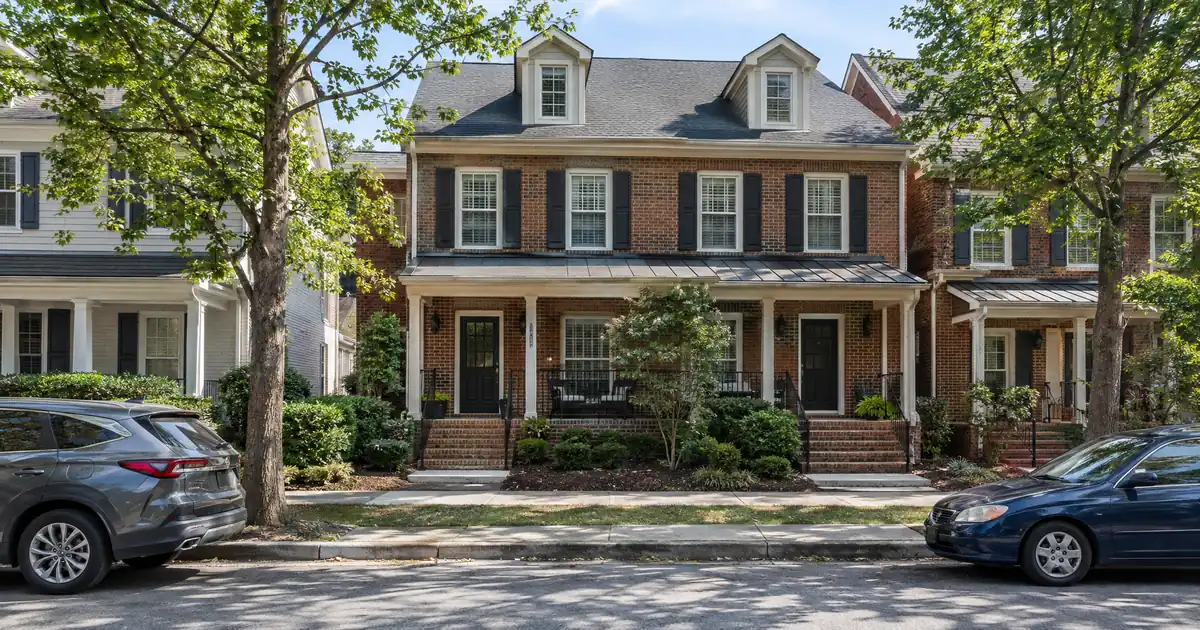
Picture an investor who bought a duplex in Athens at around $300,000, kept both units leased, and now wants the equity out for the next purchase. The leases are in place and the property has been owned long enough. The open question is how much of the equity survives a 75 percent LTV ceiling, an appraisal built on very few comparable sales, and a coverage test that includes taxes and insurance. That question decides whether the refinance happens, and it is a file question, not a market-sentiment question.
DSCR Cash-Out Calculator
Run the cash-out numbers in Athens, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A cash-out refinance on an Athens, Tennessee rental is underwritten primarily on the property’s rental income measured against its full monthly obligation. It fits owners of small multi-unit buildings or workforce 2-3 bedroom rentals who can document leases and reserves and who are comfortable with a modest, appraisal-dependent equity pull.
- Cash-out proceeds are capped by a 75 percent LTV ceiling, not by how much the property has appreciated.
- Ownership of about six months, measured from title recording, is the typical seasoning gate.
- Athens has very few duplex listings, so appraisal comps can hinge on one or two sales.
- Rental demand tracks a supplier-plant payroll, which is steady but concentrated.
- Coverage math must include taxes and insurance. P&I-only numbers mislead here.
Athens Market Snapshot
A quick read on the Athens investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $300,000 median sold (City of Athens) |
| University enrollment | 1,177 total (Tennessee Wesleyan) |
| Employment | 21,454 workers (McMinn County EDA) |
| Vacancy | 4% (AffordableHousingOnline McMinn) |
What the Athens Numbers Actually Say
Athens equity is real but modest, and the sources disagree on price. The City of Athens cost-of-living page shows a median sold price of $300,000 and a median listing price of $315,000, with homes averaging 75 days on the market and 75 percent selling below asking. Redfin puts the median sale price at $238K, down 0.5 percent year over year, with 88 days on market. Prop:Metrics lands in between at $253,000.
That is a $60,000-plus spread between sources, so cite a range and name the source whenever you quote a value. Underwrite to the appraisal, not to any one of these medians.
Pricing here reads as flat to modestly up, with frequent below-ask sales. That is not an appreciation-driven equity story. The equity most Athens owners are extracting comes from paydown, below-market purchase prices, or value-add work, not from a market that ran away from them. The cash-out math should be built on that assumption.
The Rent Side: Use In-Place Leases
Rent data is mixed, and the trend is inconsistent. Zumper shows a median rent of $1,090 across all types and rents up 16 percent year over year. Prop:Metrics, citing Rentcast, reports median rents of $854 for a 1BR, $1,020 for a 2BR, $1,540 for a 3BR, and $1,670 for a 4BR. It shows 2BR and 3BR units making up 43.9 percent and 29.3 percent of rental stock. The city’s own page lists average rents of $849, $921, and $1,404 for 1BR, 2BR, and 3BR units.
Headline growth figures vary widely by source, and at least one aggregator shows rents flat. Don’t underwrite on growth. A lender reviewing the file will use the in-place leases or a market-rent opinion from the appraisal, and the lease evidence should be what the borrower’s own numbers rest on.
The 3BR-to-2BR rent jump is large. That makes duplexes with three-bedroom units, and small buildings with larger units, the likeliest way to stack income, though that is inference, not a sourced yield.
Duplex Versus Single-Family: The Premium Isn’t Where You’d Expect
Duplexes in Athens do not carry a clearly better rent-to-price ratio than single-family homes. A listing snapshot from Realmo showed three active Athens duplexes priced from $299,900 to $349,000, averaging $324,450. Two 2BR units at the $1,020 Rentcast median gross about $2,040 a month, roughly 0.63 percent of that average price. A 3BR single-family at $1,540 against $238K-$300K prices runs roughly 0.51 to 0.65 percent. That is arithmetic on asking prices and median rents, not a sourced yield.
What a duplex adds is a second rent stream. If one unit goes vacant, the other still pays, and lenders read that as stability. It is not a yield premium, so don’t promise one.
Run the numbers on a modeled duplex valued near $325,000 with two 2BR units at $1,020 each. These are modeled assumptions, not market facts. At 75 percent LTV, with full PITIA including taxes and insurance, coverage lands around 1.05, and you should round down from there. Now run a 3BR single-family at $1,540 on a $300,000 value at the same leverage. Including taxes and insurance, that sits in the high-0.8s, below the 1.00 benchmark. At a $253,000 value, the same house gets close to 1.00.
If the number lands below 1.00 on long-term rent alone, the paths a lender may review include a lower-leverage cash-out, a sub-1.00 program, or an interest-only structure. Qualification stays subject to lender guidelines, credit approval, and property review.
Small multifamily stacks better. One Athens listing advertises a six-unit, three-story building with per-unit asking rents between $1,150 and $1,325. It is an undated asking-rent example, so treat it as directional only. The mechanism is what matters: total rent rises faster than price when units stack on one parcel, which lifts the coverage number.
The Comp Problem (Where Athens Files Get Stuck)
Thin multi-unit inventory is the main friction point on an Athens cash-out file. Realmo showed only three active duplexes in the city, and its own page pointed to four more in nearby cities. Redfin’s 37303 multi-family page lists the same handful. Few listings mean few recent sales, and an appraiser may lean on one or two comps or reach outside the city.
Working DSCR brokers see a recurring pattern in small markets with a thin multi-unit comp pool: the appraisal, not the borrower’s credit or the lease, sets the proceeds. A value that comes in $20,000 light changes the loan amount at 75 percent LTV more than any pricing tweak. Files that go in with an appraisal reconsideration packet ready, meaning recent in-area sales, condition adjustments, and a documented rent schedule, recover value more often than files that treat the first number as final.
Budget conservatively. Assume the appraisal could come in under the borrower’s expectation, and size the plan so a shortfall doesn’t break the next acquisition.
The Demand Anchor: One Plant, One Hospital, One Small University
Athens rental demand rests on a plant payroll more than on a campus or a tourism draw. DENSO Manufacturing Athens is the county’s largest employer at 1,444 employees. A $100 million expansion adds 200 jobs and 54,560 square feet of production space, bringing the footprint to 879,000 square feet. The state’s 2018 release shows an earlier $190 million expansion with 320 jobs, so this is a repeat-investment pattern, not a one-off.
The McMinn County EDA county profile counts 1,707 businesses employing 21,454 workers. It also shows 9,101 workers commuting into the county and 13,880 residents who live and work there. The city sits on I-75 between Knoxville and Chattanooga. That commuter flow is a second demand layer: workforce renters who want to live near where they work.
Starr Regional Medical Center adds more than 690 staff and 20 providers. Tennessee Wesleyan University reported a record enrollment of 1,177, up 11.6 percent. That is a small pool, and only some of those students rent off campus, so don’t underwrite student premiums. The 2BR and 3BR stock matches plant and hospital workers better.
The flip side is concentration. A single-employer anchor means a plant disruption would hit rents harder than it would in a diversified metro. Census Bureau QuickFacts puts the city population at 14,471, with a median household income of $53,929, which is a small, workforce-priced base.
On vacancy, an aggregator drawing on federal data, AffordableHousingOnline, shows McMinn County rental vacancy at 4 percent and renters at about 24 percent of the population. Treat that as directional, county-level, and secondary-source, not an Athens-city figure. It supports a modest vacancy haircut and signals a shallow rental pool.
How the Cash-Out Mechanics Work Here
Equity extraction follows a set order. Seasoning comes first: lenders typically want about six months of ownership, measured from title recording and documented by the settlement statement. A recent purchase doesn’t qualify for cash-out until that clock runs.
Next is the LTV ceiling. On cash-out refinances the program cap is 75 percent, a different number from the purchase cap, so don’t borrow the purchase figure. Proceeds are what’s left after the existing payoff and costs, and they depend on appraised value, rent used for lender review against PITIA, and reserves. Nothing guarantees a particular cash figure.
Then the standards. The common coverage benchmark is 1.00 rent against full PITIA, and most files need credit in the 620-and-up range, with better tiers at 660, 680, and 700. Reserves typically run about six months of PITIA. Loan amounts go up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network. Manufactured homes, log homes, and barndominiums fall outside these programs. All of this is subject to lender guidelines and varies by borrower, property, and loan scenario.
The clean file has the full lease set and rent schedule, the entity documents if the property is held in an LLC (subject to lender program eligibility), the settlement statement showing the recording date, a fresh insurance quote, and a reserves statement. Gaps in any of those pend the file. For the mechanics in more depth, see cash-out refinance details and the investment property refinance options. New to the product? Start with the DSCR fundamentals, and for the comparison with income-document loans, read DSCR versus conventional.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Athens, TN, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Investors can request a scenario review through Lendmire’s quote page or by calling 828-256-2183. Tennessee files are covered at the state level under Tennessee DSCR investor loans. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
How do you qualify for a DSCR loan in Athens, Tennessee?
Qualification centers on the property: rent used for lender review measured against full PITIA, with 1.00 as the common benchmark. Lenders also review credit (the floor is typically 620), reserves of about six months, and the lease documents. Because Athens duplex comps are thin, the appraisal’s value and rent opinion matter as much as the borrower profile. Final eligibility is subject to lender guidelines and property review.
What are the requirements for an investment property cash-out refinance in Athens, Tennessee?
Expect about six months of ownership from title recording, a 75 percent LTV ceiling, qualifying coverage of 1.00 or better, and reserves around six months of PITIA. You’ll need leases, a rent schedule, insurance documentation, and entity documents if the property is in an LLC. Proceeds depend on appraised value and are not a guaranteed figure.
Is a duplex or a single-family rental better for cash-out in Athens?
Neither has a clear yield edge on asking prices. A duplex at the Realmo average price and median 2BR rents works out to roughly 0.63 percent monthly rent-to-price, which is about on par with a 3BR single-family. The duplex’s advantage is two rent streams, which lenders view as a stability plus. Its drawback is the thinner comp pool, which raises appraisal variance.
Does the DENSO plant make Athens rental demand risky?
It makes demand steady but concentrated. DENSO’s 1,444 employees and repeated expansions support workforce rentals, and 9,101 workers commute into the county. But a single-employer anchor means a plant disruption would hit rents harder than in a diversified market. Underwrite on in-place leases and keep reserves documented.
Where the Asymmetry Sits
The mismatch in Athens is in small multi-unit buildings and three-bedroom rentals. The 3BR rent jump over 2BR is steep, the comp pool is thin enough that careful documentation can matter, and the plant-and-commuter payroll feeds demand near the DENSO and I-75 exit 52 corridor, where Ingleside Avenue connects the neighborhoods to the interstate. Sale prices there look flat, yet stacked units lift rental coverage. The owner who holds a duplex or a six-unit building with solid leases and a well-supported appraisal is the one who can pull equity without leaning on appreciation.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized by Scotsman Guide as a 2026 Top Workplace and a 2025 Scotsman Guide Top Mortgage Workplace, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. City of Athens, Cost of Living
2. Tennessee Wesleyan University, Enrollment Release
3. McMinn County EDA, County Profile
5. Redfin, Athens Housing Market
7. Zumper, Athens Rent Research
8. Realmo
9. Redfin’s 37303 multi-family page
12. Starr Regional Medical Center
13. Census Reporter, Athens City
14. Recognized by Scotsman Guide as a 2026 Top Workplace
15. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Athens Georgia · DSCR Cash Out Refinance in Bristol, Tennessee: Avoca Equity and a Thin Rent-to-Value Market · Cash Out Refinance Investment Property in Lewisburg, Tennessee: The 2026 DSCR Financing Guide to the Square
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.