
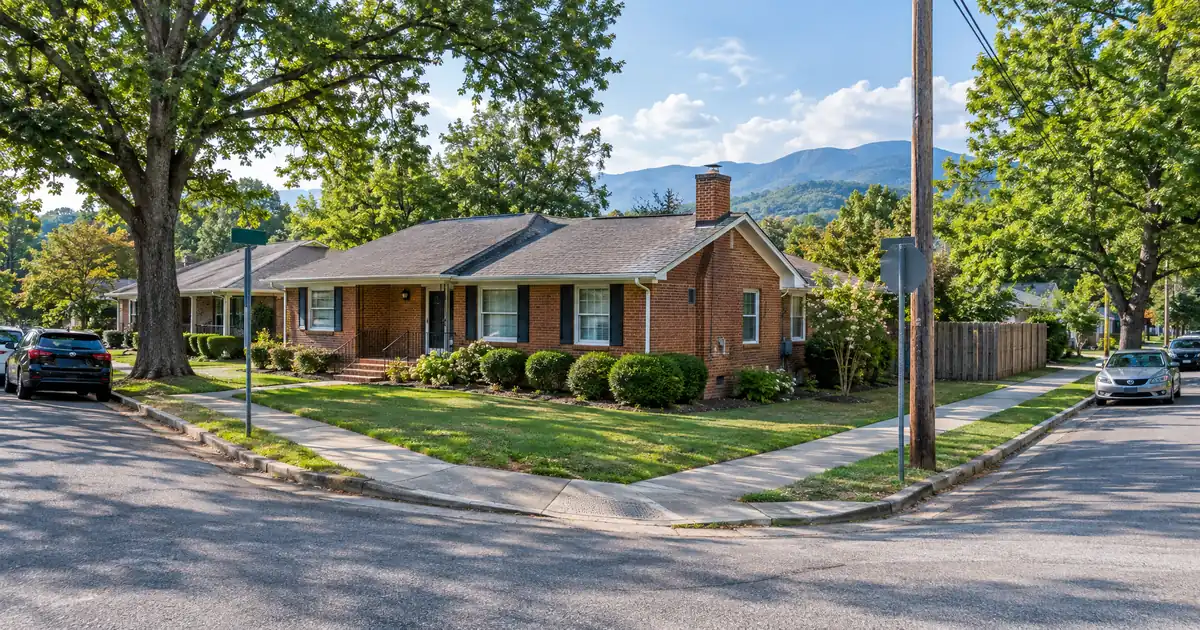
Cordova has no city government of its own. It is a large suburb that Memphis annexed in part and then partly gave back, and the de-annexation shed roughly 4,000 residents and about 1,800 housing units from the city. For anyone planning a cash out refinance on an investment property in Cordova, Tennessee, that boundary history matters more than it sounds. Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker, and Cordova, Tennessee is one of the 41 markets — 40 states plus Washington, D.C. — where Lendmire places DSCR loans for investment-property borrowers. This article assumes the purchase is done and asks one question: how much equity can this market realistically release, and what does it take to get there?
At a Glance: A cash-out refinance on a Cordova rental is underwritten primarily on the property’s rental income measured against its full monthly obligation. Seasoning, lease documentation, and lender review of rent, reserves, and the leverage cap all shape the deal.
DSCR Cash-Out Calculator
Run the cash-out numbers in Cordova, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out leverage tops out at 75% LTV, and seasoning is about six months of ownership from title recording.
- Sources put the median sale price near $295,000 and three-bedroom rent near $1,830, per Prop:Metrics.
- Single-family coverage runs tight. Small duplexes can carry better cushion on paper.
- Flat prices mean equity comes from your basis and paydown, not from appreciation. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Cordova Market Snapshot
A quick read on the Cordova investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,176 (Kirkland Company Memphis) |
| Vacancy | 14.10% (Kirkland Company Memphis) |
The Equity Math Is a Coverage Math Problem
In Cordova, the binding constraint on cash-out proceeds is usually coverage, not LTV. Rents are modest relative to home values in the area, so the loan-to-value cap often isn’t the number that limits the loan.
Prop:Metrics, drawing on Rentcast data, shows median rents of $1,270 for two-bedrooms, $1,830 for three-bedrooms, and $2,210 for four-bedrooms, against that $295,000 median home price (down 1.9% year over year). Redfin shows a slightly higher $297K median, up 2.8%, with homes sitting about 28 days. The sources disagree on direction and agree on the big picture: flat.
Run the numbers on a modeled three-bedroom. Assume a $295,000 value, $1,830 in rent used for lender review, 75% LTV, and full PITIA, meaning principal, interest, taxes, and insurance. Coverage lands right around 1.0 including taxes and insurance. That is the standard 1.00 benchmark, and it leaves almost no cushion. If the appraisal comes in light or the lender uses a lower rent, proceeds get trimmed to fit the ratio. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
DSCR is simply monthly rent divided by the full monthly obligation. The DSCR guide walks through the mechanics. What matters here is that Cordova single-family files rarely have room to spare.
Why Flat Prices Change the Playbook
Cash-out in a flat market comes from three places: a purchase basis below today’s value, forced appreciation through renovation, or years of principal paydown. It does not come from the market lifting your value during the seasoning window.
Sources split on direction. Prop:Metrics shows a 1.9% annual decline, Redfin shows a 2.8% gain, and Movoto’s list-price median of $329K is down 3%. Treat that spread as noise around a flat trend. Seasoning is about six months from title recording, and the 75% cap applies to the appraised value on the day of the refinance. So an investor who bought near the current median with little renovation should expect modest proceeds, not a windfall. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Don’t count on a cash-out built on an aggressive valuation. A DSCR loan is reviewed primarily on property-level rental income covering the payment, subject to lender guidelines, and the appraisal still sets the ceiling. Many Cordova sale comps sit within a narrow band, and appraisers lean on them.
Where the Coverage Works Best: Small Multifamily
Duplexes and small multi-unit buildings pencil better than single-family in Cordova, but inventory is thin and slow. Two rent checks against one tax bill and one loan is the cleanest path to real cushion.
Homes.com showed 14 multi-family listings priced from $148,900 to $386,000, averaging 64 days on market. Rentcast puts two-bedroom rent at $1,270 and one-bedroom at $1,160, and two-bedrooms and one-bedrooms make up the largest shares of rental stock. A modeled duplex with two-bedroom units grosses about $2,540. Priced near the top of that listing band, at 75% LTV and full PITIA, coverage comes out around 1.1 including taxes and insurance. These are modeled assumptions, not a listing’s actual rent roll. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
| Factor | 3BR single-family | Modeled duplex |
|---|---|---|
| Rent input | $1,830 | $2,540 (2 × $1,270) |
| Modeled price | $295,000 | $386,000 |
| Coverage at 75% LTV | About 1.0 | About 1.1 |
| Main friction | Thin cushion | Few comps, slow sales |
Thin comps are the catch. A cash-out appraisal on a duplex needs support, and a handful of sales over a long stretch makes that harder. Verify every listing’s rent roll before building a refinance plan around it. The cash-out refinance page covers how proceeds are sized, and the broader range of refinance programs is outlined separately.
Where to Hold Rental Stock in Cordova
Rent-to-value sources here are ZIP-level, not neighborhood-level, so treat these profiles as tenant and demand reads rather than priced comps.
Wolfchase. This is the retail hub around Wolfchase Galleria, with the densest apartment supply in Cordova. Tenants are retail and service workers and commuters using Germantown Parkway and I-40. That density is also the caution. An investor holding a single-family rental here competes with large apartment communities for the same renter, so concessions can cap rent growth. Conservative rent assumptions are the right call.
Countrywood and the Greenline corridor. Listings describe this area as near the Greater Memphis Greenline and Shelby Farms Park, a 4,500-acre green space. Trail access pulls renters who want suburban space, which favors three-bedroom houses. Of the submarkets here, this is the one where single-family rentals make the most sense.
Walnut Grove Lake and west Cordova. These residential streets sit closest to the campus of Baptist Memorial Hospital-Memphis, a 706-bed hospital on an 80-acre campus. Healthcare staff are a plausible tenant pool here, though that link is an inference, not a sourced fact.
Old Cordova and Dexter. Old Cordova is a small historic core with likely older housing and no price data. Dexter, east of Germantown Parkway, is apartment-heavy. Neither is where a cash-out play starts.
Demand Isn’t the Problem
Cordova renters are a real pool with real paychecks. RentCafe shows a 38% renter share, while a local property manager, EPM, puts it at 41.2% of 20,593 households. Median household income is $81,659 there (a commercial source, so weigh it accordingly). That is sizable for a place people label owner-heavy.
Tenants here commute. The metro anchors are FedEx, at 32,333 local jobs per Kirkland’s brokerage report, along with St. Jude, International Paper, and AutoZone. Healthcare is the other big employer type, including Baptist and Methodist Le Bonheur campuses nearby. The University of Memphis enrolls a sizable student body but isn’t close enough to make Cordova a student market.
Commercial brokerage IRR notes that east-side development is anticipating demand tied to Ford’s Blue Oval truck factory, including projects in Cordova. That’s a forward-looking tailwind. It’s also a warning that new apartment supply may show up near your property.
The Vacancy Question
Metro vacancy is the number that keeps coverage assumptions honest. Kirkland, citing CoStar, puts Memphis-area multifamily vacancy at 14.10%, forecast to ease to 12.20%, with average rent of $1,176 and 12-month rent growth of 0.7%. I found no Cordova-specific vacancy figure. The supply pressure IRR describes is concentrated in Downtown and Midtown, not Cordova, which helps suburban small-scale rentals. Still, underwrite the rent used for lender review conservatively and expect the lender’s rent to come in at or below your lease.
Rent sources vary widely, from $1,314 at RentCafe to $1,750 median at Zumper. Use the lower end for planning and lease-verified rent for the lender.
A Jurisdiction Split Worth Checking Before You Refi
Most of Cordova sits inside Memphis city limits, but it has been reshaped before. A petition for a further de-annexation had gathered more than 800 online signatures, per FOX13 Memphis, and no further de-annexation has happened. Bridgewater, for example, is a subdivision inside a county island. Two adjacent streets can sit under different jurisdictions, which can change the taxes and insurance that feed PITIA. Confirm each parcel’s status and costs with qualified local professionals before you model proceeds. That is the only place here where local rules come up, and it is enough.
Population figures shift with the boundary too: Wikipedia gives 68,779, Point2Homes gives 51,673, and ZIP 38016 is around 44,400. Roughly 45,000 to 69,000 is the honest range.
What the Deal Desk Tends to See
In suburban workforce markets like this one, the common friction on a cash-out file is rent documentation, not credit. The cleaner files from a documentation standpoint tend to arrive with executed leases, entity documents, the title recording date, and property details already lined up, and they tend to stay clean because the seasoning clock and the rent figure are easy to verify. Files with month-to-month tenants or a rent figure pulled off a listing portal tend to hit questions early. Reserves are the other recurring item, since programs generally look for about six months of PITIA behind the loan. Every point here is subject to lender guidelines and the borrower’s profile. A fresh look through the guide “Where DSCR and Conventional Diverge” shows why investors use the property-income path in the first place.
Using the Proceeds
Proceeds are capital, not profit. Eligible borrowers can generally go up to 75% LTV, credit starts at a 620 floor with better tiers at 660, 680, and 700, and loan amounts run up to $3,000,000 on standard programs. Actual cash depends on rent used for program review, PITIA, reserves, and the LTV ceiling. It isn’t a guaranteed figure.
The stronger play for most Cordova owners is probably a duplex or second small rental bought at a lower basis, with the refinance used to fund it, though an investor with a well-bought three-bedroom near the Greenline could reasonably argue the opposite. Either way, run the next purchase’s coverage before you pull equity, because this market punishes assumptions. Details on Lendmire’s Tennessee DSCR loan programs are available, and investors can see how the math pencils or call 828-256-2183.
DSCR vs. conventional financing
Two common ways to finance an investment property in Cordova, TN. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How much equity can a Cordova rental actually release?
Generally no more than 75% of appraised value minus the existing balance, and often less. Single-family rents here are modest against prices, so the coverage ratio frequently caps proceeds before the LTV does. Reserves of about six months of PITIA are also typical, subject to lender guidelines.
Does flat pricing hurt a cash-out plan in Cordova?
Yes, if the plan depends on appreciation. Sources show Cordova prices moving between a 1.9% decline and a 2.8% gain, which amounts to flat. Equity has to come from a below-market purchase, renovation, or paydown.
Is a duplex better than a single-family rental for a refi here?
On paper, usually. Two rent checks against one loan and tax bill can lift coverage to around 1.1 versus about 1.0 for a three-bedroom. The trade-off is thin inventory (14 multi-family listings) and slow sales, which makes appraisal support harder.
Does the Cordova jurisdiction split affect a DSCR refinance?
Yes, it can. Because parts of Cordova have shifted between Memphis and county jurisdiction, taxes and services can differ parcel to parcel. That difference flows into the PITIA the lender uses, so confirm each property’s status early.
How long must I own before cashing out?
About six months from the title recording date, per the verified program parameters. Lender guidelines and the specific file can change that.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire — NMLS# 2371349 — is a mortgage brokerage specializing in DSCR investor loans, helping arrange financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The model centers on property-level rental income reviewed by the lender rather than W-2 documentation, subject to lender guidelines, which suits entity-owned and multi-property investors. Lendmire is a top-ranked workplace in 2026 and was recognized by Scotsman Guide in 2025 as a Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. The Kirkland Company, Memphis Multifamily Report
3. Redfin, Cordova Housing Market
5. Homes.com, Cordova Multi-Family
7. Baptist Memorial Hospital-Memphis
8. RentCafe
9. EPM
10. IRR, Memphis Multifamily Report
11. Zumper
12. FOX13 Memphis
14. Wikipedia
15. Point2Homes
16. Scotsman Guide — Top Workplaces 2026
17. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Cordova, Tennessee: Pulling Equity From a Flat-Price Suburb · Investment Property Loans in Memphis, TN: What It Takes to Qualify on Rental Income · Cash Out Refinance Investment Property in Memphis
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.