
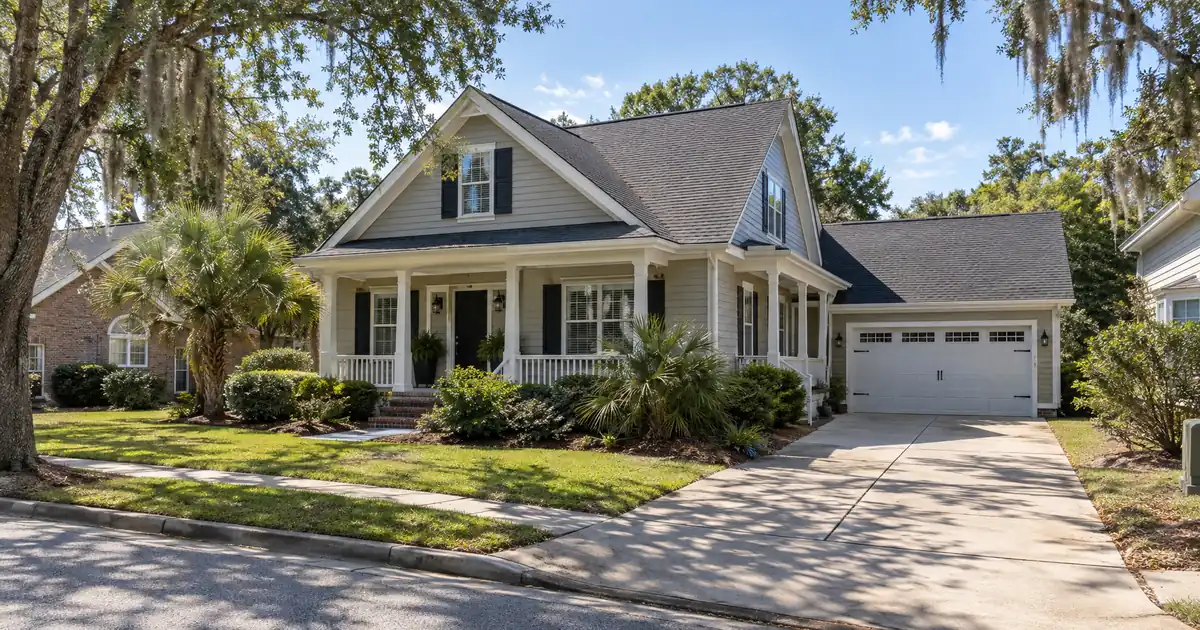
A three-bedroom in one of Gaffney’s newer subdivisions hits the DSCR math like this. Active Zillow rental listings show three-bedroom houses asking $1,100 to $1,495 a month, while CapRateCity models a citywide median price of $180,000 against a median rent of $990. Same town, same lender box, and coverage that swings from under 1.00 to comfortably above it depending on which house the investor owns. That swing is the whole story of a Gaffney cash-out.
The Quick Read: Cash-out on a Gaffney, South Carolina rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file works only when the appraised value, the rent used for lender review, and post-closing reserves all line up together, subject to lender guidelines.
DSCR Cash-Out Calculator
Run the cash-out numbers in Gaffney, SC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Modeled median single-family ($180,000 price, $990 rent) lands below 1.00 coverage once taxes and insurance are counted.
- Three-bedroom rentals listed at $1,100 to $1,495 carry the best rent per dollar of value.
- Values are flat, so equity comes from a purchase discount or value-add, not market lift.
- First Solar’s planned 600-job plant is the newest demand catalyst in the county.
- Roughly 13% of the housing stock is small multifamily, so duplex comps exist.
Gaffney Market Snapshot
A quick read on the Gaffney investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | ~1,600 students (University Herald, Limestone) |
| Population | 12,596 population (Census Reporter) |
| Employment | 600 jobs (SCBiz (Gaffney tag)) |
| Vacancy | 5.5% (CapRateCity) |
Start With the Three-Bedrooms
The three-bedroom houses in the newer subdivisions on the growing side of town are the best cash-out candidates in Gaffney. Rent per dollar of value beats the smaller units, and that is where refinance coverage has room to clear 1.00.
The spread is easy to see in the data. Rentcast figures via Prop:Metrics put median rent at $887 for a one-bedroom, $980 for a two-bedroom, and $1,520 for a three-bedroom in ZIP 29341. Two-bedrooms and three-bedrooms are the most common rental sizes there, at 33.9% and 31.4%. Listings in the Granite, Osage, and Cypress area sit in the low-to-mid $1,000s to $1,300s, with a larger four-bedroom out on the Ellis Ferry side asking $1,800. Those are listing snapshots, not leases. Treat them as evidence of the range, not as a rent roll.
Run the numbers on a three-bedroom appraised at $180,000 and renting at $1,250 (modeled inputs, not sourced comps). At 75% LTV, coverage including taxes and insurance lands around 1.15. That clears the 1.00 baseline that most standard programs are built around, with some cushion for a vacancy or a repair bill. Push the rent to the top of the listing range and the cushion widens. Drop to the modeled $990 and it disappears. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Here’s the catch: the rent has to be defensible to an appraiser, not just to the investor. A house that has never had a lease at $1,250 has to earn that number on market comps. Investors sitting on three-bedrooms with a signed lease near the top of the range hold the cleanest documentation for a refinance.
Lendmire (NMLS# 2371349) works with Gaffney, South Carolina investors to place DSCR financing through wholesale lenders reaching 41 markets — 40 states plus Washington, D.C. Gaffney is a thin market, and the underwriting question is almost always whether the house can carry a bigger loan than the one it already has. Lendmire’s South Carolina DSCR loan programs cover that state-level picture.
Why Median Single-Family Struggles
Median single-family in Gaffney is unlikely to clear coverage on a cash-out at full leverage. CapRateCity’s model shows net operating income of only about $730 a month at the median, and a 20%-down conventional purchase running negative cash flow on a monthly basis. Its own suggested fixes are larger down payments, seller financing, or buying 15% to 25% below median. It is a modeled aggregator, so read it as directional. Directionally, though, it’s blunt.
The arithmetic bears it out. A $180,000 house renting at $990 comes out around 0.9x on a 75% LTV refinance once taxes and insurance are counted. Not ideal. Zumper reports a citywide average rent near $950, down 5% year over year, and the ZIP-level Rentcast series shows a similar softening. Do not underwrite a rent increase into a Gaffney refinance. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Sub-1.00 files aren’t dead, but they get harder. Select lenders may review sub-1.00 scenarios, and an interest-only structure can change the coverage math. The trade is reduced leverage, stronger credit, deeper reserves, and more lender scrutiny. Qualification stays subject to lender guidelines, credit approval, and property review. For an investor holding a median-priced house with a $990 rent, the honest options are to hold and season it, to pull less cash than the 75% ceiling allows, or to skip the refinance and put the equity to work another way. Understanding how rental-income qualification works makes it easier to tell which side of that line a given house sits on.
Duplexes and Small Multifamily: Where Stacking Works
Small multifamily is Gaffney’s best cash-out structure, because two rents stacked on one basis lift coverage in a way no single-family house can. It’s also scarce.
NeighborhoodScout puts the housing mix at 66.25% single-family detached, 12.96% duplexes, converted homes, or small apartment buildings, and 17.90% large complexes. Roughly one unit in eight is small multifamily, so a refinancing duplex owner has real comps and a tenant pool that knows the product. The data vintage on that page is unclear, so use the shares as a rough proportion, not a census count.
For a cross-check on what stacking produces, small-complex asking rents on Zillow’s rental pages run from about $800 for a studio to $955 for a two-bedroom in one complex and $1,199 for a two-bedroom in another. Model a duplex appraised at $250,000 with two units at $950 each (assumptions, not comps). At 75% LTV, coverage including taxes and insurance comes out around 1.25. That’s a real file. The same duplex at a $360,000 appraisal lands under 1.00, which is why price basis matters more here than almost anywhere. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
The scarcity cuts both ways. Multi-unit listings in Gaffney are a handful at any given time, and asking prices in the mid-$300,000s and up don’t work at these rents. Small multifamily is a fit for investors who already own one bought at a discount. It isn’t a plan for someone hunting one from scratch. The refinance is the reward for a good purchase, and the purchase side is a separate conversation. The refinance side picks up from where ownership already sits.
Flat Values: Where Does the Equity Come From?
Gaffney values are flat, so cash-out equity comes from buying below market or adding value, not from appreciation. Anyone underwriting a refinance on the assumption that the house went up since purchase is going to be disappointed at the appraisal.
The sources disagree, and that disagreement matters. REAIGENT7 shows the ZIP 29341 median at $228,907, up 0.8% over the past year, with a three-year change of -0.8%, a five-year change of +8.5%, and a September 2022 peak of $236,936. Prop:Metrics shows -1.1% year over year at a $218,000 median and 75 median days on market. Movoto’s citywide median list price is $268,000, down 2%. CapRateCity’s claimed 3.4% annual appreciation conflicts with everything else, so leave it alone. Pick one source, quote it with its context, and keep moving. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Appraisal dispersion is the other risk. Resideline reports that the middle half of Gaffney sales runs from $130,000 to $262,000, at $101 to $149 per square foot, and that 97% of tracked closings are single-family. A band that wide means the appraiser’s comp selection can move the value a lot, and the value drives the 75% LTV ceiling. Picture an investor who bought a house at a real discount and renovated it, then refinances with comps pulled from the lower half of that band. The equity that seemed obvious can shrink at the appraisal table. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Seasoning is the mechanical piece. Programs in the network typically look for about six months of ownership measured from title recording before a cash-out. That’s a short window in most markets and a useful one in Gaffney, where the discount is usually baked in at the purchase. Investors who wait out the seasoning period and paper the rent with a lease tend to produce cleaner files than those who rush the window.
Who Actually Rents Here?
Gaffney’s tenant base is manufacturing and distribution workers, and the employer story is stronger than the population story. The city’s population is about 12,596 and has been essentially flat since the last census count of 12,764, so demand growth has to come from jobs, not migration.
Data USA shows the resident workforce concentrated in manufacturing (909 people), educational services (718), and health care (566). Per the Post and Courier, Freightliner and Nestlé each employ more than 900 in the county, a Dollar Tree distribution center employs about 600, and average county hourly wages run $20.18. That wage supports a $1,000-to-$1,300 rent without stretching a single earner. Cherokee Medical Center, a 125-bed acute care hospital in the Spartanburg Regional system, adds a steady health care employment base.
The newer catalysts are worth weighing. The Governor’s office announced a $150 million Nestlé investment in a Gaffney plant that has operated for four decades, and a reinvestment that size in an older facility signals durable, low-turnover employment. SCBiz reports First Solar leasing 1.3 million square feet for a $330 million plant expected to create 600 jobs. Six hundred jobs against a city of roughly 12,600 is a big potential renter pool. The lender, though, underwrites the rent an appraiser supports today, not the rent that plant might justify later. Treat it as a reason to hold a Gaffney rental with confidence, not as a number to put in the model.
Then there’s the cautionary side. Limestone University, founded in 1845, closed after trustees voted to shut it at the end of the academic year, per the SC Commission on Higher Education. It served roughly 1,600 to 1,800 students. As the Post and Courier reported, roughly $38 million in debt is stalling a campus sale. A downtown restaurant owner said she lost about 40% of her business. Skip any student-housing thesis here. Whatever premium that demand carried is gone, and no replacement institution has surfaced in the research.
East Gaffney, Downtown, and the Blacksburg Side
The submarket data in Gaffney is too thin to rank neighborhoods by numbers, so treat this as qualitative direction, not a scorecard.
Rents in the western part of Gaffney run higher than in the east, which fits the pattern of newer three-bedroom stock sitting on the growing side. East Gaffney, a census-designated place of 2,882 residents, is the lower-rent end. A stale $115,620 median price floats around for it, but it doesn’t match the other sources and shouldn’t anchor a refinance. Downtown and the historic residential streets have older housing and depend on a Limestone Street corridor that just lost its anchor. Buying there for cash flow is a hard sell, though a well-priced older house could work as a value-add if the appraisal supports the finished product.
The I-85 corridor near the Exit 92 outlet area drives retail and hospitality employment, which feeds rental demand indirectly. The county is divided by the Broad River. The Gaffney side has grown more while the Blacksburg side has struggled, per the Post and Courier, even though a new industrial park is planned near Blacksburg. For a refinance on a rental, favor the Gaffney side. (A $415 million industrial park announcement is a headline, not a rent roll.)
A note from the deal desk. In small, employer-driven markets like this one, the common friction point on cash-out files is the appraisal, not the borrower’s credit. Comps are sparse, value bands are wide, and a lender’s review often turns on whether the rent schedule and sales comps tell a consistent story. The cleaner files from a documentation standpoint tend to arrive with a signed lease, a payment history, and reserves shown clearly before the file goes in. Ownership seasoning is usually the easy part.
What the Proceeds Do Next
Cash-out proceeds are only as good as the next deal they fund, and in Gaffney the next deal has to be priced for coverage or the recycled capital just buys another sub-1.00 house.
The program box is straightforward. Cash-out is typically capped at 75% LTV, credit files generally start around a 620 floor with better positioning at higher tiers, reserves run about six months of PITIA on most files (higher on very large balances), and loan sizes go up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. The equity available depends on rent used for lender review, PITIA, reserves, and that 75% ceiling. It is not a guaranteed figure, and details are subject to lender overlays and program changes. Vesting the property in an LLC is common, subject to lender program eligibility. For the mechanics on that side, see Lendmire’s DSCR cash-out refinance page, and for the borrower-profile differences, it helps to consider the tradeoffs between conventional and DSCR financing.
The stronger play in Gaffney might be recycling proceeds into a below-median house or a small multifamily rather than a stabilized three-bedroom at market. Although a stabilized property holds its rent, it offers less room between price and appraisal. Investors chasing appreciation could argue the other way, but with flat values that argument takes patience. Investors weighing a specific property can reach out at 828-256-2183 for a scenario review. Verify current local rental rules, taxes, and insurance with qualified local professionals before committing to a plan.
DSCR vs. conventional financing
Two common ways to finance an investment property in Gaffney, SC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
Can a median-priced Gaffney house clear 1.00 on a cash-out?
Usually not at full leverage. A $180,000 house renting at $990 models around 0.9x once taxes and insurance are counted, using CapRateCity’s median figures. It clears when the basis is below median, the rent is toward the top of the three-bedroom listing range, or the investor takes lower leverage. Eligibility review depends on lender review.
How long does an investor have to own a Gaffney rental before pulling cash out?
Programs in the network typically look for about six months of ownership, measured from title recording. Flat local values mean the equity usually comes from a discounted purchase or renovation, so the seasoning clock matters less than the appraisal.
Did the Limestone University closure hurt Gaffney rental values?
It hurt downtown business, with one restaurant owner reporting roughly a 40% loss, and it removed student-housing demand. The research shows no clean number for its effect on house values, and appraisals depend on recent comparable sales. Keep any student premium out of the rent assumption.
Do the First Solar and Nestlé jobs let an investor underwrite higher rents?
Not directly. A lender relies on what an appraiser or lease supports today, and the plant is not yet reflected in rent data. The jobs make holding a Gaffney rental more appealing over time, but the rent used for program review has to be documented on its own.
Is a duplex realistic in Gaffney?
Yes, but the inventory is small. Roughly 13% of the housing stock is duplexes, converted homes, or small apartment buildings, so comps exist. Coverage on a duplex works when the price is modest, and asking prices in the mid-$300,000s and up tend to fall below 1.00 on these rents.
The Bottom Line on Gaffney Equity
Gaffney rewards the investor who bought at a discount and can prove the rent. It punishes the one who bought at median and hoped. A three-bedroom or a small multifamily with a clean lease can carry a refinance, while a median house at a $990 rent needs a different plan. Flat values mean no rescue from the market either way.
If you only take one thing from this piece, it’s this: in a flat market like Gaffney’s, a cash-out clears only where the price was low enough and the rent strong enough to cover the debt on the day you apply, because neither appreciation nor the new plant jobs will do that work for you.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow, Gaffney rental houses
3. University Herald, Limestone
7. Zumper, Gaffney rent research
8. NeighborhoodScout, Gaffney real estate
10. Resideline, Gaffney housing market
12. Post and Courier, Cherokee County growth
13. Spartanburg Regional, Cherokee Medical Center
14. SC Governor’s Office, Nestlé Gaffney expansion
15. SC Commission on Higher Education, Limestone University closure
16. 2025
17. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in South Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.