
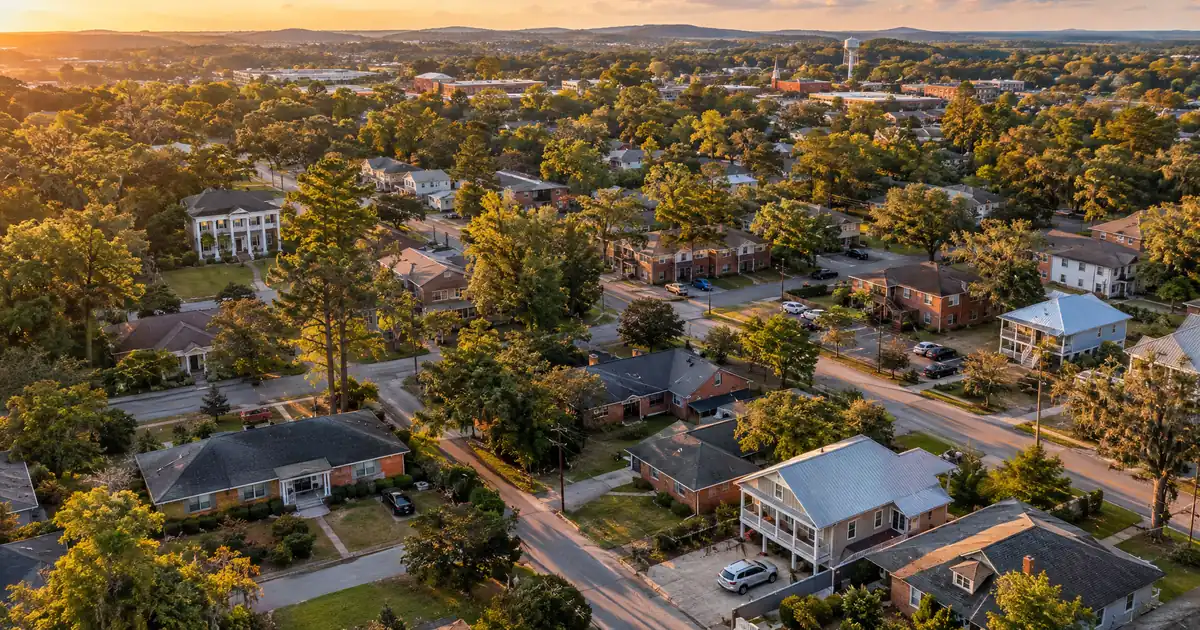
In Griffin, the appraisal sets the cash-out, and the rent roll only confirms it. Median prices are drifting lower while inventory builds, so the 75 percent loan-to-value ceiling tends to bind before the coverage ratio does. Investors sitting on older bungalows near downtown or the Wellstar corridor should size the refinance off a conservative value, not last year’s comp. Investors in Griffin, Georgia work with Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, to place DSCR financing through wholesale lenders reaching 41 markets, including D.C. Lendmire arranges the loan. Lenders review and approve it.
The Quick Read: A cash-out refinance on a Griffin, Georgia rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, but the appraisal sets the ceiling. With median prices softening and inventory rising, the 75 percent loan-to-value cap binds harder than the rent does.
DSCR Cash-Out Calculator
Run the cash-out numbers in Griffin, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Renters occupy 61 percent of Griffin households, per RentCafe.
- Single-family rents average $1,523 on Homes.com; duplex doors list far lower. Redfin shows a $215K median, down 6.3 percent year over year.
- Cash-out typically caps at 75 percent LTV after about six months of title seasoning.
- Older 1940s-to-1980s housing stock carries most of the workforce rental supply.
Griffin Market Snapshot
A quick read on the Griffin investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $725 and $700 rents (Homes.com multi-family) |
| University enrollment | 6,185 total (CollegeTuitionCompare) |
| Employment | 130 jobs (Area Development) |
The Older Core: Downtown, Third Ward, and the Bungalow Stock
The best cash-out candidates in Griffin are the low-basis older houses in and around the downtown core. Low basis means the appraised value stays modest, so a rent in the low $1,500s can still clear the coverage ratio at 75 percent LTV. The catch is that those same houses get the hardest appraisal scrutiny.
The Griffin Commercial Historic District covers 28 acres, with restaurants and retail concentrated along Taylor and Hill streets. Third Ward, just off downtown, is a neighborhood of ranch-style bungalows. No neighborhood-level rent or price series exists for either, so treat any per-street claim you read with suspicion. What is documented is the housing stock. The Homes.com local guide says many Griffin homes were built between the 1940s and 1980s, with new construction now starting to outnumber the older bungalows. That newer product is aimed at first-time owners, not renters, so it is not where rental comps will come from.
For an investor who bought one of these houses more than six months ago, the refinance question is simple. Does the appraiser credit the renovation, and does rent cover the new payment with taxes and insurance included? Both answers depend on the comp set. More on that below.
Why the Renter Pool Is Deep but Thin-Wallet
Griffin has a large renter base and modest incomes, which is the right profile for workforce rentals. RentCafe counts 5,881 renter-occupied households against 3,837 owner-occupied, a 61 percent renter share. Census Bureau QuickFacts, using five-year ACS data, puts the population at 23,761 and median household income at $43,632, against $89,724 for the Atlanta metro. Mean commute is 22.2 minutes.
Read that correctly. Tenants here are price-sensitive. Rent growth is capped by what a $43,632 household can carry, so a cash-out that only works on a rent push is a bad file.
RentCafe shows average rent at $1,346, up 3.2 percent over the past year, with 72 percent of rentals between $1,001 and $1,500. Its two-bedroom figure is $1,300 and its three-bedroom is $1,578. Homes.com puts median rent at $1,400, with single-family at $1,523, townhouses at $1,238, and condos at $1,300. Other portals publish figures that disagree, and one of them likely mixes in subsidized units. Rents in the low $1,300s is the defensible framing.
Demand Anchors That Actually Hold Tenants
Griffin’s demand comes from work, not campuses. The Georgia Department of Labor lists Caterpillar, Hoshizaki America, Walmart, the University of Georgia, and Wellstar Health System among Spalding County’s major employers. It publishes no headcounts, and older headcount documents are stale, so none are used here.
Two corridors follow from that list:
- South 8th Street, near Wellstar. Wellstar Spalding Medical Center sits at 601 South 8th Street. It added a 6,475-square-foot cancer center, per Wellstar, and runs an Internal Medicine residency program, which adds resident and nursing-trainee rental demand. No rent data exists for the corridor. The anchor is real; the numbers are not published.
- Highway 16 and The Lakes at Green Valley. Location Georgia describes a 570-acre mixed-use development on the Highway 16 corridor. Area Development reported a $38 million Ecopol plant expected to create 130 jobs there. That is industrial-worker demand, with Caterpillar and Hoshizaki in the same orbit.
Student housing is not the thesis. Southern Crescent Technical College reports 6,185 total students on one aggregator, but that figure is systemwide across campuses and includes 3,266 online students. The University of Georgia Griffin campus is an agricultural research site dating to 1888, not a dormitory market. Lenders underwriting a Griffin rental will not credit a student premium.
What Does the Coverage Math Look Like?
On modeled inputs, a Griffin single-family cash-out sits right around the 1.00x benchmark and moves sharply with the appraised value. These are illustrations, not market statistics, and every ratio below includes taxes and insurance in the monthly obligation. Most standard DSCR programs are built around a 1.00x minimum because rent covers the payment at that level, though exact eligibility depends on lender guidelines, credit, reserves, and property review.
Run the numbers on three cases, all at 75 percent LTV on a 30-year amortization:
1. A $215,000 appraised value with $1,523 rent. That is the Redfin median against the Homes.com single-family figure. Coverage lands around 1.1x.
2. The same value with $1,346 rent. That is the RentCafe average. Coverage drops to roughly 1.0x, right on the line.
3. A $275,900 appraised value with $1,523 rent. That is the Homes.com twelve-month median. Coverage falls into the low 0.9s.
The third case is the point. Same rent, higher value, lower ratio, because the loan amount scales with value while rent does not. When a sub-1.00 result shows up, the structures a lender may review include a sub-1.00 program, interest-only payment structuring, or a lower LTV. Each is subject to lender guidelines, credit approval, and property review. None is a given.
DSCR files in markets like this one typically look the same. Rent is documented cleanly by a lease and a rent schedule, and the coverage pencils on the modeled value. The file then stalls when the appraisal lands under the owner’s expectation and the loan amount has to shrink. The files that move cleanly enter review with a realistic value, a current insurance quote, and reserves already documented. Lendmire’s broker desk sees the value gap, not the rent, as the usual source of a re-trade.
Reserves. Six Months, Documented.
Reserves trip more Griffin files than investors expect, because cash-out proceeds do not count as the borrower’s reserves on most programs. Expect about six months of PITIA held in verified accounts, with the requirement stepping up toward nine months on loans above $1,500,000. A bank statement that shows the balance, in the borrower’s or entity’s name, is the clean version. A stale statement or a balance that came from the refinance itself is a preventable gap.
The other typical guidelines for a Griffin cash-out, all subject to lender program terms:
- Seasoning of about six months from title recording, evidenced by the settlement statement.
- Credit tiers starting at a 620 floor, with better terms generally available at 660, 680, and 700.
- Loan sizes up to $3,000,000 on standard programs.
Seasoning is the one that kills files that assume it away. A house bought and renovated recently, with a value bump the investor wants to pull out, has to wait out the recording date. How the cash-out mechanics work is laid out on Lendmire’s site.
Appreciation Versus Appraisal: The Tension
Griffin’s history says prices rose hard. The current data says the run has cooled, and the sources disagree. That is the honest read.
NeighborhoodScout reports 136.75 percent appreciation over ten years, about 9.00 percent a year. The page is dated, so treat it as history. Redfin shows a $215K median sale price for the last three months, down 6.3 percent year over year, even as price per square foot is $151, up 13.5 percent. The two can coexist. Smaller or lower-end homes sold, which pulls the median down while per-foot value holds. A local MLS-based report puts the Spalding County single-family median at $265,000, up 6 percent, but that is county data, not city data. Orchard shows a 30-day median of $265,000, down 11.6 percent.
Four sources, four answers. The practical point for cash-out is to underwrite to the low end of the range. Redfin also reports homes selling after 64 days on market against 52 a year earlier. Orchard shows months of supply at 9.98, up from 4.34. More inventory and slower sales give an appraiser more room to discount. A cash-out sized to the top of a price range is riskier than one sized to the median.
Duplexes: Stacking Helps Only When Basis Is Low
Duplex math in Griffin is not the single-family math doubled. Listed doors rent for less. A Homes.com duplex listing shows a renovated 4-bedroom, 2-bath building with units renting at $725 and $700. A byowner.com feed shows a multifamily rental at $900 and a 2-bed/1-bath at $1,025. These are single-listing asking rents, not market statistics.
The two doors on that Homes.com listing total $1,425. That is about what a single-family house brings in on its own. Stacking only pays when the purchase basis is low enough that two modest rents cover one loan with room left. Vacancy is also easier to absorb. One empty door leaves the other rent in place, where a vacant single-family house drops coverage to zero.
Inventory is thin. Homes.com shows 6 multi-family listings for sale, and Zillow shows 4 homes on its duplex and triplex page. Few comps means the appraiser may reach for a wide radius or older sales, and a converted duplex listed as single-family can complicate the rent-schedule treatment. Ask early how the lender will handle it. Price any duplex at modeled per-door rents in the $700 to $900 range, not the $1,523 single-family figure.
The Supply Question Near Downtown
New income-restricted housing is arriving downtown. The Griffin Daily News reports Parc at Solomon as a four-story building with 69 rental units, capped at 60 percent of area median income. A second project, Parc at Rosenwald, carries a total cost of $57 million. Delivery dates and lease-up status are unconfirmed.
Units priced for the same income band compete with older private bungalows and small duplexes. That could cap rent growth and stretch vacancy on the lowest-tier product near downtown. Stress-test vacancy there before counting on a rent bump to support a refinance. Verify current local rental rules, property taxes, and insurance costs with qualified local professionals before committing to any number.
What Happens to the Proceeds?
Cash-out proceeds are not a fixed figure. Equity available depends on the rent used for lender review, PITIA, reserves, and the 75 percent LTV ceiling, and on what the appraiser actually writes. An investor who overestimates the value plans a reinvestment that never funds.
The sound approach is to treat the proceeds as down-payment capital for the next Griffin or Atlanta-fringe purchase, sized only after the appraisal is in hand. Compare DSCR options before locking in a plan. Lendmire’s Georgia DSCR platform covers state-level program detail, and the team can be reached at 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Griffin, Georgia?
Qualification centers on the property’s rent against its full monthly obligation, with a typical 1.00x minimum. Lenders also review credit, reserves, seasoning, and the appraisal. Griffin’s rents in the low $1,300s mean the appraised value, not the rent, often decides whether the ratio clears. All of it is subject to lender guidelines and credit approval.
DSCR vs. conventional financing
Two common ways to finance an investment property in Griffin, GA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for a cash-out refinance on an investment property in Griffin, Georgia?
Typical guidelines are a 75 percent LTV ceiling, about six months of ownership measured from title recording, a 620 credit floor, and about six months of PITIA in reserves. Loan sizes run up to $3,000,000 on standard programs. Program terms vary by lender, so confirm current requirements before planning around them.
Can a LLC-owned Griffin rental be reviewed for DSCR financing?
Yes, subject to lender program eligibility. Lendmire arranges DSCR investor loans. Under most programs the review centers on the property’s rental income, with entity documents and the operating agreement part of the file.
Does a duplex improve coverage in Griffin?
Only when the basis is low. Listed duplex doors rent around $700 to $900, well under the $1,523 single-family figure, so two doors may total about what one house brings in. Vacancy risk is spread across two tenants, though, and that helps stability. Appraisal comps are thin, which adds review friction.
How much can a soft Griffin appraisal change a cash-out?
It can change it more than the rent does. At the same rent, moving the modeled value from $215,000 to $275,900 drops coverage from around 1.1x to the low 0.9s. A lower appraisal shrinks the loan amount, which can lift the ratio but cut the proceeds. Conservative value assumptions avoid re-trades.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. A 2025 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2026, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Appraisers in Griffin will tell you that the houses that hold value are the ones with clean rent records and sane comps, and the rest get marked to the soft end of the range.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. RentCafe
2. Homes.com
3. Redfin
4. Homes.com — Griffin GA Multi Family Homes for Sale
9. Georgia Department of Labor
10. Wellstar Spalding Medical Center
11. Wellstar
12. Location Georgia
13. Southern Crescent Technical College
14. University of Georgia Griffin campus
15. NeighborhoodScout — Griffin Real Estate
16. MLS-based report
17. Orchard
18. byowner.com
19. Zillow
21. 2025 Scotsman Guide Top Mortgage Workplace
22. Scotsman Guide — Top Workplaces 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.