
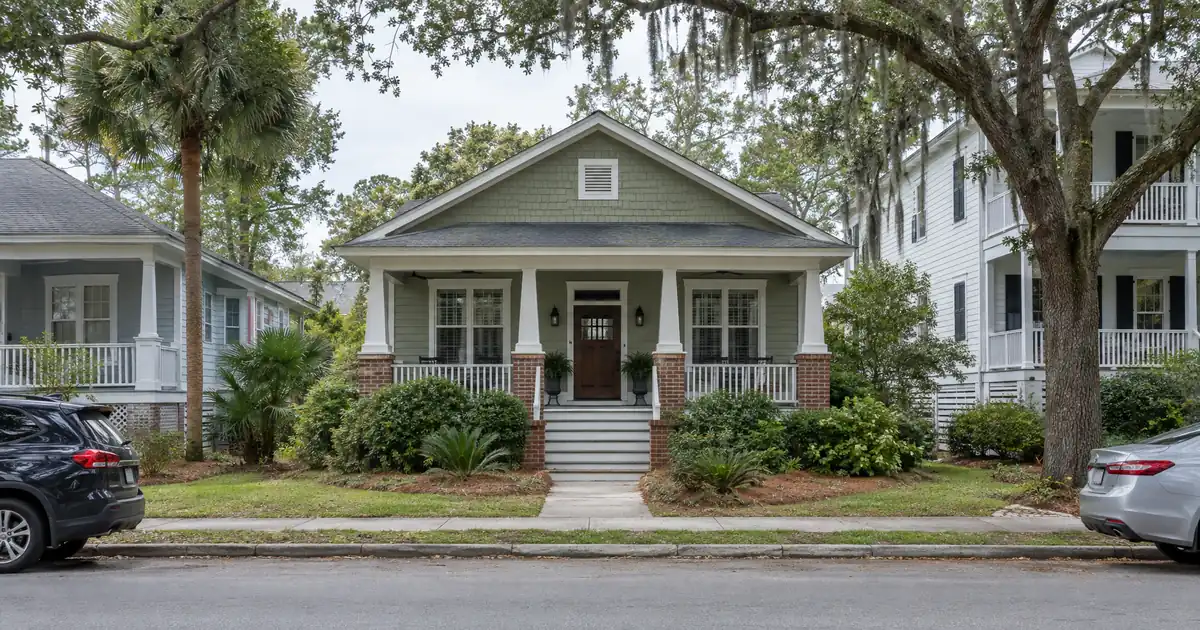
Per MoveWithMomentum, a brokerage market page, St. Simons carried 294 homes for sale against 456 sales over the trailing twelve months. That works out to 7.7 months of supply, past the six-month line that separates buyer’s markets from balanced ones. For an investor sitting on an island rental and eyeing a cash-out, the number matters for one reason: appraisers price off recent closings, and those closings are soft.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. Through Lendmire’s DSCR program footprint — 41 markets, including Washington, D.C. — lenders may review qualifying rental income subject to program guidelines for St Simons Island, Georgia investors. This piece covers the extraction side only: what a cash-out looks like on an island where appreciation has stalled and the rent-to-value ratio is thin.
DSCR Cash-Out Calculator
Run the cash-out numbers in St Simons Island, GA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read: A cash-out refinance on a St Simons Island rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds sized by appraised value, the 75 percent LTV ceiling, and reserves rather than by any promised cash figure.
- Mid-island condos near Frederica and Demere Roads offer the most plausible coverage on the island.
- Island-average single-family typically lands well under 1.00x on modeled rent and full PITIA.
- Cash-out generally requires about 6 months of ownership from title recording.
- Buyer’s-market supply means appraisals can come in noisy, so proceeds are never a given.
St Simons Island Market Snapshot
A quick read on the St Simons Island investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $664K median (Redfin, St. Simons housing) |
| University enrollment | ~3,700 students (College of Coastal Georgia) |
| Employment | ~1,200 federal + ~1,866 contract employees (Federal Law Enforcement) |
Where the Collateral Works: Mid-Island Condos and Townhomes
Mid-island is the strongest cash-out collateral on St. Simons. The Frederica Road and Demere Road corridor, along with Sea Palms, holds the lowest price basis on the island, and lower basis is what lifts a coverage ratio toward 1.00x.
The evidence sits in recent condo sales. According to Redfin’s St. Simons market data, a two-bedroom condo near Redfern Village sold at $385,000, and a three-bedroom, two-bath unit on Blair Road sold at $360,000. Compare that with the island-wide average home value of $681,128, per Zillow’s home value index. Redfin’s median runs lower at $664K, a difference in methodology, so treat the island’s typical price as a $660K-to-$680K band rather than a point.
Run the numbers on a condo bought near $385,000, refinanced at 75 percent LTV. Assume a modeled rent of $2,600 (a modeled figure, not a sourced comp). Against full PITIA, including taxes and insurance, coverage lands around 1.1x before HOA dues. HOA dues then decide everything. Add them and the number slides toward the 1.00x line. Not a comfortable margin.
The mid-island housing stock is mostly residential subdivisions (Hamilton Landing, Wymberly, Devonwood) plus condo complexes like Shadow Brooke Village and Barnes Plantation. No published neighborhood-level median rent exists for any of them. Pull fresh rent comps before underwriting. Any coverage figure here is a model, not a market fact.
Single-Family at Island Prices: The Math Breaks
Single-family at island-average value struggles to clear 1.00x. Sample three-bedroom asking rents on Zillow’s rental listings run $2,850 to $3,500 a month, and Repit, an aggregator, puts the typical rent near $2,663. Against a $680K-class basis, that is roughly 0.4 to 0.5 percent rent-to-value. That ratio is a listing-based estimate, not a published statistic.
Modeled at 75 percent LTV on a $681,000 house with $3,200 of rent, coverage including taxes and insurance comes out near 0.7x to 0.8x. A sub-1.00x file is not automatically dead. A lender may review a sub-1.00 program, an interest-only structure, or lower leverage, and each usually comes with tighter pricing, more reserves, or more cash left in the deal. Whether any of those apply is a matter of lender guidelines, credit approval, and property review. Investors who want the mechanics can read the guide “What Is a DSCR Loan”.
The stronger play might be the condo over the house for cash-out purposes, though an investor holding a paid-down house with real equity could argue for taking the lower leverage instead. It’s a genuine toss-up. The house gives more collateral cushion, and the condo gives the better ratio.
Skip the Luxury Enclaves
Hampton Point, Hampton Plantation, and the St. Simons Island Club skew owner-occupant, and the price basis makes coverage math unworkable. Coastal Georgia Real Estate Associates, citing Redfin, shows the Club at a $1,495,000 median sale price on only three closings, an 89.7 percent sale-to-list ratio, and 77 days on market. Island-wide, the same source shows a $679,000 median, 101 days on market, and sales roughly 5 percent below list.
Three closings is not a comp set. An appraiser leaning on that sample has wide error bars in both directions, which is the last thing a 75 percent LTV cash-out needs. The sub-$700K workforce-adjacent stock, including condos and townhomes along Sea Island Road, has deeper comps and is the more defensible collateral.
What Seasoning Means With No Appreciation Tailwind
Cash-out proceeds here depend on the appraisal and the original basis, not on price momentum. Typical program guidance calls for about 6 months of ownership measured from title recording, and the ceiling on a cash-out is 75 percent LTV. Cash-out is never capped at the purchase figure, but on this island the purchase price plus documented improvements is the safest underwriting anchor.
The market’s own data explains why. Zillow shows a modest one-year gain. Redfin shows a year-over-year decline. MoveWithMomentum shows a slight decline on a twelve-month median. When three credible sources disagree on direction, the honest read is flat. Add sold homes that typically close somewhat below list, with time to go under contract varying by property and price tier, and the island is a place to buy below market, not to assume the refinance appraisal will bail out a full-price entry.
The listing mix matters too. The same dataset shows 195 houses, 72 condos, and 26 townhomes for sale, so condos and townhomes are about a third of current inventory. That gives appraisers a workable, though not deep, pool for the mid-island tier.
Under the standard program parameters, a file also generally needs about 6 months of PITIA in reserves, a 620 credit floor, and a 1.00x minimum coverage ratio. The reserve requirement steps up for balances above $1,500,000. Equity available is a function of rent used for lender review, PITIA, reserves, and the LTV cap. It is not a guaranteed figure. For the full sequence, see the guide “The Refi Options” and the investor refinance breakdown.
DSCR files in markets like this one typically look the same on paper: high basis, modest rent, and a coverage number that sits right around the 1.00x benchmark. The files that move cleanly usually carry a recent, well-documented lease, a condo with a clean HOA budget and warrantable project, and an investor comfortable taking a lower LTV to protect the ratio. The files that stall are the ones that assumed the appraisal would do the work.
Who Rents Here: The Demand Case
The tenant pool leans on employment anchors more than on the island itself. The Federal Law Enforcement Training Centers campus in Glynco hosts about 68,000 students a year from 105 federal agencies, with roughly 3,000 on campus at any time, per the Washington Examiner. FLETC itself reported nearly 1,200 federal employees and about 1,866 contract employees at its 50th-anniversary milestone (an older figure). Sea Palms listings explicitly pitch units toward FLETC-related stays, and the campus pages show trainees taking recreation trips to the St. Simons Pier.
Healthcare adds year-round demand. Southeast Georgia Health System lists over 3,000 team members, and the Golden Isles Development Authority describes a 316-bed hospital with more than 300 physicians serving six counties. The College of Coastal Georgia adds a smaller layer, with U.S. News reporting 3,609 undergraduates.
The ceiling is wages. The Development Authority, citing Georgia Department of Labor data, notes that accommodation and food services and retail trade are Glynn County’s largest employment industries. Rents that stretch those incomes will sit vacant, so underwrite to what a hospitality or federal-training paycheck supports, not to the $3,500 asking-rent outliers.
One more signal. Sea Island Company won county approval for an 84-unit, four-story employee multifamily project on Sea Island Road, per First Coast News. A major employer building its own staff housing confirms workforce demand outruns supply. It also means competing units near that corridor, and completion status was not confirmed in the research, so check before buying nearby.
Turning Proceeds Into the Next Deal
The proceeds only matter if they buy something that covers better than the asset they came from. On this island that argues for redeploying off-island, where workforce single-family and small multifamily likely show stronger rent-to-value. That is an inference; the research found no sourced duplex, triplex, or fourplex data on the island itself, and small multi-unit inventory looks scarce. Nothing here supports claiming multi-unit strength.
Loan sizes generally run up to $3,000,000 on standard programs, with smaller balances routed through select lenders. For a structure walk-through, investors can talk through the numbers or reach the brokerage at 828-256-2183. The broader state framework is on the page for DSCR loans in Georgia.
Verify current local rental rules, taxes, and insurance with qualified local professionals before committing. That covers the regulatory side once; the rest of this analysis stays on coverage and collateral.
Frequently Asked Questions
How do you qualify for a DSCR loan in St Simons Island?
The file is reviewed on the property’s rent against its full PITIA, with a 1.00x baseline common across programs. Lenders also look at credit (a 620 floor on typical tiers), reserves near 6 months of PITIA, and property type. Exact eligibility depends on lender guidelines, credit profile, and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in St Simons Island, GA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in St Simons Island, Georgia?
Typical guidance for a cash-out includes about 6 months of ownership, a 75 percent LTV ceiling, a 1.00x minimum coverage ratio, and reserves near 6 months. Manufactured homes, log homes, and barndominiums fall outside these programs. Qualification is subject to lender overlays and underwriting.
How does rental income affect DSCR refinance eligibility in St Simons Island?
rent used for lender review is the numerator in the coverage ratio, so a documented lease or market-rent appraisal directly sizes what a lender may review. Lendmire arranges DSCR investor loans and the program is built around rental income rather than personal income paperwork, subject to lender guidelines.
Do mid-island condos or island houses work better for a cash-out?
Condos and townhomes near Frederica and Demere Roads usually give the better coverage ratio because of the lower basis, while houses give more equity cushion. HOA dues on the condo side are the deciding variable. Model both before choosing.
Does a buyer’s market hurt a cash-out appraisal?
It can hurt the appraisal. With plenty of supply on the market and homes selling below list, appraisers work from softer comps, and thin luxury samples make it worse. Underwrite to purchase price plus documented improvements rather than assumed appreciation.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a top-ranked workplace in 2025, Lendmire places loans through wholesale investor lenders and is not a direct lender.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. MoveWithMomentum, St. Simons listings
2. Redfin, St. Simons housing market
4. FLETC
5. Zillow Home Value Index, Saint Simons Island
7. Repit
8. Coastal Georgia Real Estate Associates
10. Southeast Georgia Health System
11. Golden Isles Development Authority, Southeast Georgia Health System
12. goldenislesdev.com — Wages and Employment Data Glynn County Georgia
13. First Coast News
14. a 2026 Scotsman Guide Top Mortgage Workplace
15. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property on St. Simons Island · Luxury Rental DSCR Loans In St. Simons Island · Cash Out Refinance Investment Property Toccoa Georgia
Guides: Investment Property Cash-Out Refinance in Georgia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.