
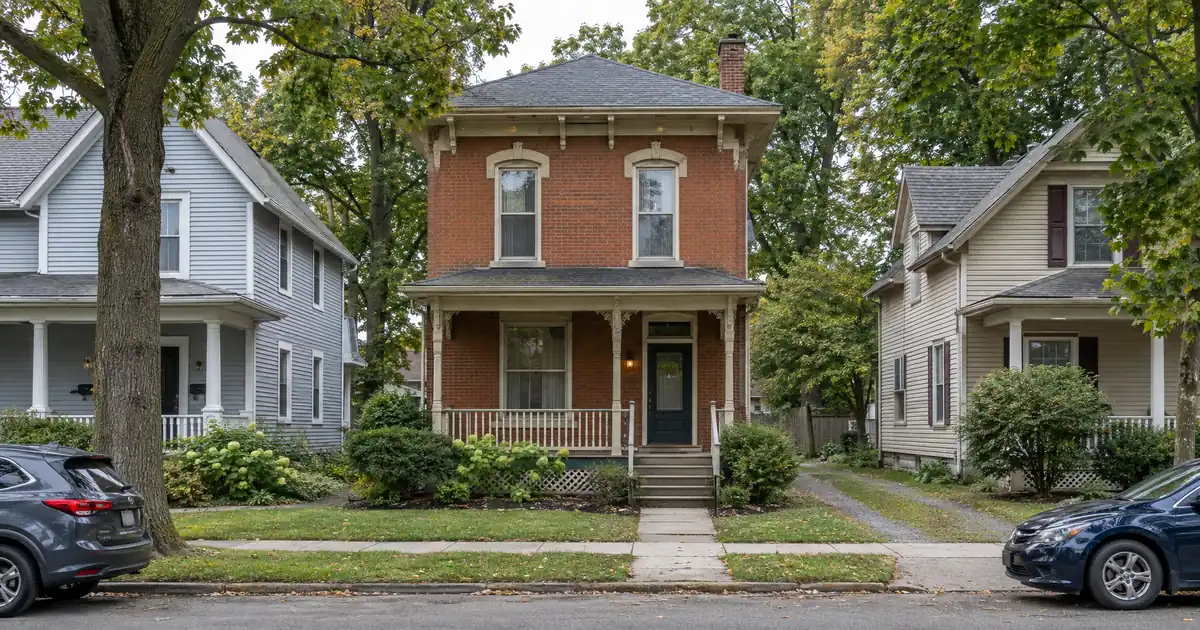
Picture an investor holding a single-family rental in the 46516 ZIP, bought years ago at a price that now looks cheap against a $153,400 ZIP-level home value. The loan balance has shrunk. The house has not. The equity is real, but it sits idle. The question is how much of it can be pulled out, and what the next purchase has to look like to justify the risk.
The Quick Read: A DSCR cash-out refinance in Elkhart, Indiana is underwritten primarily on the property’s rental income measured against its full monthly obligation, so a seasoned rental is judged on its own income. Eligibility is reviewed by the lender and depends on appraised value, a 75 percent loan-to-value ceiling, reserves and rent used for lender review.
DSCR Cash-Out Calculator
Run the cash-out numbers in Elkhart, IN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Modeled coverage on typical workforce rentals lands near 1.2x at the 75 percent cap, including taxes and insurance.
- Seasoning runs about six months from title recording, so recent buyers wait.
- The city’s rent-to-price ratio sits near 0.7 percent, per the research below.
- Tenant income leans on RV manufacturing, which is contracting.
- Manufactured homes fall outside these programs, and they are nearly 10 percent of local housing stock.
Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker offering DSCR lending in 40 states and Washington, D.C. (41 markets total), arranges these refinances through wholesale investor lenders. This report covers how the equity math works in Elkhart and where the demand risk sits. It does not cover purchase mechanics. For those, see Lendmire’s Indiana DSCR loan programs.
Elkhart Market Snapshot
A quick read on the Elkhart investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median age 34.6 (ZIP-Codes.com) |
| Employment | ~35,000 jobs (U.S. Dept. of the Interior) |
| Vacancy | 9% (AffordableHousingOnline Elkhart) |
What the 75 Percent Cap Leaves You
Cash-out proceeds in Elkhart are set by three limits: a 75 percent loan-to-value ceiling, rent that covers the new debt service, and reserves of about six months of the full obligation. Appreciation helps, but the ceiling and the coverage number decide how much comes out.
Start with value. Redfin reports a city median sale price of $183,500, up 6.7 percent year over year, with homes averaging 21 days on market. The sample was thin, only 32 sales in the month. Treat it as direction, not a verdict. The county figure is far higher, $269K per Redfin’s county page, but that includes Goshen, Middlebury and the lake areas. It overstates what an Elkhart city rental is worth.
Now the mechanics. Say you own a rental appraised near the city median, with a payoff balance equal to 60 percent of that value. The 75 percent ceiling leaves a 15-percent-of-value gap before payoff costs, reserves and fees. That gap is the ceiling, not a promise. Appraisals can land short, and the lender sets final proceeds.
Seasoning matters here. Most programs look for about six months of ownership measured from title recording. A buyer who just finished a rehab and wants to recycle capital immediately will have to wait. Plan the calendar before the contract, not after.
One more point most investors skip: cash-out raises the loan, so it lowers the coverage number. Run it as a modeled assumption. Take a 3-bedroom rent of $1,314, per RentCafe, against a $183,500 value. At a 60 percent balance, coverage including taxes and insurance runs around 1.4x. Push the loan to the full 75 percent and it drops to about 1.2x. Still above the 1.00 baseline many programs use, but the cushion is gone. Exact eligibility depends on lender guidelines, credit profile, reserves and property review. The guide “What Is a DSCR Loan” covers the formula in full.
Where the Coverage Math Holds (and Where It Doesn’t)
Elkhart’s three ZIP codes produce very different coverage profiles on modeled numbers. The 46514 ZIP shows the widest cushion on paper, 46516 clears the baseline, and 46517 dips just under 1.00. The data is thin, so these are screening figures, not underwriting rents.
The table uses ZIP-level median gross rent from City-Data paired with the best value figure available for each ZIP. The value bases differ: asking prices for two ZIPs, a home-value estimate for the third. Gross rent also includes utilities, which overstates what an owner collects. Coverage is modeled at 75 percent LTV, including taxes and insurance, rounded down.
| ZIP | Median gross rent | Value basis | Modeled coverage |
|---|---|---|---|
| 46514 | $1,157 | $126,544 asking | 1.4x+ |
| 46516 | $1,056 | $153,400 value | About 1.15x |
| 46517 | $975 | $171,393 asking | Just under 1.00x |
Sources: City-Data for 46516 and 46517; ZIP-Codes.com for the 46516 value.
Two cautions. First, 46514’s pretty number sits on a small balance. Smaller loans route through select lenders in the network, not the standard programs. Second, 46517 below 1.00 is not a dead end on its face. A sub-1.00 program, an interest-only structure or a lower loan amount are options a lender may review, subject to credit approval and property review. None is a given.
Beyond ZIP-level data, the research found no reliable neighborhood-level price or rent set for Elkhart, so ranking submarkets by yield would be guesswork. What can be said is qualitative. Downtown and the River District are the redevelopment story. The north side has green space and toll-road access. Corridors along East Bristol Street and the US-33 side pull workers who commute toward the RV plants. All draw the same tenant: someone employed in manufacturing or its supply chain.
The RV Question
Elkhart’s tenant base depends on one cyclical industry, and that industry is contracting. Cash-out underwriting here should assume rent holds but cannot assume it climbs. Stress the vacancy line before borrowing against the property.
The concentration is hard to overstate. The Herald Bulletin reports that over 80 percent of U.S. RVs are built in Elkhart County and the surrounding area. A dated county employer list from the Bradley Company put Thor Industries at 13,622 workers and Forest River at 10,000, with Lippert Components at 7,500. Those are county-wide counts from an older list, not current city payrolls. The U.S. Department of the Interior once pegged the county industry’s economic impact at $14.5 billion and nearly 35,000 jobs. Read that as a historical benchmark.
The current signals are softer. BLS data as reported by IndyStar and Hoodline shows the metro unemployment rate rising to 3.8 percent in June from 2.7 percent in April. Nonfarm jobs fell from 133,600 to 130,300 over a two-month stretch. Forest River is closing a plant in Bristol and cutting 105 jobs. This is secondary reporting, so weigh it as such.
A reasonable reading: the rents that make the coverage ratio work are paid by people whose hours can be cut. Rent per unit is not falling in the data. RentCafe shows the average at $1,165, up 5.83 percent, and Zumper shows $1,144, up 9 percent. But RentCafe covers buildings with 50 or more units only. Single-family and duplex rents may differ.
On vacancy, sources disagree. AffordableHousingOnline reports a 9 percent rental vacancy rate for the city against 6 percent for the county, and the aggregators do not name their data vintage. A vacancy allowance of 8 to 10 percent is more defensible than a thin one. A lender may apply its own factors regardless.
The Lendmire deal desk sees a recurring pattern in single-industry manufacturing markets like this one. Coverage ratios that pencil on current rent often get tested on lease terms and the appraiser’s rent schedule, not on headline averages. Files with in-place leases at or near market rent, and reserves that clearly exceed the minimum, tend to be the cleaner ones. Thin files usually have a vacant unit or a rent assumption nobody can document.
The Tenant Base Beyond Assembly Lines
Elkhart is not a college rental market. Ivy Tech’s local campus is an extension of the South Bend campus with a Goshen address, and Niche lists 2,762 full-time and 5,454 part-time undergraduates for the combined institution. That is a commuter student body, not a rental engine.
Healthcare is the better counterweight. Elkhart General Hospital, part of Beacon Health System, lists 357 licensed beds, over 300 physicians and nearly 2,000 employees on a page that is several years old, so treat the headcounts as approximate. Hospital employment does not follow RV production schedules. Rentals within reach of the campus are a reasonable place to look for that tenant pool, though no rent data supports a premium.
Then there is supply. The Indiana Realtors’ housing shortage analysis says the St. Joseph-Elkhart region needs 10,145 units and has a 166 percent permit gap. That favors rents and appraisals. The same report calls the region the only one with negative net migration since 2020, losing over 12,000 domestic residents while about 9,000 international arrivals partly offset the loss. It describes the demographic foundation as more fragile than the headline numbers suggest. Regional, not city-specific. The takeaway is simple: supply shortage supports value, but out-migration argues against underwriting a steep price run-up. Use conservative appraisal assumptions.
Local reinvestment is modest but real. WNDU reports a $1.5 million READI grant for the Freight Street Initiative in the historic railroad district, with about 100 housing units possible and construction still ahead. Nice for downtown. Not a reason to adjust a rent assumption today.
Duplexes: Thin Comps, Wide Prices
Small multifamily fits Elkhart’s price point, but the stock is thin. Duplex and small-building comps exist, and appraisers on a cash-out may have to reach for them.
NeighborhoodScout puts single-family detached homes at about 53 percent of units, duplexes and small buildings at 10.41 percent and large apartment complexes at 25.04 percent. Mobile homes are 9.75 percent. Manufactured homes fall outside Lendmire’s network DSCR programs, so those units cannot be used as collateral for this strategy.
Two-family pricing is all over the map. The sensible read is that rent per dollar of price depends on the specific building, so each unit’s actual rent should be underwritten rather than assuming a duplex beats a house.
The rent bands help. Point2Homes says 60.92 percent of rentals fall in the $1,000 to $1,500 range and 2-bedrooms are the largest share at 42 percent. HUD Fair Market Rent for the city runs from $968 to $1,581 by unit size. A 2-bedroom per side fits the deepest part of the market. The HUD housing market profile adds a historical note: buildings with four or fewer units made up slightly more than half of the metro’s rental units.
(For context on why the structure differs from a conventional refinance, see conventional vs DSCR on investor loans.)
Turning Proceeds Into the Next Deal
Equity extraction only works if the capital goes somewhere with better return than the cost of holding it. With rent-to-price near 0.7 percent, an illustrative figure from RentCafe rents against the Redfin median, Elkhart is a cash-flow market, not an appreciation play. The honest comparison is between redeploying here and redeploying somewhere with less single-industry exposure.
That is a genuine toss-up. Staying local means familiar comps and cheap entry. Going elsewhere diversifies tenant income. An investor with two or three Elkhart rentals already may reasonably prefer the second path.
Whichever route, the property being refinanced has to carry the new loan on its own. The cash-out refinance walkthrough and the refinance pathway for investor properties cover structure and sequencing. Investors weighing a scenario can get a DSCR quote or call 828-256-2183.
One reminder. Investors should verify current local rental rules, taxes and insurance with qualified local professionals before borrowing.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Elkhart?
Qualification centers on the property’s rent against its full monthly obligation, a seasoning period of about six months, reserves of roughly six months and a credit score that typically starts at a 620 floor. The loan is capped at 75 percent of appraised value. Final eligibility depends on lender guidelines, credit approval and property review.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Elkhart, IN, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Elkhart, Indiana?
The property needs to be an eligible type, such as a single-family home, duplex or small multifamily. Manufactured homes, log homes and barndominiums are excluded. Programs generally look for coverage at or above 1.00, with rent used for lender review supported by a lease or appraiser’s rent schedule. Some scenarios below 1.00 may be reviewed, usually with compensating factors, lower leverage or different pricing.
Does the RV industry slowdown change how a lender views an Elkhart rental?
The DSCR formula itself looks at the property, not the tenant’s employer. But lender conservatism tends to show up in rent documentation, vacancy treatment and reserve expectations. Investors should assume the appraiser’s rent figure, not the owner’s best-case figure, drives the coverage number.
Can a small Elkhart balance still be financed?
Programs run up to $3,000,000 on standard terms, and smaller balances route through select lenders in the network. With 46514 asking prices near $126,544 and 46516 values near $153,400, loans in this market are often small. Ask early which lender fits the loan size.
How does rental income affect DSCR refinance eligibility in Elkhart?
Rental income is the primary qualifier, measured against the full monthly obligation including taxes and insurance. Lendmire is a non-QM DSCR mortgage broker (NMLS# 2371349) that arranges investor loans across 41 markets, and select programs it works with use a 1.00 coverage floor, subject to lender guidelines. Higher coverage generally improves the file.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349), a non-QM mortgage broker serving investors in 41 markets including Washington, D.C., helps structure DSCR scenarios commonly evaluated around a property’s rental income rather than personal income paperwork, subject to lender guidelines. Recognized as a 2025 Scotsman Guide Top Workplace and a top-ranked workplace in 2026, Lendmire places loans through wholesale investor lenders and is not a direct lender. See the 2026 Top Workplace recognition announcement for details.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. $153,400 ZIP-level home value
2. U.S. Department of the Interior
4. Redfin: Elkhart, IN Housing Market
5. $269K per Redfin’s county page
6. RentCafe: Elkhart Average Rent
8. 46516
9. 46517
10. Herald Bulletin: Indiana RV Industry Tariff Story
11. Bradley Company
12. Hoodline: Elkhart County RV Plant Closure
13. Zumper
14. an extension of the South Bend campus
15. Niche
16. beaconhealthsystem.org — LOCATION ELKHART GENERAL HOSPITAL
17. Indiana Realtors: Facing Up to Indiana’s Housing Shortage
18. WNDU
20. Point2Homes
21. HUD PD&R: Elkhart-Goshen Housing Market Profile
22. a 2025 Scotsman Guide Top Workplace
23. Scotsman Guide — Top Workplaces 2026
24. the 2026 Top Workplace recognition announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Elkhart, IN · Investment Property Cash-Out Refinance in Indiana
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.