
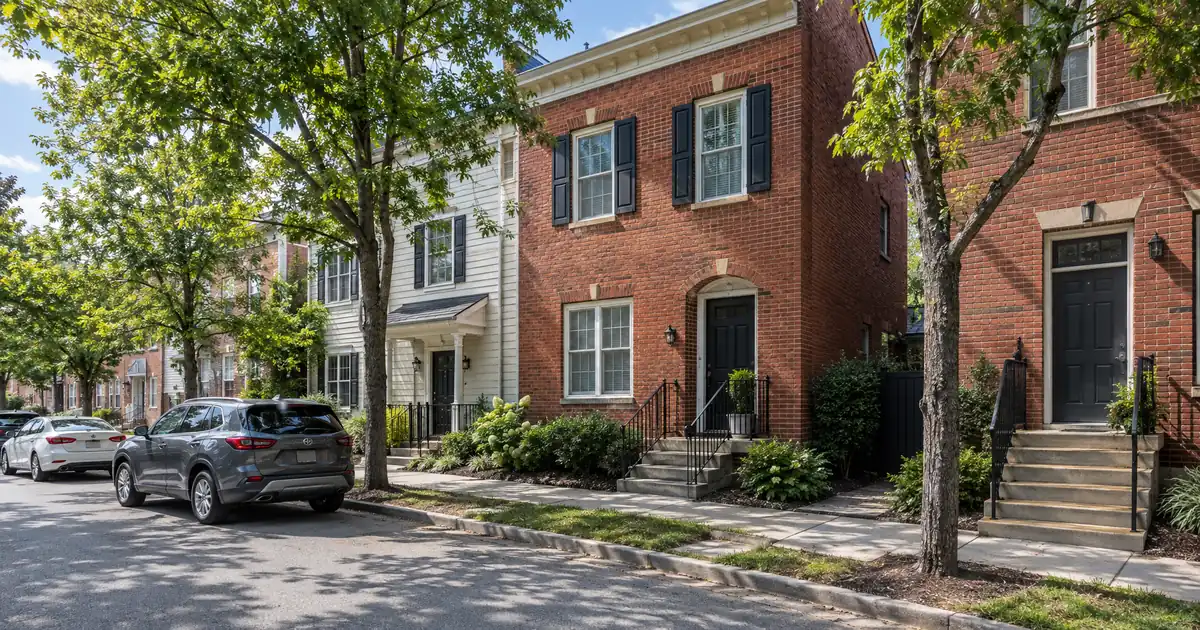
Picture a townhome near Wildhorse Village that you bought a few years ago. It’s worth more today, but the rent isn’t keeping pace with the price. That gap defines Chesterfield. Per ApartmentFinder, three-bedroom rents in the city average about $2,668 a month, while Redfin puts the median sale price near $595K. Equity is plentiful here. Rental coverage is the constraint. Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, helps arrange DSCR financing for Chesterfield, Missouri investors through wholesale and investor-lending channels across 41 markets, including Washington, D.C.
DSCR Cash-Out Calculator
Run the cash-out numbers in Chesterfield, MO
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance in Chesterfield, Missouri is underwritten primarily on the property’s rental income measured against its full monthly obligation, not the borrower’s paycheck, and it draws equity from a rental you already own, capped at 75 percent of appraised value, subject to lender guidelines.
- Median sale price in Chesterfield sits well above what many rental markets see, so rent-to-value runs thin.
- Entry-tier closings, at the lower end of the local price range, are where coverage is most attainable.
- Only a small share of the housing stock is duplexes or small apartment buildings, so most rentals are single-family houses.
- Full-leverage cash-outs on houses often model below 1.00. Lower leverage fixes that.
Chesterfield Market Snapshot
A quick read on the Chesterfield investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $1,703 gross (City-Data Chesterfield) |
| University enrollment | Parkway 17,000 students (Livability Major Employers) |
| Employment | St. luke’s 3,400 staff (Livability Major Employers) |
Where the Equity Sits (and Where the Coverage Doesn’t)
Chesterfield builds equity easily, but rent doesn’t scale with price. The city’s housing stock is high-value and owner-occupied. RentCafe counts 4,464 renter households (22 percent) against 16,240 owner households (78 percent), and NeighborhoodScout reports that single-family detached homes make up 63.83 percent of units.
Price sources disagree, so a note on method. This article uses Redfin’s $595K median as the canonical figure. Resideline, which tracks 381 closings, lands higher at a $622,000 median, with the middle half of sales between $449,000 and $790,000. Zillow’s typical-value index reads lower, near $498,561, because it measures a different thing. Appreciation readings range from flat to double-digit depending on the source. Underwrite a cash-out on appraised value near today’s level, not on a hoped-for gain.
Rent doesn’t climb in step with that price ladder. Recent closings in the 63017 ZIP, per Redfin, include three-bedroom homes at $420,000 and $445,000, against larger homes at $720,000 to $799,900. A three-bedroom in the $2,250–$2,800 rent range against a $622,000 median implies roughly 0.35–0.4 percent monthly rent-to-value. That ratio is Lendmire Research’s own arithmetic across two sources, not a published figure.
The takeaway: the sub-$460K tier is where DSCR coverage is realistic. The $700K-plus homes are appreciation holdings, and they’ll need a much lower loan-to-value to qualify.
Run the Numbers on a Chesterfield Cash-Out
At full 75 percent LTV, most Chesterfield houses model below 1.00. Lower leverage is what gets the number over the line. The standard benchmark is a 1.00 minimum DSCR (rent used for lender review against full PITIA: principal, interest, taxes, and insurance), though exact eligibility depends on lender guidelines, credit, and reserves.
These are modeled assumptions, not sourced market facts. Each includes taxes and insurance at Missouri-average loadings.
- Entry-tier house. Say you own a three-bedroom valued at $450,000 that rents for a modeled $2,500. At 75 percent LTV, coverage lands around 0.9x. Drop to roughly 60 percent LTV and it moves to just over 1.0x.
- Median-priced house. Take a $622,000 home renting for a modeled $2,700. Even at 75 percent LTV the ratio sits in the low 0.7s. Skip it unless you’re prepared to bring the balance way down.
Sub-1.00 files aren’t dead ends. A lender may review sub-1.00 programs, interest-only structures, or reduced leverage, each with its own compensating factors and pricing. Qualification stays subject to lender guidelines, credit approval, and property review. The tradeoff is simple: less cash out per property in exchange for a file that clears.
Other parameters, stated as typical guidance: cash-out generally requires about six months of ownership measured from title recording, credit tiers begin at a 620 floor, and reserves run about six months of PITIA. Equity available is never a guaranteed figure. The cash-out mechanics and the DSCR fundamentals cover the full framework.
Appraisals Here Have a Wrinkle
Comps are plentiful, but investor-grade ones are thin. Houzeo shows homes selling in about 27 days, with 1.2 months of supply and sales near 99.88 percent of asking. Redfin’s own three-month read is 14 days on market, up from 8 the year before. Low supply and near-asking closings support appraisals.
The catch: Resideline notes Missouri is a non-disclosure state, so sale prices aren’t public record. Appraisers lean on MLS data, and most Chesterfield sales are owner-occupant deals. An appraiser who knows West County matters more here than in a disclosure state.
(One practitioner habit worth copying: pull your own MLS comps before the appraisal is ordered, so nothing surprises you on value.)
What Actually Fits a DSCR Cash-Out
Condos, townhomes, and older attached stock carry the best rent-to-value. The Apartments.com condo page lists average condo rent at $1,735 a month. HOA dues reduce coverage, so factor them into the full obligation.
Small multifamily is the scarce prize. Homes.com shows just 14 multi-family listings, priced from $339,000 to $748,000, with no unit counts or rents broken out. If you already own a duplex or fourplex here, you’re holding rare product. Coverage depends on in-place rents and unit count, so it has to be underwritten one property at a time.
Village Green and West County are the city’s more affordable pockets, per Apartments.com, with one-bedroom averages near $1,530 and $1,540 respectively. Entry-level attached stock like this tends to cash-flow better than the big houses. The city’s broader rent picture is a spread: $1,423 average in one snapshot, $1,703 median gross rent per City-Data, and higher for new-build product. Sources differ by methodology (asking versus Census gross rent versus new construction).
Ineligible for these programs: manufactured homes, log homes, and barndominiums.
Downtown Chesterfield: Supply Risk or Demand Engine?
This one’s a genuine toss-up. STLPR reports that The Staenberg Group’s Downtown Chesterfield plans about 2,700 residential units on a 117-acre former mall site, backed by up to $352 million in tax increment financing. The developer targeted roughly 1,000 units opening by the end of the decade.
For an owner pulling equity now, that cuts both ways. New Class A supply will compete with older rentals once it’s delivered, and asking rents at nearby older stock could soften. But a walkable urban core with retail, dining, and office space also strengthens the location story for everything within a short drive. No source quantifies the net effect. Treat it as a reason to refinance while your rent roll is stable, not to bet on rent growth.
Demand Anchors Behind the Rents
Tenant demand rests on employment, not speculation. Per Livability, St. Luke’s Hospital (493 beds) and the Parkway School District are among the city’s largest employers. Dierbergs Markets is headquartered in Chesterfield, and Logan University adds a graduate-heavy student body of roughly 1,400. The economy also leans on corporate offices, agricultural-science R&D, and financial services. Employer counts in the Livability article are dated, so read them as directional. The city sits about 25 miles west of St. Louis with access to Interstate 64 and Route 340.
What Lendmire’s Deal Desk Tends to See
In high-price, thin-rent suburbs like this one, the common friction point is a borrower who sized the cash-out to the appraisal instead of the coverage ratio. The cleaner files tend to arrive with a signed lease, a current HOA statement where applicable, and leverage already dialed to where the number clears. Coverage that pencils at full leverage on paper often doesn’t survive the full tax-and-insurance load, so running it both ways up front saves a re-trade. Where some institutional lenders cap the number of financed properties, non-QM DSCR channels generally evaluate each property on its own rental coverage, which suits multi-property investors. LLC-titled holdings are workable subject to lender program eligibility.
Where the Proceeds Go Next
Chesterfield equity often works best deployed outside Chesterfield. Ballwin, Ellisville, Manchester, and Wildwood are listed as adjacent markets on Apartments.com, and ApartmentFinder shows Ballwin one-bedrooms averaging $1,243 a month, well below Chesterfield’s averages. Workforce-priced stock there can carry stronger rent-to-value than a $600K house. Cash-out proceeds from a low-leverage Chesterfield refinance can fund a down payment on a property that covers itself more comfortably. See Lendmire’s Missouri DSCR platform for statewide context, and the refinance side for structure. The guide “Where DSCR and Conventional Diverge” is worth a read if you’re weighing conventional financing.
For an indicative scenario, connect with Lendmire or call 828-256-2183. Verify current local rental rules, property taxes, and insurance with qualified local professionals before committing.
Frequently Asked Questions
Can a $600K-plus Chesterfield house work for a DSCR cash-out?
Usually only at reduced leverage. At the median price with typical rents, modeled coverage falls well below 1.00 at 75 percent LTV. A lower loan-to-value, a sub-1.00 program, or an interest-only structure may be reviewed, subject to lender guidelines.
DSCR vs. conventional financing
Two common ways to finance an investment property in Chesterfield, MO. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
How long do I need to own before cashing out?
About six months, measured from title recording, on typical program guidance. Recently purchased rentals in the entry tier are the natural candidates once that clock runs.
Does Missouri’s non-disclosure status affect the appraisal?
Yes. Sale prices aren’t public record, so appraisers rely on MLS data. Comps are plentiful, given 719 transactions over the past year per Houzeo and RealtyTrac-style tallies, but mostly owner-occupant. Choose an appraiser experienced with West County.
Are condos better than houses for cash-out coverage here?
Often, on rent-to-value alone. Condo rents average $1,735 per Apartments.com against much lower price points, but HOA dues reduce coverage, so use the full obligation in your math.
Will Downtown Chesterfield’s new units hurt my rents?
Possibly for comparable Class A product once units are delivered. No source quantifies it. Older, lower-priced stock is less directly exposed, and the redevelopment may also strengthen the location.
Your Next Move
Look at the property you already own in Chesterfield. Does its rent clear the full obligation at 75 percent LTV, or only at 60 percent? And if you pulled that equity out, would the next deal sit in Chesterfield’s thin-rent market or a step west, where the rent-to-value math runs friendlier?
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage, and program. The team has been recognized as a 2026 Scotsman Guide Top Workplace and a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin, Chesterfield Housing Market
3. City-Data
4. Livability
5. RentCafe
6. NeighborhoodScout, Chesterfield Real Estate
7. Redfin, 63017 Housing Market
8. Houzeo, Chesterfield Market Data
10. Homes.com, Chesterfield Multi-Family
11. Apartments.com, Chesterfield Rent Trends
12. STLPR, Downtown Chesterfield
13. Logan University
14. a 2026 Scotsman Guide Top Workplace
15. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Missouri
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.