
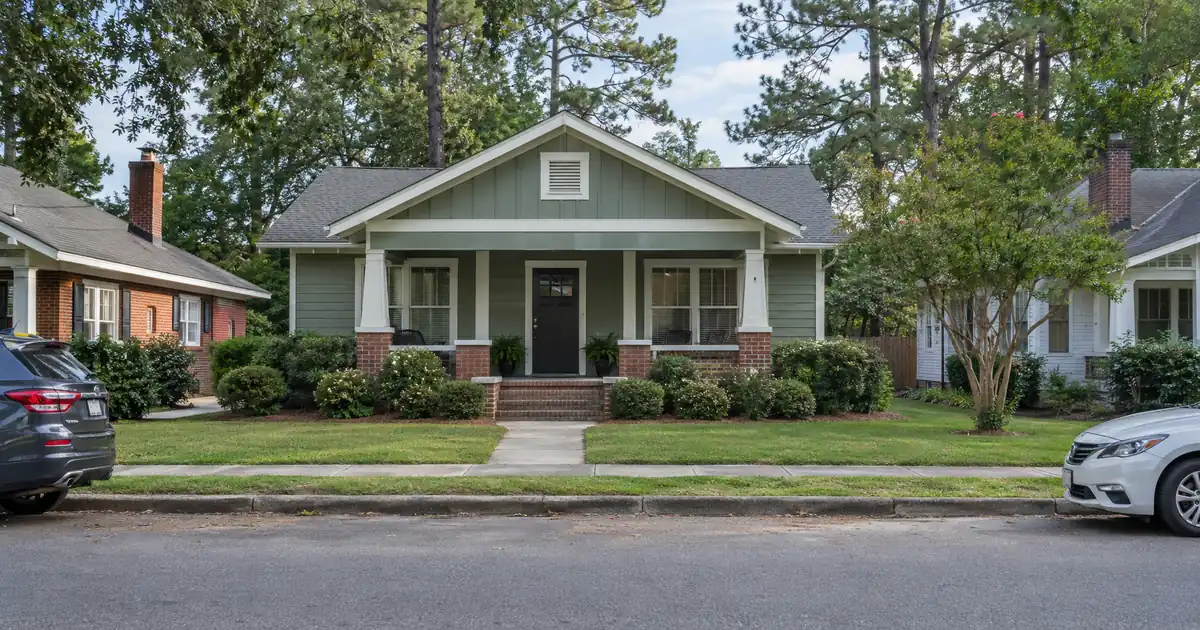
A rental on the Summerville Road corridor hits the DSCR math like this. Assume a 1950s-era single-family house valued near the NeighborhoodScout median of $136,586, renting for about the $1,111 average that NeighborhoodScout reports for the submarket. Modeled at 75 percent loan-to-value, with full taxes and insurance in the obligation, the coverage number lands around 1.4x. Push the same structure onto a median-priced Phenix City house and the number drops toward 0.9x. Two properties in one city can sit on opposite sides of the 1.00 line, and that gap is what cash-out planning here turns on.
Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, works with Phenix City, Alabama investors through a DSCR program footprint spanning 40 states plus Washington, D.C. This report covers the owner who already holds a property, not the buyer. It looks at how much equity can come out, which property types clear the coverage test, and what could change the picture over the next 6 to 24 months. Every modeled ratio below is an assumption, not a sourced market fact.
DSCR Cash-Out Calculator
Run the cash-out numbers in Phenix City, AL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
TL;DR: A Phenix City, Alabama cash-out refinance is underwritten primarily on the property’s rental income measured against its full monthly obligation, with proceeds capped by the loan-to-value ceiling and seasoning requirements.
- Cash-out LTV tops out at 75 percent, with about 6 months of ownership typically required.
- Sub-median stock and small multifamily pencil better than median-priced houses.
- Redfin shows the median sale price at $255K, up 16.1 percent year over year.
- Rents are softer than prices, so appraisal value may outrun rent-supported value.
Phenix City Market Snapshot
A quick read on the Phenix City investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $170,300 home value (StateDemographics) |
| Recent appreciation | +16.1% yoy (Redfin) |
| Vacancy | 22.7% (NeighborhoodScout) |
Why Phenix City Equity Is Worth Pulling
Phenix City’s equity story runs through appreciation that has outpaced rents. Owners who bought a few years ago may sit on meaningful equity, and Redfin’s local market data describes a market that is priced close to list, with homes going pending only slightly below asking. Whether that equity converts to cash depends on what the rent supports.
The price data needs a caveat. The Census-derived owner-estimated median home value is $170,300 per StateDemographics, which reprints ACS data. That is far below Redfin’s sale-price median, and both can be true: one measures what owners think their homes are worth, the other what buyers just paid. Zillow’s ZIP-level figure for 36870 is $247,130, so even citywide numbers differ from the subject property’s own ZIP.
The city itself is a mid-sized Alabama market. StateDemographics counts 38,499 residents in the latest ACS period, the 14th largest city in the state. RentCafe reports 49 percent of households, or 7,948, are renter-occupied. That is a deep tenant pool for a city this size.
The Two-State Metro Behind the Tenant Base
Phenix City sits directly across the Chattahoochee from Columbus, Georgia, and the two cities function as one interconnected metro, per an area description on Apartments.com. The city even runs on Eastern Time, unlike the rest of Alabama. The property, the taxes, and the loan sit in Alabama, but the paychecks are largely Georgia paychecks.
The City of Phenix City’s economic development page lists the regional employers. The page is old, so treat the counts as a historically cited ranking rather than current headcount. Fort Benning (now Fort Moore) sits at the top at 42,000. TSYS, now part of Global Payments, and Columbus Regional Healthcare, now Piedmont Columbus Regional, are each cited near 4,000. Aflac is cited near 3,700, and St. Francis Hospital near 2,000. Health care (Piedmont), payments, insurance, and the Army make a diversified base for a small metro.
The military layer matters most for underwriting. PCSgrades says the vast majority of soldiers live off-post with their families, and that people typically live in Fort Mitchell or Phenix City if not in Columbus. A 2026 PCS guide adds that Phenix City offers lower housing costs than Columbus. Housing allowances follow the Columbus military housing area, which gives a government-indexed ceiling for rents. Rents sitting near those allowance tiers are the most defensible to underwrite. Confirm the current tier before setting a rent assumption.
Troy University operates a Phenix City campus, and Columbus State University sits across the river. Neither has a verified enrollment figure in the research, so treat them as supporting demand rather than the anchor.
Where Does the Coverage Math Actually Work?
Older sub-median stock and small multifamily clear the coverage test here. Median-priced houses mostly do not. The reason is a rent-to-value squeeze: Zillow’s average rent across bedroom counts is $1,295 against Redfin’s $255K median, roughly 0.5 percent a month. Zillow’s own rental data shows $847 for a one-bedroom and $925 for a two-bedroom.
Rent sources disagree, so a range is the honest way to present them. RentCafe’s average is $1,174, but it covers only buildings of 50 or more units. Zumper shows a $1,080 median and rents down 11 percent year over year. A market source lists a $926 median. Rents are soft or drifting, not accelerating. Sizing a cash-out on optimistic rent is the fastest way to a file that does not qualify. (Appraisers can round a value up. Rent roll math doesn’t round.)
The Summerville Road Corridor
ZIP 36867 is the best-documented submarket. NeighborhoodScout describes mostly small to medium single-family homes and small apartment buildings, with many built between 1940 and 1969. It shows a median price of $136,586, an average rent of $1,111, and a modeled 22.7 percent vacancy rate. The vacancy figure is modeled, so treat it cautiously, but it hints at older and possibly stale stock. TopHap’s automated valuation for a typical home there is $175,696, or $110 per square foot. That is an estimate, not a sale price.
Modeled with full taxes and insurance at 75 percent LTV, the corridor’s rent-to-price relationship runs near 1.4x. That is meaningful cushion above the 1.00 baseline that most standard programs use. The catch: older housing carries maintenance and condition risk, and an appraiser working with limited comps may not reach the value an owner expects. Rent tied to Fort Moore and Columbus commuters gives the corridor its demand.
Duplexes and Small Multifamily
The strongest math in the research comes from stacked units. A Redfin-listed duplex is offered at $170,000 with two leased units at $850 and $725, or $1,575 a month, with leases running into the following year. That works out to about 0.93 percent monthly gross rent-to-price. The listing agent quotes a cap rate near 9.4 percent, which looks high before vacancy, maintenance, management, and reserves. Underwrite from the in-place leases, not the marketed cap rate. Modeled at 75 percent LTV including taxes and insurance, that rent pattern sits around 1.5x.
Homes.com shows the same type of inventory: a duplex with two renovated units renting at $1,000 each, a 2008-built duplex near Riverwalk access, and a seven-unit lot with a 3/1 house, a quadplex, and two cottages. Newer duplexes near the riverfront and older converted houses on Summerville Road are different risk profiles. Confirm unit legality and separate metering on any conversion before assuming the second unit’s rent counts.
Three-Bedroom Houses
Rentometer shows average rents of $965 for a 1BR, $1,010 for a 2BR, and $1,465 for a 3BR. Houses with 3BR or more run $1,400 to $2,100, while two-bedroom houses often sit just under $1,000. The jump from 2BR to 3BR is about $455, versus roughly $45 from 1BR to 2BR. Sample sizes are unknown, so confirm with local comps.
The implication for a cash-out: a 3BR house earns a real rent premium, but at Redfin’s median price even a $1,465 rent models to roughly 1.0x with full carrying costs at 75 percent LTV. That is at the line, not safely above it. A 3BR bought or valued below the median works better. The 2BR house is the weak spot. It gets a median-ish price with a sub-$1,000 rent.
How the Cash-Out Actually Sizes
Cash-out refinance proceeds come from the lesser of what the appraisal supports and what the rent covers. The loan cap is 75 percent of appraised value, and the loan must be big enough to pay off the existing mortgage before any cash reaches the investor. Seasoning is typically about 6 months of ownership measured from title recording. The minimum coverage baseline on most files is 1.00x, meaning the rent used for lender review must cover the full monthly obligation of principal, interest, taxes, insurance, and any HOA dues. Some lenders review lower coverage with compensating factors, but that usually means lower leverage or more cash in reserve. Credit tiers run from a 620 floor upward, and reserves typically run about 6 months of the full obligation. Review details are subject to lender overlays, and the equity figure is never guaranteed. Investors can walk through DSCR cash-out refi mechanics and the investor refinance breakdown for the general framework.
Working DSCR brokers see a recurring pattern in small, military-adjacent markets like this one: the appraisal comes in fine and the rent test is what limits the cash-out. Owners assume a hot sale-price market means large proceeds, then find the rent-to-obligation ratio binds first. The files that go smoothly usually start with an in-place lease, a documented rent history, and a realistic read of the property’s own ZIP rather than a citywide median.
Appreciation Versus Rent: Which Signal Do You Trust?
Sources disagree on direction, and that is itself a finding. Redfin shows sale prices up 16.1 percent. Movoto puts the median listing price at $261K, down 1 percent year over year. Zumper shows rents down 11 percent, while Zillow’s rent figure has risen by $120. Zumper notes it lacks the inventory to break rents out by neighborhood.
Sold-price gains have outpaced rent growth. For a cash-out, that squeezes rent-to-value on the loan and can produce an appraisal above what rent alone would justify. Don’t size a cash-out on a single source’s appreciation figure. Use closed comps in the subject’s own ZIP. If prices flatten while rents stay soft, the properties with thin coverage today get thinner. Properties already above 1.3x have room to absorb that.
What to track over the next 6 to 24 months:
- Closed-sale comps in the subject ZIP. They set the appraisal, and the appraisal sets the ceiling.
- Lease-renewal rents on in-place units. Rent softness shows up here before it shows up in the aggregators.
- New-construction pace. NewHomeSource lists 13 communities in the Phenix City area, including Summerfield off Summerville Road. More new stock can cap rent growth on older units.
- Military housing allowance changes. They move the rent ceiling for the tenant group that matters most.
The Riverfront and Lakewood (Longer-Term, Less Data)
Downtown and the riverfront are a redevelopment story rather than a cash-flow one. The city’s Riverwalk page describes a 1.21-mile structure on the western bank of the Chattahoochee, along with a 3,000-seat amphitheater. Alabama Recreation Trails calls the whitewater course the longest urban whitewater course in the world. Business View Magazine reported $40 to $50 million of riverfront construction that included a Troy campus and a hotel, though that coverage is dated. No rent or price data was found for this area, so it belongs in the appreciation-potential column, not the coverage column.
The Lakewood and Summerfield area reads as suburban and newer, with new-construction listings but no sourced rents or prices. Newer, higher-priced stock has a thinner rent-to-value ratio than older stock under $150K. Owners there may have the most equity but the least coverage.
Investors holding LLC-titled properties should note that closings in an entity name are subject to lender program eligibility. For Alabama-specific program context, see the DSCR loans in Alabama hub. Investors should also verify current local rental rules, taxes, and insurance with qualified local professionals, especially because the city straddles Russell and Lee counties.
What Happens to the Proceeds?
Cash-out proceeds are only useful if the next property also works. Phenix City’s own stock offers a straightforward pattern: pull equity from an appreciated, well-covered property and redeploy into sub-median stock or a small multifamily at a stronger rent-to-price ratio. The refinanced property carries a higher obligation, so run its new coverage number before assuming it stays above 1.00. The new purchase should be tested on its own coverage rather than on a hoped-for rent bump.
A useful sanity check is a stress test: cut the modeled rent by 10 percent and see whether the file still clears 1.00. Given Zumper’s 11 percent rent decline, that is not a hypothetical. Coverage cushion is the buffer against soft rents. Investors who want a file reviewed can request a quote or call 828-256-2183.
DSCR vs. conventional financing
Two common ways to finance an investment property in Phenix City, AL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Where the Mispricing Sits
The asymmetric opportunity in Phenix City is older small multifamily and sub-median 3BR stock in the Summerville Road corridor. Those properties are priced well below the $255K citywide median. They earn rents that sit close to the housing-allowance tiers of a large off-post military tenant base. They also show rent-to-price ratios (about 0.93 percent on the sampled duplex, above 0.8 percent on the corridor average) that the median house cannot match. The market is pricing the whole city off its riverfront and new-construction stock, while the cash flow lives in the 1940s-to-1960s housing near the Columbus commute.
Frequently Asked Questions
Can a median-priced Phenix City house support a cash-out refinance?
Usually not without modest leverage or a strong rent. At the $255K Redfin median and a blended rent near $1,295, modeled coverage including taxes and insurance falls around 0.9x at 75 percent LTV. A 3BR renting near the Rentometer $1,465 average gets to about 1.0x. Sub-median stock and duplexes carry more cushion. Eligibility depends on lender guidelines and property review.
Does the Fort Moore connection help a refinance appraisal or the rent test?
It helps the rent test more than the appraisal. Off-post soldiers make up much of the local tenant base, and housing allowances follow the Columbus military housing area, which gives a documented rent ceiling. Appraisals still depend on closed comps in the subject’s own ZIP. Confirm the current allowance tier before assuming a rent.
How long must I own a Phenix City rental before pulling cash out?
Typically about 6 months, measured from the date the title was recorded. Investors who bought recently may still qualify on a rate-and-term basis, but cash-out proceeds require that seasoning. Program details vary by lender.
Which Phenix City submarkets have real rent data?
Only Summerville Road (ZIP 36867) has a documented figure, an average rent near $1,111, and that is modeled data. Downtown, Lakewood, and the Highway 80 side had no verified rent data. Use closed comps and current leases rather than assumptions.
Does the 16 percent price gain mean I can borrow more?
No. The 75 percent LTV ceiling applies to appraised value, but the loan also has to clear the rent-based coverage test and reserve requirements. Rapid appreciation raises what an appraiser might say, but soft rents can limit what the file supports. The equity available is never a guaranteed cash figure. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. NeighborhoodScout, Summerville Road
2. Redfin, Phenix City Housing Market
4. RentCafe
6. City of Phenix City, Major Employers
7. Piedmont
8. Pcsgrades.com — Army Fort Moore
11. Zillow — Market Trends Phenix City AL
12. Zumper
14. City of Phenix City, Riverwalk
15. Alabama Recreation Trails, Chattahoochee Whitewater
16. 2025
17. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Unlock Equity With DSCR Cash Out Refinance Phenix City Alabama · DSCR Cash Out Refinance Opelika Alabama · Cash Out Refinance Investment Property in Birmingham AL
Guides: Investment Property Cash-Out Refinance in Alabama
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.