
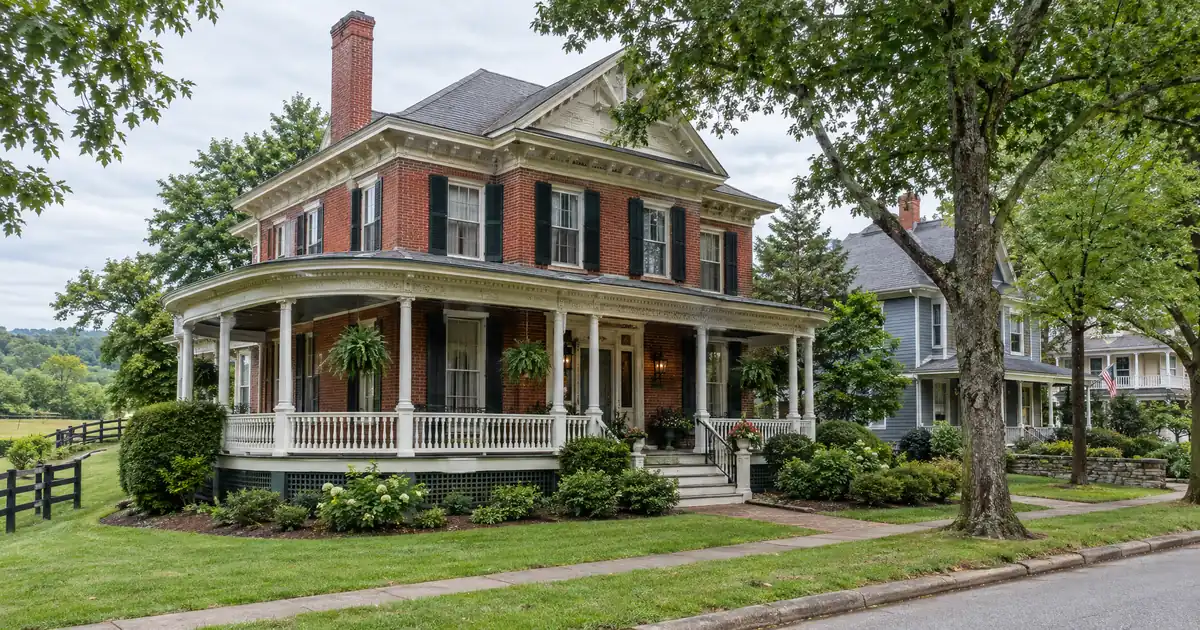
Picture an investor who bought a three-bedroom rental in Bellevue a couple of years back. It’s leased, it’s steady, and it has quietly built equity while sitting there. The next deal is on the table, but the cash is locked inside that house. A cash-out refinance on an investment property is how that equity goes back to work. In a small market like Danville, the details of how it gets done matter more than the headline idea.
DSCR Cash-Out Calculator
Run the cash-out numbers in Danville, KY
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
A cash-out refinance on a Danville, Kentucky rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file works when rent used for lender review covers principal, interest, taxes, insurance, and any dues near the 1.00 benchmark, typically with leverage capped at 75 percent and about six months of seasoning.
- Redfin shows a median sale price near $229K, up only 0.2 percent year over year.
- Rentcast medians run $1,130 for two-bedrooms and $1,410 for three-bedrooms.
- Modeled single-family coverage at the median price lands near 1.0 including taxes and insurance, so structure matters.
- Homes averaged 50 days on market versus 38 a year earlier, so exits are slowing.
- Older small-unit stock near downtown and East Main is the natural place to redeploy proceeds.
Lendmire structures DSCR scenarios for investors targeting Danville, Kentucky and places them with wholesale lenders across 41 markets, including D.C. It is a DSCR-focused mortgage broker, NMLS# 2371349. If you need the mechanics behind the coverage ratio first, the DSCR fundamentals cover them. This article assumes you already own the asset and want to know what it can fund.
Danville Market Snapshot
A quick read on the Danville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $207,600 median value (Data USA: Danville, KY) |
| University enrollment | ~1,400 students (Colleges That Change Lives) |
| Employment | ~180 Meggitt employees (2021) (Livability: Danville-Boyle) |
| Vacancy | 6% (AffordableHousingOnline) |
How Much Equity Does Danville Really Give You?
Danville equity comes from disciplined purchase prices and time, not from market momentum. Prices here are flat to modestly up. Anyone planning a cash-out around a big appreciation jump will be disappointed.
Look at the price data. According to Redfin, the median sale price over the most recent three months is essentially flat year over year, with only a modest number of homes changing hands in June and homes taking noticeably longer to sell than they did a year earlier. Redfin scores the market “somewhat market-rate,” which is a polite way of saying it isn’t hot. Zillow’s average home value reads higher and shows modest growth, but that is an average of all homes, not a median of recent sales, so the two figures measure different things and needn’t agree. Data USA’s Census-based median property value shows a slightly faster gain over the past year, though still gradual.
Nobody here is buying a rocket ship. It’s steady, slightly upward, and slower to sell. For a cash-out, that leaves two levers:
- Price discipline at purchase. Equity built in the first place by buying below what the property is worth carries the refinance.
- Value-add work. Rehab on older houses is often where real equity gets created in a market this flat.
Zillow reports homes going pending in around 30 days, while Realtor.com data reports a much longer median on market. These sources measure different things, so treat the timing picture as mixed and skip any promise of a clean exit.
The Coverage Math at the 75 Percent Cap
At the 75 percent cash-out cap, a Danville single-family rental at the median price lands right around 1.0 coverage once taxes and insurance are included. That leaves almost no cushion, which is why the structure of the refinance matters as much as the property.
Run the numbers on a modeled scenario. These are assumptions, not market quotes. Assume a house appraising near the $229K citywide median and renting at the Rentcast three-bedroom median of $1,410. Divide that rent by the full monthly obligation (principal, interest, taxes, and insurance) at the 75 percent ceiling. The coverage ratio comes out roughly at 1.0, and rounding down is the honest read. Drop the leverage to around 65 percent and the same house moves into the low 1.1s, still including taxes and insurance. Swap in the $1,230 average rent and the file slips below 1.00 at the cap.
A simple screen shows why. Average rent of $1,230 against Zillow’s average home value works out to under half a percent a month. Movoto’s May median list price of $324K would put a typical listing well under that. Rents in this market simply don’t stretch far relative to price. A property that clears the benchmark comfortably usually got there through a low basis, a strong lease, or unit count.
If a file lands below 1.00 on long-term rent, the paths a lender may review include lower leverage, a sub-1.00 program, or an interest-only structure. Each carries its own credit, reserve, and pricing conditions, and eligibility depends on lender guidelines and property review. A typical 1.00 benchmark is common because rent covers the payment at that level. It is not a guarantee at 1.00 or a wall below it.
Pulling equity with a DSCR cash-out walks through the general mechanics. The Danville-specific takeaway is simple: don’t assume the average house cash-flows at 75 percent. Model each property.
Where the Equity Pulls Cleanly
The best cash-out candidates in Danville are older small-unit properties near the hospital and downtown, followed by workforce single-family in Bellevue. Neighborhood-level price and rent data doesn’t exist in any source I’d trust, so these profiles are qualitative. Trust the pattern, not a made-up number.
East Main and the Downtown Core
This is where I’d look first for a multi-unit equity story. The East Main Street Historic District is older housing built in the decades around the turn of the last century, close to downtown and to Ephraim McDowell Regional Medical Center. That stock lends itself to duplex and triplex configurations. Demand comes from hospital staff, Centre staff, and downtown workers who want to walk to work.
Here is the multi-unit logic. Rent doesn’t scale with size in this market. A three-bedroom house earns about $1,410 at the Rentcast median, while four two-bedroom units at $1,130 each would gross about $4,520 a month. Stacking small units is the realistic way to lift income relative to the loan. I have no sourced duplex or fourplex price data for Danville, so that’s a comps exercise, not a claim.
One caution. Confirm the property is legally established as a multi-unit and that the appraisal treats it that way before you underwrite it as one. A house that has been carved up informally doesn’t get the same credit from a lender.
Bellevue
Bellevue is a predominantly residential west-side neighborhood with quiet streets and established homes. It’s a candidate for the workforce single-family rental, which is the core product here. Current asking rents on small older houses cluster around $950 to $1,200, according to a Zillow listing snapshot. Those are asking rents, not a market statistic, and larger or newer houses ask a good deal more.
The move is to underwrite at conservative rents, not the top of the range. Strong equity here comes from a low basis. If you paid full retail for a Bellevue house, expect coverage at 75 percent to be tight.
Perryville Road Corridor
Newer ranch and new-construction three-bedroom product shows up near Boyle County High School. Newer product means lower maintenance, which helps net cash flow. It also means a higher basis, and in a market where rents rise less than proportionally with price, a higher basis erodes coverage. A newer house can work at conservative leverage. It rarely wins on cash-on-cash.
Where I’d Skip the Cash-Out Thesis
Maple and Lexington Avenues are the higher-end, owner-oriented streets near Centre. They are lovely and they’re priced for owner-occupants, so investor coverage is thin. The southern retail and commercial corridor is car-dependent and commercial in character. It has little of the older rental stock this strategy wants. Skip both for DSCR cash-out purposes.
What’s Holding Up the Rent Roll?
Danville’s rental demand rests on a hospital and a college that don’t compete for the same tenant. That produces long-tenure workforce renters instead of student turnover, which is what a cash-out lender wants to see in a lease history.
A regional college reports undergraduate enrollment of 1,385. Roughly 98 percent of students live on campus, per Colleges That Change Lives. Off-campus student rental demand is therefore small, and what Centre does supply is faculty and staff. Don’t underwrite a house here as a student rental.
The healthcare side is bigger. Ephraim McDowell serves approximately 120,000 residents across Boyle and neighboring counties, according to Business View Magazine. The Danville-Boyle County Development Corporation maintains the official employer list, which also covers manufacturing names including Hobart, Denyo, and Meggitt. Check headcounts there before leaning on any single employer in a lender narrative.
Supply looks tight rather than loose. In September 2025 the mayor said the city is 1,700 homes short of what its citizens need, including workforce and middle-class housing. A Bowen National Research study for Kentucky Housing Corporation projected a housing gap in Boyle County of more than 20 percent of existing households by the end of the decade, as reported by Somerset-Kentucky.com. An aggregator, AffordableHousingOnline, reports a 6 percent rental vacancy rate, which is undated, so treat it as directional. Underwrite vacancy at a conservative 6 to 8 percent and don’t count on 100 percent occupancy.
Rentals are also a normal part of the housing mix. Data USA puts homeownership at 56.4 percent, and 2-bedroom and 3-bedroom units make up 48.3 and 34.0 percent of the rental stock. Two- and three-bedroom product is the right target.
What’s the Catch With a Market This Size?
The catch is the appraisal, not the borrower. Danville has about 17,300 residents per Wikipedia’s Census summary, and a market that small has a thin pool of comparable sales. When you’re asking an appraiser to support a cash-out valuation, one or two odd comps can move the number.
Medians swing on a handful of sales. Treat the ARV as conservative, don’t assume big equity from a short hold, and remember that seasoning is measured from title recording. Seasoning before cash-out is about six months of ownership, per program guidance.
In markets like this, deal desks tend to see the same friction point: the appraised value comes in a notch under the investor’s expectation, and the coverage ratio that looked fine at the higher value gets tight at the lower one. The cleaner files from a documentation standpoint tend to be the ones where the investor already has a lease in place, a conservative rent supported by comps, and a fresh insurance quote in hand before submission. Going in with a number that still works at a lower value is the simplest protection.
A separate wrinkle: the same market that gives you tight coverage also gives you modest appreciation. Don’t count on a cash-out being a repeat event every year. It’s a one-time tool that turns the equity you bought or built into fresh capital.
Putting the Proceeds to Work
Cash-out proceeds are only as good as the next deal’s basis. In Danville, the smart redeployment is small-unit product where income stacks faster than price, not another single-family house at full retail.
DSCR vs. conventional financing
Two common ways to finance an investment property in Danville, KY. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
On most files, several program parameters shape the structure (qualification is subject to lender guidelines):
- Leverage: cash-out tops out at 75 percent, not the 80 percent purchase figure.
- Coverage: the baseline is 1.00, measured as rent used for lender review against full PITIA.
- Credit: tiers run 620, 660, 680, and 700, with a floor around 620. Better scores generally improve terms.
- Reserves: about six months of PITIA, more on larger balances.
- Loan size: up to $3,000,000 on standard programs, with smaller balances routed through select lenders in the network.
The equity you can actually pull depends on rent used for lender review, PITIA, reserves, and that 75 percent ceiling. It’s not a guaranteed cash figure. LLC-titled properties are common on these files, subject to lender program eligibility.
Investors weighing this against a conventional refinance should look at the comparison. For the state overview, DSCR loans in Kentucky covers the rest. To test a specific property, see what the numbers look like or reach the team at 828-256-2183.
A last piece of thinking out loud. The stronger play may be using proceeds on a duplex near downtown rather than a second workforce house, since unit count does the work that price appreciation won’t. Investors who prefer simplicity could reasonably argue the other way. Either way, run both against the 75 percent cap before committing.
Also note that older houses, including anything near the historic district, can carry higher maintenance costs. A rehab budget belongs in the analysis. And investors should verify current local rental rules, taxes, and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Danville, Kentucky?
Qualification is built around the property’s rent against its full PITIA, with a 1.00 baseline and a 75 percent LTV ceiling on cash-out. The property generally needs about six months of ownership from title recording, reserves near six months of PITIA, and a credit score meeting the program tier, with a floor around 620. Details vary by lender, borrower, and property.
What are the requirements for an investment property loan in Danville, Kentucky?
Expect a lender to review the rent roll or lease, the appraisal, credit profile, and reserves. Eligible property types include single-family homes and small multifamily, which fits Danville’s stock well. Manufactured homes, log homes, and barndominiums fall outside these programs. Program terms vary, so confirm the current parameters before planning around them.
Will a typical Danville rental clear 1.00 at the 75 percent cap?
Often not by much. At a price near the $229K median and a rent near the $1,410 three-bedroom median, modeled coverage sits right around 1.0 once taxes and insurance are counted. Lower leverage, a low basis, or unit stacking improves the picture. Underwrite each property rather than the market average.
Does a regional college create student rental demand?
Very little. Roughly 98 percent of students live on campus, so the college’s demand comes mostly from faculty and staff. The more durable renter base is hospital and workforce employment, which suggests longer leases and steadier occupancy than a student-heavy market.
What DSCR terms may lenders review for investors in Kentucky?
Lendmire arranges DSCR investor loans, including in Kentucky. One key feature is that eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines.
Danville or Lexington? Right Now, Danville
Lexington sits about 35 miles up the road and offers a deeper buyer pool and easier appraisal comps. For an investor who already owns in Danville and wants to pull equity, though, the math favors staying put and reinvesting locally. Danville’s modest price levels, tight supply, and older small-unit stock mean proceeds can buy more rent per dollar of basis than in a bigger, pricier market. The thin comp pool is the price you pay for that, so cash out at conservative leverage and keep the next purchase on multi-unit product.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C. Eligibility is generally reviewed around property-level rental income rather than personal income, subject to lender and program guidelines, which suits self-employed investors and LLC-owned portfolios. The brokerage was recognized as a 2026 Scotsman Guide Top Workplace and a top-ranked workplace in 2025, as covered in Lendmire’s 2026 Top Workplace announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Danville housing market
6. Ephraim McDowell Regional Medical Center
7. Zillow
8. Business View Magazine: Danville-Boyle County
9. Danville-Boyle County Development Corporation
10. WEKU: Kentucky housing shortage coverage
13. a 2026 Scotsman Guide Top Workplace
14. Scotsman Guide — Top Workplaces 2025
15. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property Danville Kentucky · Cash Out Refinance Investment Property in Danville, Illinois: Equity From a Sub-$125K Basis · Cash Out Refinance Investment Property Pikeville Kentucky
Guides: Investment Property Cash-Out Refinance in Kentucky
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.