
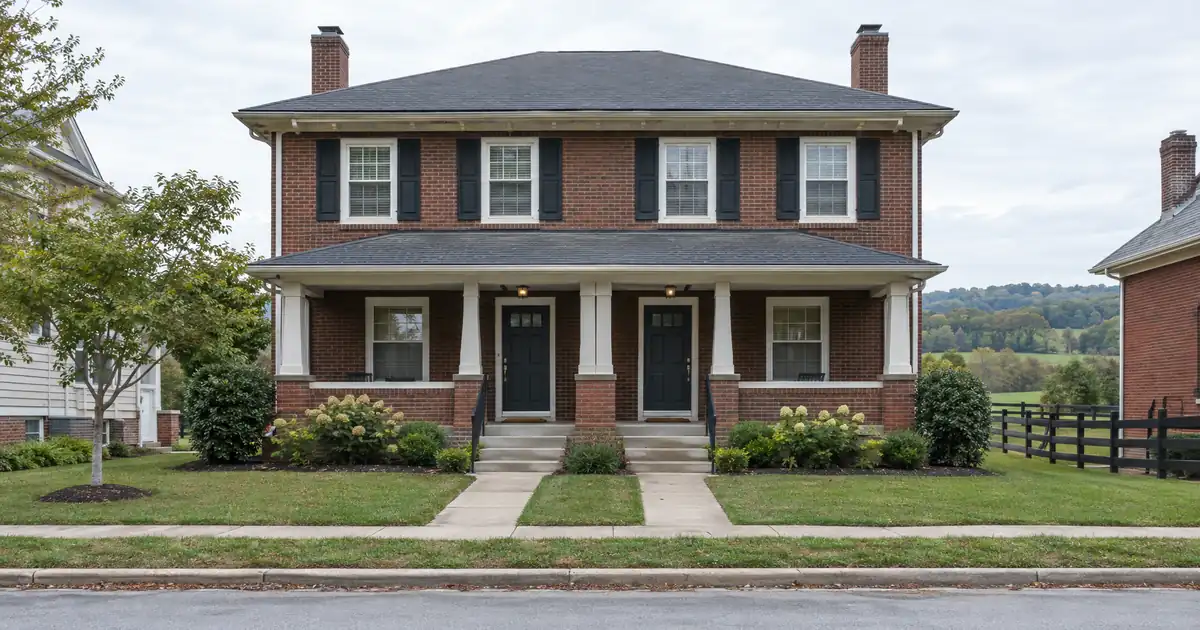
A rental in Versailles’ older downtown core hits the DSCR math like this. Take a three-bedroom valued near $190,000 (the price tier of the anecdotal sales in Redfin’s listing samples) and assume a modeled rent of $1,400. At the 75% cash-out LTV ceiling, and with taxes and insurance included at Kentucky averages, coverage lands around 1.2x. Now swap in the typical single-family home, which Zillow values at $359,888, and assume a $1,700 rent. Coverage falls below 0.85x on the same structure. Same town, same loan program, opposite outcomes. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker. DSCR financing for Versailles, Kentucky investors runs through wholesale lenders that Lendmire works with across 41 markets, including D.C. The question for an owner here is not whether the program exists. It is which property in the portfolio has the rent-to-basis profile to support an equity pull.
DSCR Cash-Out Calculator
Run the cash-out numbers in Versailles, KY
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
At a Glance: A DSCR cash-out refinance in Versailles, Kentucky is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the outcome turns on the ratio of rent to value, not the borrower’s income. In a market where Zillow shows values down 1.4% year over year, coverage matters more than paper appreciation.
- Cash-out LTV tops out at 75%, with about 6 months of seasoning from title recording.
- Typical single-family stock in the $360K range models below 1.00x on rent alone.
- Older, lower-basis homes and priced-right duplexes are the likelier coverage candidates.
- Rent sources conflict, from about $965 to $2,045, so the appraisal’s rent schedule decides.
Versailles Market Snapshot
A quick read on the Versailles investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | Median value $299,700 (Data USA) |
| Typical rents | $965 rent ($676–$1,347) (City-Data Woodford County) |
| Population | Population 10,492 (Census Reporter) |
| Employment | 13.8K jobs (Data USA) |
Where the Equity Comes From When Prices Are Flat
Equity in Versailles comes from purchase discounts, renovation, and paydown, not from market appreciation. Values are drifting sideways to slightly down. Zillow puts the average home value at $359,888, down 1.4% over the past year. Homes.com reports a median sale price of $369,950 over the last 12 months, down 3% from the prior period. Those two sources measure differently, so treat them as a band of roughly $360K to $370K, not a single truth. One note on thin data: a single-month median in a small sample swung above $500K, and that figure says nothing about trend. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
For an extraction strategy, the implication is direct. An investor who bought years ago at lower basis may hold real equity. An investor who bought recently near current pricing should assume little or none from market movement during seasoning. The cash-out is measured against a 75% ceiling of appraised value, and what remains after the existing balance, reserves of about 6 months of PITIA, and costs is the available capital. It is a function of the appraisal, not a promise. The DSCR cash-out refi mechanics page walks through that sequence, and a separate page on refinance details covers the broader refinance options.
The Coverage Math by Property Tier
Versailles is a high-basis, low-yield market, and coverage separates cleanly by price tier. A typical single-family home fails the 1.00x baseline on rent alone, while older lower-priced homes clear it. The table below uses modeled assumptions, not cited market rents, and every figure includes taxes and insurance at Kentucky averages on a 30-year amortization at the 75% ceiling.
| Modeled scenario | Value | Assumed rent | Coverage |
|---|---|---|---|
| Typical SFR, lower rent | ~$360K | $1,700 | Under 0.85x |
| Typical SFR, upper rent | ~$360K | $2,045 | About 0.95x |
| Older workforce home | ~$190K | $1,400 | Around 1.2x |
| Duplex, two units at $965 | ~$300K | $1,930 | Just over 1.0x |
The Homes.com rental data backs up the top of the table: a price-to-rent ratio of 18.1, which the portal labels balanced, and a single-family rental median of $2,045. Even at that ceiling, a $360K house barely approaches the baseline. Most standard programs are built around a 1.00x benchmark because rent covers the obligation at that level. Some lenders will review lower ratios, but those files usually need lower leverage, stronger reserves, or different pricing, and eligibility depends on lender guidelines, credit, and property review.
The rent-to-value picture at the county level reinforces it. City-Data’s ACS-derived figures show a 2024 median contract rent of $965 against a median home value of about $329,000, with a value range running from $211,532 at the lower quartile to $459,200 at the upper. Median rent is roughly 0.29% of median value. Coverage lives near the bottom of that value range, and probably below it.
Rent Data That Disagrees With Itself
Versailles rent estimates run from about $965 to $2,045 depending on the source, and that spread is the single largest input uncertainty in any coverage model here. Zumper reports an average of $1,697 but flags limited data. RentalSource shows an average of about $1,412 and roughly 32 days on market. The ACS county median contract rent sits at $965, and ACS reflects existing leases, including long-tenured ones below current asking levels.
Listings-based rents reflect what new tenants pay. Contract rents reflect what sitting tenants pay. A lender’s appraisal will use a market rent schedule or the in-place lease, so the practical move is to have a signed lease and a rent survey ready before applying. The renter base is also small. City-Data counts 3,114 renter-occupied units in the county as of the 2020 census, so comps are few and estimates carry wider error bars. No reliable vacancy rate turned up, and sources conflict on the picture. Days on market suggest balance, not tightness. Underwrite a meaningful vacancy cushion and don’t assume rent growth.
Downtown Core, Rental Pockets, and Midway
No reliable neighborhood-level price or rent series exists for Versailles, so submarket analysis here is qualitative.
The historic core. Homes.com describes late-19th and early-20th-century housing near downtown: Colonial Revival, Queen Anne, and minimal traditional styles. This is the most plausible source of lower-basis stock, and it is where an older owner is most likely to have both meaningful equity and coverage that clears. It is also where appraisal comps get thinnest, since older homes vary widely in condition.
Established rental pockets. Homes.com’s rental guide names Harrods Hill, Stonewall, Beaumont, Garden Springs, and Wellington as popular rental areas. Those are the places tenants already look, which helps a lender’s rent schedule. Without pricing data, the ratio math per pocket can’t be stated.
Newer development. Firmantown, Shetland, and the south side are newer areas. Newer product tends to carry higher basis, which pushes toward the sub-1.00 side of the table.
Midway. The neighboring town, home to Midway University and the Lakeshore Learning distribution network, is outside the city limits and not covered by this analysis.
Property Type: Why Duplexes Are Thin but Interesting
Versailles offers little small multifamily, so a duplex is a niche asset with thin comps. The Woodford County housing study from the University of Kentucky’s CEDIK found 9,229 one-unit detached structures, over 82% of county housing, and only 387 attached units, with “very few multi-family units including duplexes, fourplexes, and condominiums.” The data predates recent construction, but the pattern is clear.
That scarcity cuts both ways. Local broker listings on Keys to Kentucky show duplexes exist, including one in the Blackhawk Circle area, though no verified prices or rents turned up. Two rents against one price is the most natural route to coverage. In the modeled table above, two units at the county median contract rent only clear the baseline when the property is priced near $300K or below. At $360K, that same duplex models near 0.9x. Thin comps also mean the appraiser leans on a handful of sales, which complicates the value that the 75% ceiling applies to.
Working DSCR brokers see a recurring pattern in high-basis small markets: the first file stalls at the rent schedule, not the credit review. Owners assume the asking rent on a listing carries the number, then the appraiser’s schedule comes in lower, and coverage drops a tenth or more. The files that go smoothly usually arrive with a signed lease, a documented rent survey, and a clear plan for the reserves before anyone asks.
Tenant Demand Runs Through Lexington and Frankfort
Rental demand in Versailles is regional, not local. The same housing study found that only about 33% of Woodford County’s workforce, 3,115 workers, lives and works in the county. Many residents commute out and many workers commute in. Census Bureau QuickFacts puts the city’s population at 10,492 with a 24.5-minute mean commute, and the Versailles urban area at 17,302.
Local employment is broad, not concentrated. Data USA shows about 13,800 county jobs, led by health care and social assistance (1,771), educational services (1,572), and manufacturing (1,495), with employment up 0.6% in the latest year. Named employers include Brown-Forman’s Woodford Reserve, Yokohama, Pilkington, and Lakeshore Learning, whose state-announced Midway expansion adds a 360,000-square-foot facility and 40 jobs. The Woodford County Economic Development Authority frames the county as horse-and-bourbon country between Frankfort and Lexington.
For a lender reviewing a rental, that means a tenant pool tied to regional job centers as well as local ones. Stable, but not insulated.
Seasoning, Appraisals, and Asking-Price Traps
Base the cash-out on closed comps, not asking prices. Movoto shows a median asking price near $482K, about 1% below a year earlier, while sold-price measures run $360K to $370K. That gap is over 25%. An owner who sizes a refinance off listings will be disappointed at appraisal.
Program guidance applies on top of that. Seasoning is about 6 months of ownership measured from title recording. Credit is generally reviewed against tiers starting at a 620 floor, with better positioning at 660, 680, and 700. Reserves run about 6 months of PITIA on most files. Loan amounts go up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network. Those are guideline ranges subject to lender review, not commitments. Entity-titled properties may qualify, subject to lender program eligibility.
Anyone weighing refinance versus a conventional path can review the key differences, and the guide “What Is a DSCR Loan” covers the ratio itself. Kentucky-specific program context lives on Lendmire’s Kentucky DSCR platform. Owners who want to test a specific property can see how the DSCR math pencils or call 828-256-2183.
What Happens Below 1.00x
A file modeling under 1.00x isn’t dead, but it isn’t routine either. Options a lender may review include a sub-1.00 program with lower leverage, an interest-only structure, or a different property in the portfolio carrying the loan. Each brings tradeoffs: less cash out, tighter reserves, or different pricing. Qualification stays subject to lender guidelines, credit approval, and property review. For a typical $360K single-family rental here, the honest read is that a cash-out at the full ceiling is a stretch. A smaller pull, or moving the equity request to the older lower-basis asset, is usually the better fit.
The Blind Spot: Thin Comps Meet Conflicting Rents
The biggest risk for DSCR-financed investors in Versailles is a rent-and-value estimate resting on very few data points. Small renter base, scarce duplex comps, flat prices, and rent sources spanning roughly $965 to $2,045 mean the appraiser’s schedule can move coverage more than any borrower-side choice. Model the deal at the low end of the rent range first, and treat anything above it as upside.
DSCR vs. conventional financing
Two common ways to finance an investment property in Versailles, KY. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Versailles, Kentucky?
Qualification centers on the property’s rent measured against its full monthly obligation, with a common baseline near 1.00x, plus credit, reserves, and seasoning of about 6 months from title recording. Cash-out is capped at 75% of appraised value. Because typical Versailles single-family homes model below the baseline, lower-basis properties tend to qualify more readily, subject to lender guidelines and property review.
What are the requirements for an investment property loan in Versailles, KY?
Expect a credit floor around 620, with stronger positioning at 660 and above. Reserves run about 6 months of PITIA, and the property needs supportable rent, ideally a signed lease plus an appraisal rent schedule. Eligible types generally include single-family and small multi-unit homes. Manufactured homes, log homes, and barndominiums fall outside these programs.
Does Versailles’ flat pricing hurt a cash-out plan?
Yes, it removes the appreciation cushion. Values are down 1.4% year over year at Zillow, so equity mostly comes from an older, low purchase basis or completed renovation. Owners who bought near current prices should expect little to extract, and should size the refinance on closed sales, not asking prices.
Are duplexes a better DSCR fit than single-family homes in Versailles?
They can be, but only at the right price. Two rents against one price helps coverage, though duplex stock is scarce and comps are thin. At the county median contract rent of about $965 per unit, a duplex models just over 1.0x near $300K and closer to 0.9x near $360K. Get actual rent rolls before assuming either.
Can Lendmire help investors explore DSCR financing for properties outside Kentucky?
Yes. Lendmire arranges DSCR investor loans through wholesale lending channels. Qualification centers on the property’s rental income, subject to lender guidelines.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage specializing in DSCR investor loans, helping arrange financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. Its model centers on property-level rental income reviewed by the lender rather than W-2 documentation, subject to lender guidelines, which suits entity-owned and multi-property investors. Lendmire is recognized as a 2026 Scotsman Guide Top Mortgage Workplace and a 2025 Scotsman Guide Top Mortgage Workplace.
Investors should verify current local rental rules, taxes, and insurance with qualified local professionals.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow, Versailles home values
5. Homes.com, Versailles city guide
7. Zumper
8. RentalSource
9. Woodford County Housing Study (CEDIK/UK)
10. Keys to Kentucky
11. Census Reporter, Versailles, KY
12. newkentuckyhome.ky.gov — State-announced Midway expansion
13. Woodford County Economic Development Authority
14. Movoto
15. a 2026 Scotsman Guide Top Mortgage Workplace
16. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Guides: Investment Property Cash-Out Refinance in Kentucky
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.