
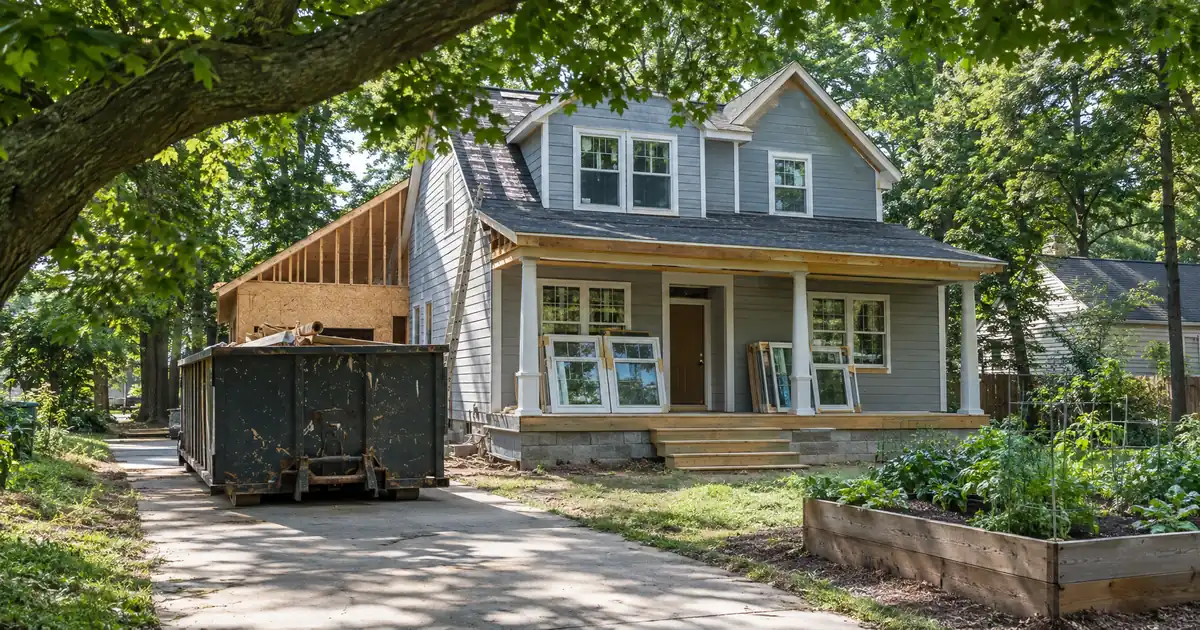
The Quick Read: Tenant type rarely matters on the hard money loan itself, because a flip is usually vacant during the rehab. It matters at the exit, when a long-term rental loan reviews the lease and who signed it.
- A flip lender looks at the deal: purchase price, rehab budget, after-repair value, borrower cash, credit, and the exit plan.
- A stranger on a market-rent lease is the standard file. A relative on a lease can work in some programs and is excluded in others.
- A relative living in the borrower’s household is an occupancy problem, not a lease problem.
- Read the exit lender’s related-party rule before the hard money loan closes.
Who Each Option Is Really For
A stranger tenant is for the flipper who wants the cleanest exit file. The lease is arm’s-length, the rent follows the market, and the payment trail is unconnected to the borrower. A relative tenant is for the flipper who has a real reason to place family, who can document market rent, and who has confirmed the exit lender allows related-party leases. Neither choice changes the hard money approval. Both change what the refinance file looks like.
What this loan actually costs to carry.
Hard money is sized against the project and priced by time. Enter the deal and see how much the program will lend, the cash required at closing, the carry while you hold it, and what is left at the exit.
Leverage tiers on the current program: 85% with fewer than 2, 90% with 2 or more, 93% with 5 or more completed projects — every tier capped at 75% of after-repair value. Loan amounts up to $5,000,000, larger by exception; terms of 6 to 18 months, interest-only, no prepayment penalty. The rehab portion funds in draws against completed work, not at closing.
Program parameters shown update from Lendmire’s centralized guideline source. Rate, points, and months are editable assumptions, not quoted terms.
Cost cap sets the loan · positive spread
Illustrative estimate only — not a quote, Loan Estimate, approval, or commitment to lend. Rate, points, and months are editable assumptions. Hard money is business-purpose financing for real estate investors, not a consumer mortgage. Leverage on the current program tops out at 93% of project cost for investors with a documented track record, capped at 75% of after-repair value, with rehab funding up to 100% of the documented budget released in draws; actual terms vary by lender, borrower experience, property, and exit. Lendmire is a mortgage broker, not a lender.
This is the part first-timers miss. Hard money is asset-based, short-term bridge financing. On Lendmire’s network, terms run 6 to 18 months, interest-only, and underwriting looks at the property, the plan, and the exit. All of that varies by lender, property, and experience, and nothing here is a commitment to lend.
Side-by-Side
The table compares each tenant type on how a long-term rental loan typically reviews the file. The stranger column reflects published industry norms. The relative column varies by program.
| Factor | Stranger tenant | Relative tenant |
|---|---|---|
| Review basis | Property rent vs. full payment | Same ratio; rent credit may be questioned |
| Core documents | Lease, deposit, payment proof | Same, plus clearer payment trail and market-rent support |
| Property types | 1-4 unit residential | Same; household occupancy is a separate issue |
| Entity vesting | Lease unconnected to LLC members | LLC does not cure the relationship |
| Program eligibility | Standard | Allowed with proof in some programs, excluded in others |
| Reserve expectations | Set by lender, leverage, loan size | Same; added scrutiny can narrow the lender menu |
| Timeline | Standard review | Added explanation steps possible |
Where the Tenant Actually Matters
The flip loan is Phase 1. The lender reviews the deal, not the tenant. The property is typically vacant and under renovation, and flip lenders commonly require non-owner-occupied, business-purpose use.
Phase 2 is an exit by sale. No tenant is involved. For a first-timer, that is the cleanest path.
Phase 3 is the exit by refinance into long-term financing. Many investors refinance out of hard money into long-term DSCR financing once the property is stabilized, and Lendmire brokers that path. The property needs to be rent-ready, because these loans do not fund rehab. An executed lease and proof of rent paid are standard documents, and the appraiser gives a market rent opinion. Qualification runs primarily on property-level rental income covering the payment, subject to lender guidelines. Our complete DSCR loans guide covers how that ratio is built.
Seasoning, the ownership period before a refinance, is lender policy. Across most of the network, about six months is the common expectation on a cash-out. It is a clock the exit lender sets, not a regulator.
What the Law Says About Relatives
No federal rule bars a relative tenant on a business-purpose loan. The restrictions come from lender guidelines and the affidavits borrowers sign at closing.
Federal law does define a bona fide tenant, though, and that definition explains why lenders get cautious. Under the Protecting Tenants at Foreclosure Act, a lease counts as bona fide only if the tenant is not the mortgagor or the mortgagor’s child, spouse, or parent, the lease was an arm’s-length transaction, and the rent is not substantially below fair market rent. The Federal Reserve’s supervisory letter CA 18-4 lays out the three-part test, and the OCC’s Comptroller’s Handbook on the act repeats it.
Keep this in proportion. That statute protects tenants after foreclosure. It is not a DSCR rule. It is simply why family leases look like not-arm’s-length deals to an underwriter. The statute names only parents, children, and spouses, so whether a cousin, sibling, or in-law counts depends on each program’s guideline.
When a Stranger Tenant Is the Better Fit
Pick the stranger when the goal is a standard file. Reasons:
- The lease is arm’s-length by default, so there is no related-party question to answer.
- The payment trail is unconnected to the borrower or the LLC members.
- Rent follows the market, so the lease rent and the appraiser’s market rent tend to line up.
- Lenders in the network can generally review it without needing a related-party program carve-out, though guidelines vary by program.
- A first-timer already has a thin track record. One fewer explanation item helps.
Say a first-timer finishes a rehab, signs an unrelated tenant at market rent, and keeps the deposit and payment records clean. That file has the documents a rental lender expects. The coverage ratio can then be judged on the property alone. A strong ratio opens better leverage tiers, but it still sits inside the credit floor, reserve rules, and property eligibility.
One caution for any tenant type. A DSCR ratio compares rent to the full payment (principal, interest, taxes, insurance, and any HOA dues). Clearing 1.00 is not positive cash flow. Repairs, vacancy, management, and utilities sit outside the calculation.
When a Relative Tenant Is the Better Fit
Pick the relative when the placement is real and the paperwork can prove it. Reasons it can work:
- A relative in a separate household, on a written lease at market rent, is a legitimate arrangement in programs that allow related-party leases.
- A trusted tenant can protect a freshly renovated property.
- A separate payment trail and a clear move-out date show the lease is a real rental.
- Rent set at market, backed by comparable rents, keeps the income number defensible.
Here’s the catch. Underwriting typically uses the lower of the lease rent and the market rent. Family rent set well below market will pull the number down. Some programs exclude related-party leases outright, and no lease overrides that exclusion. Where a program allows them, a strong file protects the rent figure rather than inflating it.
Entity vesting does not fix it either. Programs look through an LLC to the members and guarantor standing behind it. Subject to program terms, an LLC borrower with a tenant tied to a member still gets a related-party review.
The bigger trap is occupancy. A relative living in the borrower’s household makes the property owner-occupied, and that is ineligible for business-purpose investor financing. A separate household is a gray zone that each program decides on its own. Also remember the signed occupancy and business-purpose statements are the basis for the loan. An undisclosed relationship found late hurts the file.
A Short Tax Note
Tax treatment varies; consult a qualified professional.
The Decision Rule for a First-Timer
Run these checks in order:
1. Choose the exit lender first. Read its related-party tenant rule before the hard money loan closes. Hard money and long-term lenders are different underwriters, and a plan that clears one can fail at the other.
2. If the program excludes related parties, use a stranger. Nothing in the lease fixes that.
3. If the program allows a relative, document market rent with comparables and keep a separate payment trail.
4. If the relative would live with you, stop. That is owner occupancy.
5. If the lease is informal, month-to-month, or expired, sign a fresh one before submission. Those are weak files with either tenant type.
6. If you cannot explain the tenant relationship in one sentence on the application, use a stranger.
Also keep roles straight. A relative who is the tenant is not the same as a relative who is a partner or investor in the flip. Experience offsets run through partners, credit, and cash in the deal, and a first-timer can lean on those regardless of who rents the finished unit. Lendmire’s piece Hard Money Gap Funding vs Partner for a First-Time Flipper covers that choice.
Where the Verdict Lands
For most first-time flippers, the stranger is the safer default, because it removes a question the lender would otherwise ask. The relative is a workable choice only when the exit program allows related-party leases and the rent and payment trail hold up on paper. Neither tenant type changes the hard money approval. First-timers typically qualify at the lower leverage tiers on the network, and leverage varies by lender, property, and experience. The tenant decision is an exit decision, so make it before the loan, not after the rehab.
If you are buying, rehabbing or refinancing an investment property on a short timeline and want to see how the numbers work, Lendmire can help you compare hard money options based on the project, the exit plan, leverage, and your goals.
Frequently Asked Questions
Does a hard money lender care who my tenant is?
Usually not at closing. The property is typically vacant during the rehab, and the lender weighs the deal, the budget, the after-repair value, your cash and credit, and the exit. Tenant identity becomes relevant when a long-term lender reviews the lease at the exit.
Is renting to a relative illegal on a business-purpose loan?
No federal rule names a tenant type for these loans. The limits come from program guidelines and the affidavits you sign. Some programs allow related-party leases with documentation, and others exclude them.
Can an LLC get around a related-party rule?
Generally not. Programs look through the entity to the members and guarantor behind it. Related-party treatment usually follows the people, not the vehicle.
What if my relative lives with me?
That makes the property owner-occupied, which is ineligible for business-purpose investor financing. A relative in a separate household is reviewed under each program’s own rule.
What if I charge a relative less than market rent?
Underwriting typically uses the lower of the lease rent and the market rent, so the lower figure drives the coverage ratio. Rent far below market also looks like a non-arm’s-length deal.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets — 40 states plus Washington, D.C. Because deals are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders; it is not a direct lender. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. OCC Comptroller’s Handbook, Protecting Tenants at Foreclosure
This article is part of Lendmire’s hard money loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Can an Investor Get a Hard Money Loan Without Verifying Income? · Can a First-Time Flipper Change Title Before Closing a Hard Money Loan? · Can You Get a Hard Money Loan With No Down Payment?
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.