
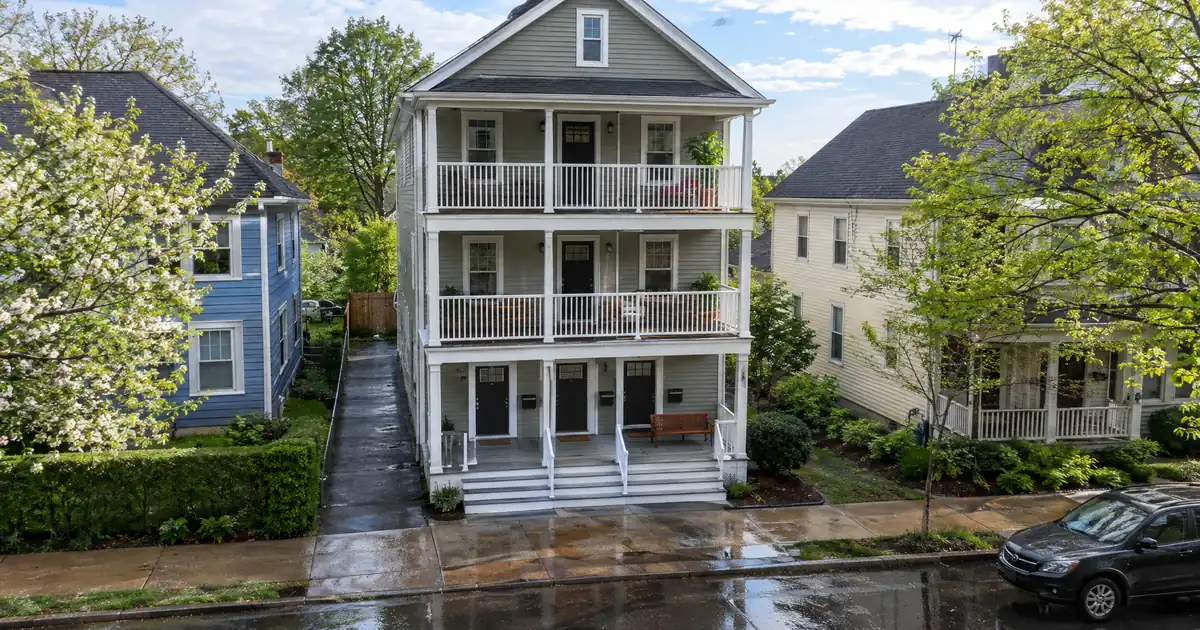
The Quick Read: If you will live in one of the units, the minimum is 5% of the price, or of the appraised value if that is lower. That is the standard path for a duplex, triplex or fourplex that gets an automated approval. The 3% option applies to one-unit homes only. If you will not live in the building, the minimum jumps to 25%, because occupancy sets the leverage.
The Short List
- Live in one unit: 95% loan-to-value (LTV), so 5% down, on a two- to four-unit principal residence.
- Don’t live there: 75% LTV on two to four units, so 25% down.
- Unit count: a duplex, triplex and fourplex share the same 95% ceiling on the standard path.
- Above 80% LTV: mortgage insurance applies. It can come off later.
- Rent helps you qualify: rent from the other units can count. Rent from your own unit cannot. Each figure is subject to lender guidelines and a complete review of property type, leverage, and credit.
What Counts as a Conventional 2-4 Unit Loan?
A conventional 2-4 unit loan is a mortgage on a building with two, three or four separate living units. You buy the building and live in one unit. Tenants rent the rest.
Conventional payment estimate
The starting figures are an example price at the first-time buyer’s minimum down payment. Replace them with yours.
Editable benchmark: 7.32% as of October 22, 2026 · Freddie Mac 30-year average via FRED®. A conventional market reference, not a conventional loan quote.
Estimate seeded at the low end of Fannie Mae’s published range (0.58%–1.86% a year); the insurer prices the actual premium on the score and the leverage. Applies only above 80% loan-to-value.
Illustrative starting assumptions: a $350,000 price, the first-time buyer’s minimum down payment, a thirty-year term at the current Freddie Mac benchmark, mortgage insurance at the low end of Fannie Mae’s published range, and property taxes and insurance estimated at typical national rates. Every field is editable.
Illustrative estimate only — not a Loan Estimate, approval, quote, or commitment to lend. The rate field carries the weekly Freddie Mac thirty-year conventional benchmark, a market reference and not a conventional loan quote; your rate is set by the lender at lock. The mortgage insurance figure is an editable estimate seeded from Fannie Mae’s published typical range, not a premium quote; the insurer prices the actual premium, and the cancellation month assumes scheduled payments with no extra principal and no change in value. Taxes, insurance and dues are editable estimates; closing costs are not included. Conforming loan limits apply by county. Licensed in sixteen states for consumer mortgages.
Lenders treat that as a home purchase, not a rental purchase. You are the occupant, so the loan gets owner-occupied terms. Those terms are better than anything offered to a buyer who plans to rent every unit.
Lendmire arranges these files through wholesale lenders, and the details sit on its conventional loan programs page. The mechanics below come from those files. Every figure is subject to lender guidelines and full file review. None of it is a commitment to lend.
How Is the Down Payment Underwritten, Step by Step?
The down payment comes out of a sequence of checks, and each one can move the number. Here is the sequence as it plays out on a real file.
1. You declare occupancy. You tell the lender you will live in one of the units as your principal residence. That single answer picks the leverage tier: 95% for two to four units, or 75% if you will not live there.
2. Automated underwriting runs. The lender feeds your credit, income, assets and the property into the agency’s automated system. The 95% tier is built for files that receive an automated approval.
3. The loan is compared to the county limit. Each county has a conforming loan limit that rises with unit count. A loan above the baseline for its unit count is a “high-balance” loan. Those carry lower leverage caps, so you put more down. Above the top limit, you are in jumbo territory.
4. An appraisal is ordered. Two- to four-unit buildings need a full appraisal that includes the rent schedule. Waivers that skip the appraisal are not available on this property type.
5. The lender measures the down payment. It uses the lesser of the price or the appraised value. If the appraisal comes in under your contract price, you cover the gap in cash.
6. Your funds are sourced. Down payment, closing costs and reserves all need a paper trail. Reserves are the savings left over after closing. The automated system sets them, and they tend to run higher on larger buildings.
7. Mortgage insurance and pricing are layered on. Above 80% LTV, insurance applies. The lender’s pricing also reflects credit score, unit count and LTV. Two- to four-unit properties carry their own adjustment, per the Fannie Mae Eligibility Matrix, which also lists the maximum LTV for each occupancy and unit type.
Think of it as a funnel. Occupancy sets the ceiling. The appraisal sets the base. Everything else decides how much cash you hold back.
Does the Down Payment Change by Unit Count?
On the standard automated path, no. A two-unit, three-unit and four-unit principal residence all top out at 95% LTV. Older guidance tiered the requirement by unit count, which is why many web pages still say a fourplex needs far more down than a duplex. That tiering has been replaced. Leverage, reserves, and pricing vary by lender and program; the final terms follow the full file review.
| Property | You live there | You don’t live there |
|---|---|---|
| Duplex | 95% LTV (5% down) | 75% LTV (25% down) |
| Triplex | 95% LTV (5% down) | 75% LTV (25% down) |
| Fourplex | 95% LTV (5% down) | 75% LTV (25% down) |
| One-unit home | 95% (97% first-time buyer, fixed rate) | 85% LTV |
The bottom row explains a common mix-up. The 97% option, which means 3% down, is for a one-unit principal residence with a fixed rate when at least one borrower is a first-time buyer. A duplex doesn’t qualify for it. Here, 5% is the floor. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Picture two buyers eyeing the same fourplex-class building. One plans to live in a unit. The other plans to rent all four. The first puts down 5% of the price. The second puts down 25%, which is 20 percentage points more, for the identical building. Occupancy alone explains the difference. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
What Does a Small Down Payment Do to Mortgage Insurance?
Mortgage insurance is required once you borrow more than 80% of the value. On a 5% down 2-4 unit loan, you will pay it. Fannie Mae’s consumer guidance says private mortgage insurance is usually required when you put down less than 20%. It also says the coverage can be removed later.
It is a monthly cost folded into your payment, and the published typical annual premiums run from 0.58% to 1.86% of the loan balance. That is a range, not a quote. Your actual figure depends on your credit score, your down payment and the file.
Here is how it ends:
- You can ask the servicer to cancel it once the balance reaches 80% of the original value. You need a good payment history, no second liens and no drop in value.
- The servicer must end it automatically at 78%, under the Homeowners Protection Act. The Consumer Financial Protection Bureau explains those cancellation and termination rights.
Unlike the insurance on some government-backed loans, this one is not permanent. Weigh the trade honestly, though. A lower down payment keeps cash in your pocket, but it adds a monthly cost until you build equity.
How Does Rent From the Other Units Count?
Rent from the units you don’t occupy can help you qualify. Rent from the unit you live in cannot. The Fannie Mae Selling Guide states that income from the owner-occupied unit can’t be used to qualify.
The lender estimates net rent from the other units, usually using the appraiser’s rent schedule and any leases. Then it adds that figure to your qualifying income. Your full housing payment, including principal, interest, taxes, insurance and any association dues, still counts as a debt. So rent does not cancel the mortgage on paper. It improves your ratios.
Here is the practical effect. On the automated path, the total ratio ceiling is 50% of income. Without counting rent, a fourplex payment can push a buyer over that line. With rent from three units added to income, the same buyer may sit comfortably under it, subject to the lender’s review. Rent helps most when your own income is modest.
Tenants who haven’t signed leases yet don’t help much. Lenders want documentation, not hopes.
Where Does the 5% Rule Break?
The rule holds on a clean, automated, conforming file. It bends in several named cases.
High-balance loans. If your loan exceeds the county baseline for its unit count, the leverage cap drops below 95%. In a high-cost county, a large duplex or fourplex can ask for meaningfully more down than 5%. Look up your county’s limit before you fall in love with a price.
Manual underwriting. When automated underwriting won’t approve the file, a human underwriter reviews it by hand. The 95% tier does not carry over. Manual files also use tighter ratios, 36% or 45% of income, depending on the reserve and score factors in the Eligibility Matrix. The credit floor can rise too, on some adjustable-rate files.
Cash-out refinances. The 95% tier is for purchases and limited cash-out refinances. If you later pull equity out of a two- to four-unit principal residence, the maximum is 75% LTV. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
You don’t occupy. One sentence covers it: occupancy decides the leverage, so a non-occupant 2-4 unit purchase is capped at 75% LTV. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Income-limited programs. HomeReady and Home Possible match the 95% ceiling on 2-4 units. They add an income limit of 80% of area median income. Some versions have extra conditions for larger buildings, so one program’s sheet won’t match another’s. Ask your broker which version applies.
Non-occupant co-borrowers. A parent or relative who won’t live there can sometimes co-sign, but program rules differ on 2-4 units. Some programs allow it. Others don’t. Check before you plan around it.
Lender overlays. A wholesale lender can set rules stricter than the agency’s. Some set a higher credit floor than the 620 decision score our wholesale conventional programs start at. This is why two lenders can give different answers on the same file. It is also a reason to work with a broker who can compare several.
Accessory dwelling units. A backyard cottage on a one-unit home is not a 2-4 unit property. Different rules apply, and the 5% tier isn’t the point there.
What Does the Decision Look Like in Practice?
Most buyers fall into one of four situations. Find yours.
| Your plan | Leverage tier | What to expect |
|---|---|---|
| Live in one unit for the long haul | 95% LTV | 5% down, mortgage insurance |
| Live there now, move out later | 95% LTV at purchase | Occupancy is a promise you must keep |
| Rent all the units | 75% LTV | 25% down, no owner-occupant terms |
| Income under the program limit | 95% LTV (HomeReady / Home Possible) | Extra income and program conditions |
The “move out later” row deserves a plain word. Lenders expect you to move in and live there as your home. If your plan at closing is to never occupy the building, say so. Stating that you will occupy it when you won’t is misrepresentation, and it can carry serious consequences. Talk about your real plans up front, because the right loan type depends on them.
Run a mental check before you shop. Your cash need has three parts: the down payment, the closing costs, and the reserves the lender wants left in your account afterward. Many buyers budget only for the first. The 5% minimum is the entry ticket, not the whole price of admission.
Then look at the gift-fund question. Some programs let relatives gift part of the down payment on a principal residence. The lender will want a gift letter and a paper trail showing where the money came from. Plan for that early.
One more point is the trade-off between down payment and mortgage insurance. Putting more down shrinks the insurance burden and gets you to the 80% mark sooner. Putting less down keeps cash for repairs, a vacancy or the reserves. There is no universally right answer. A buyer with thin savings and a strong rent roll may reasonably choose 5%. A buyer with cash to spare and a tight monthly budget may choose more.
Key Terms Defined
Loan-to-value (LTV): the loan amount divided by the lesser of price or appraised value. A 95% LTV means 5% down. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
High-balance loan: a conforming loan above the county baseline limit for its unit count. It carries lower leverage caps.
Reserves: savings you still hold after paying the down payment and closing costs. Lenders count them as a safety cushion.
Mortgage insurance: a monthly charge that protects the lender when you borrow more than 80% of the value. On a conventional loan, it can be removed later.
Principal residence: the home you live in as your main address. Occupying one unit of a 2-4 unit building qualifies.
Manual underwriting: a loan reviewed by a person instead of an automated system. It uses tighter limits.
Frequently Asked Questions
Can I buy a fourplex with 5% down?
Yes, if you will live in one unit and the file gets an automated approval within conforming limits. The ceiling is 95% LTV, so 5% down is the minimum, not a promise. Credit, ratios, reserves and the appraisal all still have to work, and everything stays subject to lender guidelines.
Does a duplex qualify for the 3% down option?
No. The 97% leverage option is for one-unit principal residences with a fixed rate when at least one borrower is a first-time buyer. Two- to four-unit buildings cap at 95%, so the minimum is 5% down. A lender may still offer a different income-limited program, but the same 95% ceiling applies. Terms depend on the lender’s guidelines, the property type, the leverage, and a full review of the credit profile.
What if the appraisal comes in below my contract price?
The lender measures your down payment against the lesser of price or appraised value. If the appraisal is lower, the loan amount shrinks with it. You can cover the difference in cash, renegotiate with the seller, or walk away if your contract allows it. Ask your agent how your contract handles this before you sign.
Is “conventional means 20% down” true?
No. Twenty percent is the point where mortgage insurance is generally not required, per Fannie Mae. It is not a minimum. On a 2-4 unit home you will occupy, 5% down is allowed, and you pay mortgage insurance until you reach 80%.
Can I count rent from the unit I live in?
No. Income from the owner-occupied unit generally can’t be used to qualify. Rent from the other units can count toward your income, though the full housing payment still counts as a debt. That is why rent improves your ratios without erasing the payment.
Next Step
If you are buying a home and want to see whether a conventional loan fits your file, Lendmire can help you compare the options and what each one asks of the file. A broker can run your occupancy plan, credit and cash through several wholesale lenders and show you where the 5% rule holds for your purchase.
For your own numbers, request a scenario review with Lendmire.
About Lendmire
As a mortgage broker (NMLS# 2371349), Lendmire helps homeowners and home buyers in 16 states with FHA, VA, conventional and jumbo purchase and refinance loans arranged through wholesale lenders. Lendmire is never the lender; program terms are set by the lender and the agency guidelines. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your home or investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Fannie Mae Eligibility Matrix
2. Fannie Mae, What to Know About PMI
3. CFPB, PMI cancellation and termination guidance
4. Fannie Mae Selling Guide, Rental Income
This article is part of Lendmire’s conventional loan program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Homeready Requirements on a 2-4 Unit Conventional Loan · Conventional Loan Down Payment Rules for a 2-4 Unit Primary Home · Minimum vs Larger Down Payment on a Conventional Loan
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.