Super Jumbo DSCR Loans In Rosemary Beach: What The Rental Must Earn
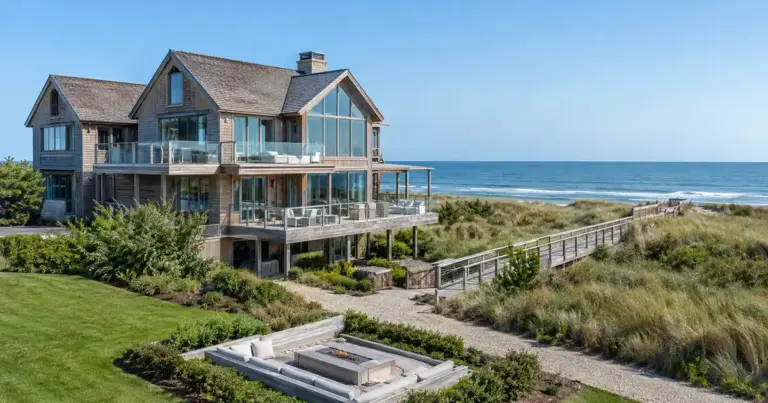
Rosemary Beach’s pricing, with median list prices running in the high-$2 million to mid-$3 million range, puts most homes there squarely in that territory.

 Lendmire Research
Rosemary Beach’s pricing, with median list prices running in the high-$2 million to mid-$3 million range, puts most homes there squarely in that territory.
Jumbo status depends purely on loan size (above the conforming limit), while non-QM depends on how income is documented — they’re separate, unrelated axes.
Most borrowers who need this product don’t lack money. They lack a W-2 that proves it.
Instead of averaging two years of tax returns, the lender reviews bank deposits, a profit-and-loss statement, or liquid assets to size qualifying income.
It’s an input the underwriter reviews, not a decision the CPA makes.
It applies to sales, cash-out refinances, and large lump-sum paydowns during that window.
As the balance climbs, leverage steps down, credit floors step up, and reserve requirements grow.
The lender pools the rent from every property, compares it to the combined payment, and lends against the group instead of one asset.
It’s built for people who have real wealth but thin reported income — retirees, business sellers, and high-net-worth borrowers.
What Is A Personal Guaranty On A DSCR Loan: what investors need to know about large-balance DSCR financing, from Lendmire.
On a mortgage, it isn’t its own category. Lenders treat it based on the paper trail it leaves: W-2, K-1, or corporate tax return.
A strong property can carry a weak one. A vacant unit or a soft lease doesn’t sink the file on its own — the pool’s total cash flow is what gets tested.
Lenders average the deposits, apply an expense factor to business accounts, and use the result as qualifying income.
Without one, selling a single property inside a blanket loan can force a payoff of the entire pool.
You buy with cash, close, then refinance shortly after — pulling out capital based on what you actually spent, not on the property’s new appraised value.