How To Navigate Two Appraisals On A High-balance Bank Statement Mortgage
It usually means a desk or field review checking the first report’s math, and if the two numbers disagree, underwriting sizes the loan to the lower figure.

 Lendmire Research
It usually means a desk or field review checking the first report’s math, and if the two numbers disagree, underwriting sizes the loan to the lower figure.
Pick 24 months when your income is steady or seasonal and a longer average tells a calmer story.
The P&L statement supports the income side of the file.
1099 Consultant Need A CPA Letter — No, not as a blanket rule.
If the loan is an adjustable-rate structure, the rate can also reset on its own separate schedule.
It rarely pays off when the lower payment is the only reason the property works today.
Divisor: the number of months a program divides your eligible assets by. A shorter divisor produces a bigger monthly income number from the same asset pool.
That second step is almost never a duplicate site visit. It’s usually a desk-level collateral review that checks the first appraisal’s math and comps.
Platform payouts count as income once they’re traceable and recurring — a monthly Stripe or Airbnb deposit reads differently than a single unexplained wire.
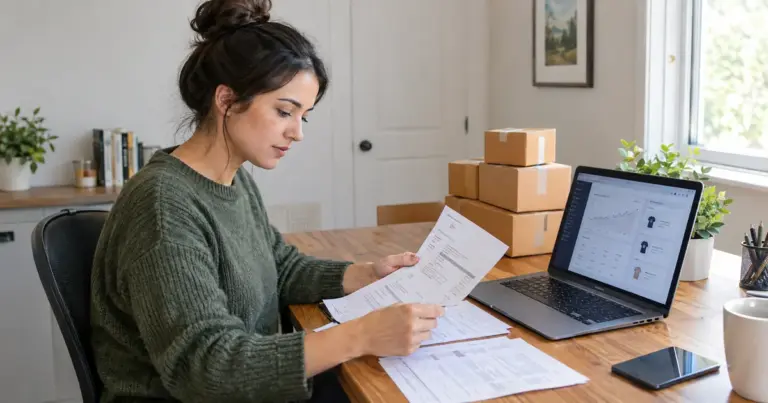
Amazon Seller Use A Business Account — Yes, a business account works for a bank statement loan, but it changes the math.
The IO period never lowers total interest owed; it only delays when principal reduction starts.
Asset Haircuts And Divisors Change Your Asset Qualifier — Yes.
Two separate appraisers value the property, and the lender uses the lower of the two numbers to set the loan-to-value calculation — never an average.
The condo project has to pass warrantability review. A seller-carried second lien has to fit standard subordinate-financing rules.
The tradeoff is documentation depth — 12 to 24 months of statements, a clean deposit pattern, and a lender who can actually follow the money.