Super Jumbo DSCR Loans In Arkansas: Complete Guide
There’s no federal definition of “super jumbo” — it’s shorthand the industry invented, and every lender draws the line somewhere different.

 Lendmire Research
There’s no federal definition of “super jumbo” — it’s shorthand the industry invented, and every lender draws the line somewhere different.
The lender checks whether the rent covers the payment and works down from there.
This guide walks through the mechanics, the size ladder, and the edge cases that trip up otherwise strong deals.
There’s no legal definition of “super jumbo” — it’s an industry term for balances well past the conforming loan limit and past standard DSCR caps.
At higher price points the mechanics don’t change conceptually, but leverage steps down, credit floors rise, and appraisal scrutiny gets heavier.
Loan amounts in Lendmire’s wholesale network commonly run up to $5,000,000, with larger deals handled by exception.
Financing A Ski Chalet With Bank Statements — A ski chalet purchased with bank statement income involves two separate decisions, not one.
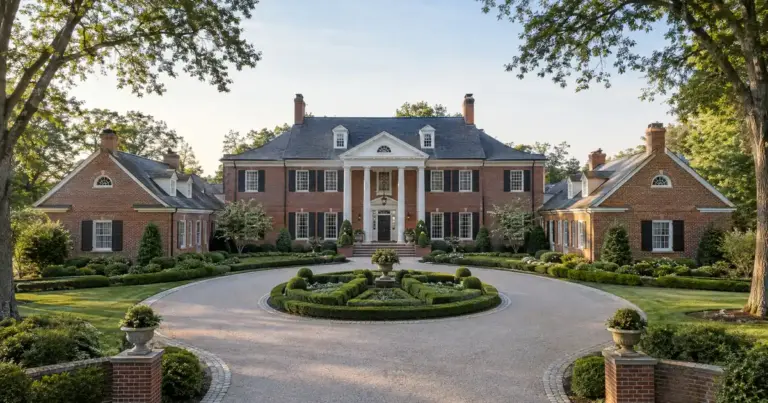
Once a loan crosses that line it’s jumbo by definition, and once it climbs well past it, DSCR lenders start calling it super jumbo.
Leverage steps down as the loan size climbs, and every file above $4,000,000 goes through case-by-case review before it’s even submitted.
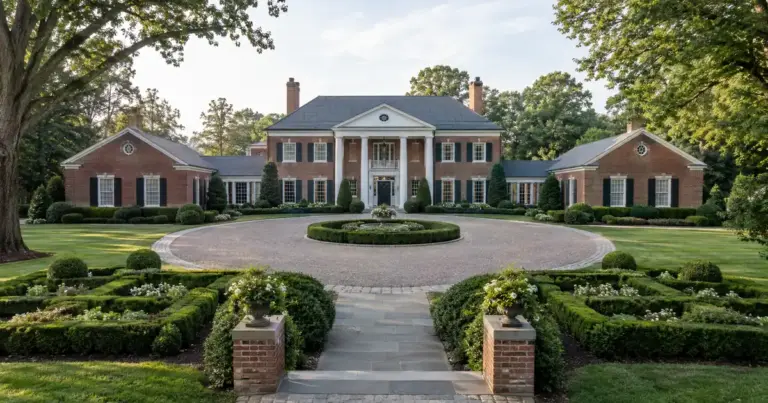
Underwriting runs on the property’s value and the investor’s exit plan, not a paycheck.
Above roughly $4,000,000, every file gets individual underwriter review before it’s even submitted.
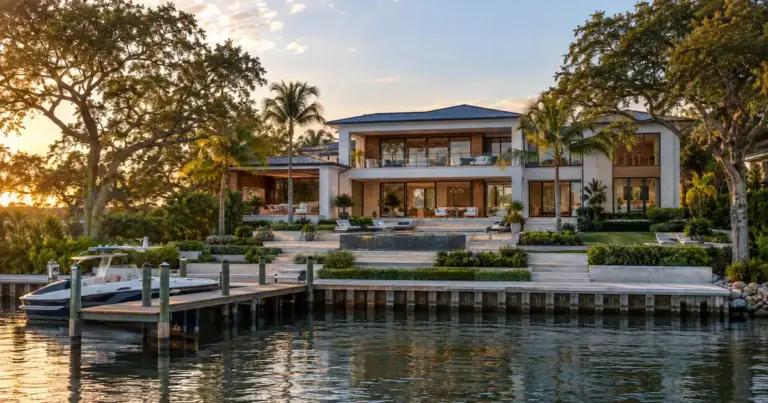
A DSCR loan qualifies the property’s rent, not your personal debts, so a yacht loan payment generally never enters the math.
The property’s rent — not your tax returns — drives qualification, and coverage, credit, and reserves all move together at scale.
Leverage steps down as the balance climbs, and every file above roughly $4 million gets reviewed case by case before it’s submitted.