When Does a Loan Officer Need Bank Statements?
On an alt-doc bank statement loan, the ask is heavier: 12 months of statements become the income calculation itself.

 Lendmire Research
On an alt-doc bank statement loan, the ask is heavier: 12 months of statements become the income calculation itself.
Lenders average your deposits, apply an expense factor, and lend against that income figure.
Which bucket you’re in depends entirely on why the lender is asking, not on some universal rule.
On a rental-property DSCR loan, bank statements don’t verify your paycheck; they verify your cash to close and your reserves. That’s the short version.
How Heavy Do Bank Statements Weigh In On Loan Approval — it depends entirely on which loan you’re using.
Do Loan Companies Verify Bank Statements — Yes, every legitimate lender reviews the bank statements you submit.
Do Loan Underwriter Need To Approve Bank Statements — Yes.
Lenders strip out transfers and one-time deposits, apply an expense factor to business accounts, and average what’s left into a monthly income figure.
Is There Any Loan Organization That Can Verify Income With Bank Statements — Yes.
Coverage — how many months of history the statement shows — is a separate question from freshness.
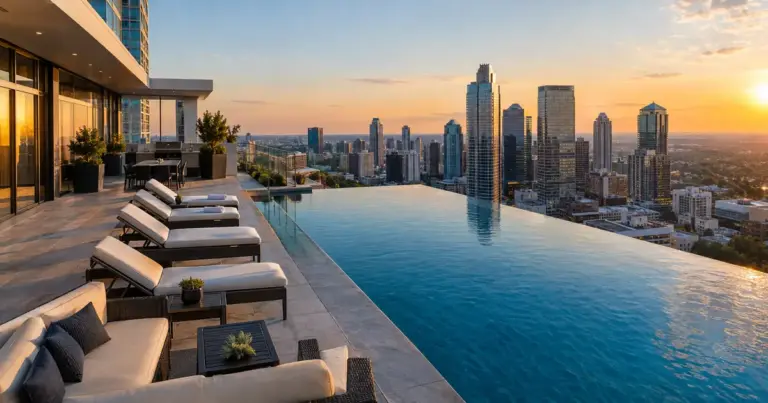
Financing A High-rise Condo With Bank Statements: Complete Guide: what borrowers need to know about high-net-worth bank-statement financing, from Lendmire.
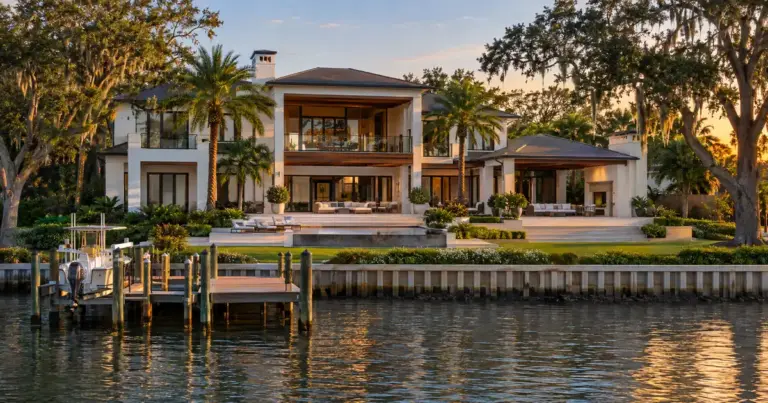
Naples’ median sale price recently ran near $1.2 million, according to Redfin, pushing most luxury purchases straight into non-conforming territory.
Banks and credit unions can do this, and non-QM/portfolio lenders built entire product lines around it.
Through select lenders in Lendmire’s wholesale network, loan sizes run from $300,000 to $30,000,000 across two overlapping programs.
Leverage steps down as the balance climbs, and Louisiana’s property tax homestead break never applies to a rental.