
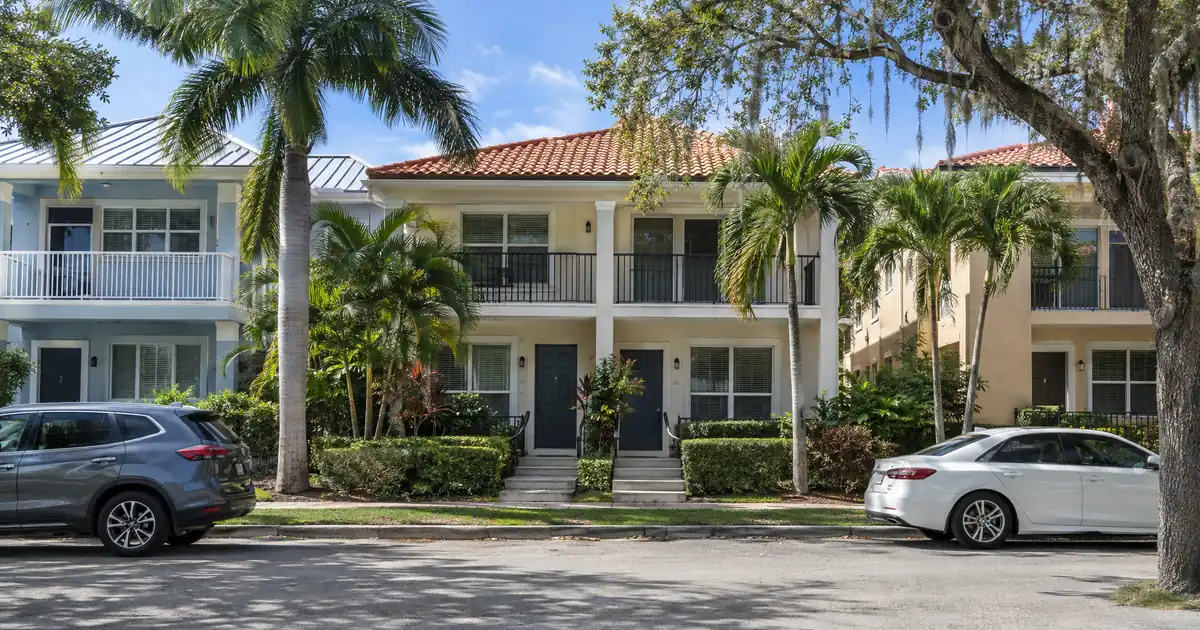
An appraisal is the first place a cash-out refinance goes wrong. The rent can be solid and the borrower’s credit clean, and a value that lands 5 percent lower still shrinks the loan ceiling before anyone discusses proceeds. In a market where Zillow puts the average home value at $278,711, down 5.0 percent over the past year, that risk is the starting assumption for any cash-out refinance investment property plan in Hallandale Beach, Florida. Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker, works with Hallandale Beach, Florida investors through a DSCR program footprint spanning 40 states plus Washington, D.C.
The Short Version: A DSCR cash-out refinance in Hallandale Beach, Florida fits investors who already hold seasoned condos, townhomes, or scarce small multifamily and want equity redeployed. The loan is underwritten primarily on the property’s rental income against its full monthly obligation, and proceeds are capped by appraised value, not by what the owner paid.
DSCR Cash-Out Calculator
Run the cash-out numbers in Hallandale Beach, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Condos and townhomes dominate: 998 listed at a median of $310,000.
- Single-family is a thin, pricier pool: 57 listings at a $649,900 median.
- Cash-out LTV tops out at 75 percent, after about six months of ownership.
- Rents are drifting lower while new apartment supply leases up nearby.
- Condo project eligibility is the practical gatekeeper here.
Hallandale Beach Market Snapshot
A quick read on the Hallandale Beach investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $2,100–$4,200 asking rents (The Real Deal) |
| Vacancy | 4.6% (Miami Finance Review) |
The Appraisal Is the Whole Game
Falling values compress cash-out proceeds faster than rents help coverage. The 75 percent LTV ceiling applies to appraised value, so every point of price softness comes straight out of available equity, while a rent decline hits the coverage number from the other side.
Run the numbers on a hypothetical owner with an existing lien at 65 percent of the property’s original value. If the appraisal comes in 5 percent lower, that same lien is about 68.4 percent of the new value. Headroom under the 75 percent cap drops from 10 points to roughly 6.6. That is a third of the equity gone without a single missed payment.
The pricing sources look contradictory, but they measure different things. Zillow’s blended figure mixes property types. The MLS-based breakdown from PBP Real Estate splits them: condos and townhomes sold year to date at a median of $240,000 across 446 closings, and single-family sold at a median of $536,500 across 48. Cite these by property type. A blended “Hallandale median” describes almost nothing you can actually refinance.
Other parameters for planning, all subject to lender guidelines and varying by borrower and property:
- Seasoning: about six months of ownership, measured from title recording.
- Coverage: a 1.00 minimum DSCR, meaning rent used for lender review against full PITIA (principal, interest, taxes, insurance, and any HOA dues).
- Reserves: typically about six months of PITIA.
- Credit: a floor of 620, with better tiers at 660, 680, and 700.
Investors who want the mechanics can read the guide “What Is a DSCR Loan”. The rest of this piece is about where those parameters bite in Hallandale Beach.
Condos: Where the Deal Gets Decided
In Hallandale Beach the property type matters more than the borrower. With condos and townhomes making up the bulk of inventory, a cash-out file often turns on whether the project itself is acceptable to the lender’s program, not on the unit’s rent.
HOA dues sit inside the payment used for coverage, so a unit with high dues and a modest rent can fall short of 1.00 even when it looks profitable on a napkin. Some lenders in the wider DSCR market limit or exclude condo projects altogether, which narrows the field before pricing is discussed. Get the project’s questionnaire and budget in hand before ordering anything.
The lowest entry points sit in Atlantic Shores. Redfin shows a median near $175K over the last three months, down 2.8 percent, with homes averaging 76 days on market versus 136 a year earlier. Low prices suggest a higher rent-to-value ratio, and that is what a cash-out needs. But a small balance and a condo-project review make it a niche fit. It works for an owner with a clean, seasoned unit, not for someone hoping to squeeze proceeds from a $175K asset.
Golden Isles is the other name investors hear. Movoto reports a median list near $265K, which appears condo-weighted, and the gated deepwater single-family homes there are premium product. Skip it if you want rent-to-value. Waterfront single-family prices in on lifestyle, and the coverage ratios follow.
Foster Road and the Northwest Quadrant
The strongest structural case for rent stacking is the Northwest Quadrant along the Foster Road corridor, though the data is thin. This is the city’s redevelopment area, and city CRA materials describe little residential construction there in decades, plus infill like the Hallandale Beach Commons townhomes and the 89-unit City Center project.
Small multifamily is the scarce asset. Duplexes and similar properties cluster west of I-95 and in the CRA area, but no reliable price or rent series exists for 2 to 4 unit stock, so anything more precise than that would be invented. The scarcity is the argument: a landlord holding a small building where a second or third rent stream supports coverage has a structural edge over a condo owner with fixed dues. The CRA’s paint program offers up to $6,000 for multi-unit dwellings versus $3,000 for single-family, which shows the city recognizes multi-unit stock in the zone. Confirm current program terms before relying on it.
The catch: this is also the neighborhood closest to new supply, and the appraisal for a small older building will lean on comps that are thin.
New Supply Is Pulling on Rents
Underwrite to in-place leases, not to headline rents, because a large lease-up is running next door. Parks at Hallandale is a 398-unit project on Pembroke Road. Its first 100 units began welcoming residents in April, and the other 298 were expected in the summer, with asking rents running from $2,100 to $4,200 across studios through three-bedrooms. A portion of the units are designated workforce housing at 120 percent of area family income, per the developer’s workforce page.
Concessions on new product can pull achievable rents down on older units nearby. The rent data already leans that way:
- Reaction Realty Group puts the median apartment rent at $2,350 to $2,500, a 2 to 3 percent year-over-year decline, and attributes the softness to new deliveries. It is a broker blog, so weigh it accordingly. – Apartment List shows averages of $2,047 for a one-bedroom and $2,796 for a two-bedroom, with prices trending down across unit sizes. – RentCafe shows the average falling 6 percent, from $3,294 to $3,096. That covers buildings of 50 or more units only, so it describes the new-build tier, not small landlords.
The sources disagree on levels because each samples a different slice. The practical read is to underwrite to the older-stock band, not the headline averages. When the same property has a value drifting down and a rent drifting down, coverage gets squeezed from both sides. If an owner’s in-place rent lands under 1.00 on full PITIA, lenders in the network may review options such as lower leverage, stronger credit and reserves, or an interest-only structure. Eligibility stays subject to lender guidelines, credit approval, and property review.
Demand Side: Deep Renter Pool, Modest Incomes
Tenant demand is the reliable part of this market. Census Bureau QuickFacts lists a population of 41,854 in a city of just 4.2 square miles, and RentCafe’s Census-based figures show 9,147 renter-occupied households, 47 percent of the total. Median household income is about $52,340 per Florida-Demographics, which points to workforce-priced units rather than luxury product.
The employment anchors are real but unquantified. Gulfstream Park combines racing, a casino, retail, and dining, and hosts the Florida Derby. The city also sits between the Miami-Dade and Broward job centers, and residents commute both ways. No verified employer headcounts turned up, so treat these as qualitative support for hospitality and gaming-wage renters.
Near Gulfstream, the Gateway and Fashion Row area is walkable, and Reaction Realty notes demand stays strong west of the entertainment district. Three Islands is more car-dependent, with a Walk Score of 29 per Walk Score. Tenants there rent for the water, not the walk.
What the Deal Desk Sees in Markets Like This
In condo-heavy coastal markets, the common friction point is not the borrower. It is the project. Cleaner files tend to arrive with the condo questionnaire, current budget, and a signed lease already organized, and the ones that stall usually stall on HOA documentation or a lease that expired and rolled month-to-month. Investors who sequence those documents before the appraisal is ordered spare themselves a redo. The other pattern is a coverage ratio that clears on last year’s lease and misses on the renewal, so pulling the current lease first avoids surprises.
Turning Proceeds Into the Next Deal
Equity available depends on rent used for lender review, PITIA, reserves, and the 75 percent ceiling. It is never a guaranteed figure. Loan sizes run up to $3,000,000 on standard programs, and smaller balances route through select lenders in the network. For many Hallandale condos the balance will be modest, so the question is whether the extracted equity justifies the transaction. The refi options and refinance details lay out the structures.
Two honest takes. First, for an owner with a small-building position west of I-95, waiting for a stronger appraisal environment may beat forcing a cash-out at the bottom of a soft cycle. Second, a long-run case exists: The Real Deal describes Hallandale Beach as the next Broward target for towers, a branded hotel, and offices, with one broker attributing it to rising Miami-Dade and Palm Beach prices. That is opinion, and the same pipeline means new-build competition and near-term soft values. Don’t count on appraisal gains to fund the proceeds.
Entity owners should note LLC-titled borrowing is subject to lender program eligibility. For the state picture, see Lendmire’s Florida DSCR financing page. Investors comparing structures can also review the side-by-side comparison. Questions on a specific file can go to Lendmire at 828-256-2183. Verify current local rental rules, taxes, and insurance with qualified local professionals before underwriting.
Frequently Asked Questions
Does a falling Zillow value make a cash-out impossible in Hallandale Beach?
No, but it shrinks the proceeds. The 75 percent ceiling applies to appraised value, so a lower appraisal reduces available equity point for point. Owners with low existing leverage keep meaningful headroom, while those who bought near the peak or already pulled equity out may find little left.
DSCR vs. conventional financing
Two common ways to finance an investment property in Hallandale Beach, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Why do condo owners here face extra scrutiny?
Condos and townhomes make up most of the inventory, and the lender reviews the project as well as the unit. Budget health, owner-occupancy mix, and HOA dues all affect eligibility, and the dues also enter the PITIA used for coverage. Some lenders in the broader market exclude condos entirely.
Can a duplex west of I-95 support a bigger cash-out than a condo?
It can support stronger coverage, since two rent streams sit against one property payment. Proceeds still come down to appraised value and the 75 percent cap. Comparable sales for small multifamily are scarce locally, which makes the appraisal the uncertain step.
How does Parks at Hallandale affect my refinance?
Indirectly, through rents. A 398-unit lease-up with asking rents from $2,100 to $4,200 can prompt concessions that pressure older-stock rents nearby. Use in-place leases, not pro-forma rents, to size the coverage ratio.
How long must I own before a cash-out?
Programs generally look for about six months of ownership from title recording. Terms vary by lender and scenario, so confirm before planning a timeline around it.
Watchlist for the Next Quarter
- Parks at Hallandale absorption: watch whether concessions widen as the remaining units deliver. Widening concessions point to more pressure on older-stock rents.
- Condo and townhome sales medians: compare against the $240,000 year-to-date level. A stabilizing median means appraisals stop eroding your equity.
- Northwest Quadrant infill: track City Center and townhome progress, since completed workforce product is the clearest test of whether the corridor supports higher small-building values.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. DSCR eligibility is commonly reviewed by the lender on property-level rent rather than personal income documentation, subject to lender guidelines, and the brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. Lendmire was named a Top Mortgage Workplace, recognized by Scotsman Guide in 2025 and a top-ranked workplace in 2026, as covered in Lendmire’s 2026 Top Workplace announcement.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Value Index, Hallandale
2. PBP Real Estate, Hallandale Beach
3. The Real Deal, Hallandale Beach development
6. Movoto reports a median list near $265K
7. Hallandale Beach CRA Residential Programs
8. parksathallandale.com — Developer’s workforce page
10. RentCafe
13. Gulfstream Park
14. Walk Score
15. recognized by Scotsman Guide in 2025
16. Scotsman Guide — Top Workplaces 2026
17. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Hallandale Beach Florida: Access Equity Without Income Docs · Cash Out Refinance Investment Property Pompano Beach Florida · Cash Out Refinance on a Sunny Isles Beach Investment Property
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosures. The information presented in this article is general market commentary, not financial, legal, or tax advice. Lendmire is a mortgage brokerage (NMLS# 2371349) — not a direct lender or depository institution — and loan placement is subject to lender underwriting. Nothing in this content represents a commitment to lend. Loan terms, pricing, and program availability vary based on borrower qualifications, property characteristics, and state of subject property, and are subject to change at any time. Lendmire complies with Equal Housing Opportunity requirements. Consumer access: nmlsconsumeraccess.org.