
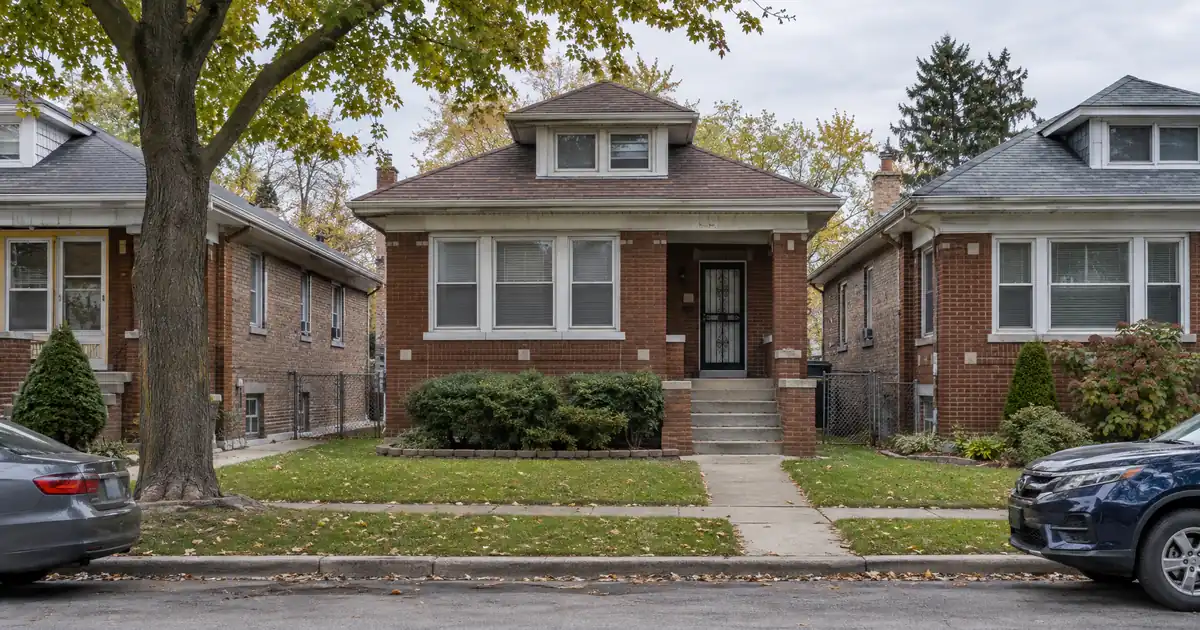
A brick two-flat in Cicero’s Clyde district, two 2-bedroom units each renting near the $1,400 that Redfin’s Clyde listings show, sits in front of a cash-out lender at 75 percent of appraised value. On a modest appraisal the coverage clears 1.0 with room to spare. Push the appraisal higher to squeeze out more proceeds, and the cushion thins fast. In Cicero the appraisal, not the rent roll, is usually where the file gets decided.
DSCR Cash-Out Calculator
Run the cash-out numbers in Cicero, IL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A cash-out refinance on a Cicero, Illinois rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the file works only if rent used for lender review covers the new payment plus taxes and insurance after the appraiser sets the value and the lender applies its loan-to-value cap.
- Cash-out is capped at 75 percent LTV, and about six months of seasoning from title recording is typical.
- Two-flats stack rent; a single-family 3-bedroom near $1,900 rent lands just under 1.0 modeled.
- Sold-price medians run roughly $275K to $310K, thin-sample data driven by 19 monthly sales.
- Pink Line blocks near 54th/Cermak carry the strongest commuter demand.
- Cicero has no district-level rent data, so underwrite from actual rent rolls.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges investor loans through wholesale lending channels, with DSCR lending in 40 states and Washington, D.C. (41 markets total). Its Illinois DSCR investor loans page covers the state-level picture. This piece covers the narrower question: what pulling equity out of an already-owned Cicero rental looks like when the comps are thin and the rents are contested.
Cicero Market Snapshot
A quick read on the Cicero investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $2,200–$2,800 (Deal Run Cicero) |
| Recent appreciation | +7.9% yoy (Rocket Homes) |
| Employment | 16,577 jobs (Redfin Cicero investment) |
Where Cicero Equity Comes From (and Where It Doesn’t)
Cicero sold-price medians cluster between roughly $275K and $310K depending on the source, and none of those figures is stable enough to underwrite as a trend. Investors should treat any appreciation claim as a hypothesis until an appraiser confirms it.
Redfin’s Cicero market page reports a $310K median sale price, up 24 percent year over year, with homes selling in about 68 days and a median of $160 per square foot. Read the footnote before the headline: only 19 homes sold in that month against 33 a year earlier. A 24 percent jump on 19 transactions is noise. Homes.com shows $275,000, up just 2 percent. Rocket Homes shows $296,835, up 7.9 percent, in a report that is now dated. Redfin’s city guide breaks it out by type: $285,000 for single-family, $230,000 for townhouses and $140,000 for condos.
Three sources, three appreciation stories. The honest read is that Cicero prices have probably firmed, but the pace is unknowable from public data. An investor who bought a two-flat well below those medians and has held it past seasoning has real equity to work with. An investor who bought near the top of the range and is counting on a 24 percent lift is gambling on an appraiser.
Context helps. Redfin’s Chicago page shows a $426K median, which puts Cicero roughly $115K to $150K below the city next door. That gap is the structural argument for owning here: entry pricing that leaves room for rent to carry a loan. It is not an argument that the gap will close on any schedule.
What Six Months of Seasoning Buys
Cash-out on an investment property in Cicero follows the standard DSCR structure: about six months of ownership measured from title recording, a 75 percent LTV ceiling, rent used for lender review of at least 1.0 against the full monthly obligation, and reserves near six months. All of it is subject to lender guidelines and property review.
The 75 percent ceiling is the number people misjudge. It is a hard cap on cash-out, lower than the purchase-side limit, and it applies to the appraised value, not the price paid. Equity available is whatever remains after the existing payoff, the 75 percent cap, the reserve requirement and the coverage test. It is not a guaranteed cash figure. Credit tiers on the programs Lendmire places run from a 620 floor up through 660, 680 and 700, with better tiers generally supporting stronger terms. Standard programs go up to $3,000,000; smaller balances route through select lenders in the network. Review details are subject to lender overlays, and Lendmire’s refi programs lay out the structure in more detail.
The seasoning clock matters more in Cicero than in deeper markets. Buy a distressed two-flat, rehab it and refinance at month seven, and the appraiser still has to justify the after-repair value from a comp set that may include three or four closed sales within a mile. Investors who buy below market and season the full period generally give the appraiser less to argue with.
The Coverage Math on Three Property Types
Two-flats are where the coverage math holds; single-family homes at median rents sit at or just under 1.0; condos depend entirely on HOA dues. The figures below are modeled assumptions, not sourced market data, and each includes full taxes and insurance on a 30-year structure at 75 percent LTV.
Start with the rent inputs, because the sources disagree. Zumper shows a $1,200 median across all unit types, up 4.3 percent, with 2-bedrooms at $1,400 and 3-bedrooms at $1,900. RentHop is higher, showing $1,800 for 2-bedrooms and $2,200 for 3-bedrooms, but its median of active listings is $1,250. Several other portals show averages well under $1,000, which appear skewed toward older apartment stock and are not used here. Underwrite off Zumper’s figures, since RentHop’s 2-bedroom number likely reflects newer or renovated inventory.
| Property type | Modeled rent | Modeled coverage |
|---|---|---|
| Two-flat, $300K value | $2,200-$2,800 combined | About 1.0 to 1.3 |
| Two-flat, $350K value | $2,800 combined | About 1.1 |
| SFR 3BR, $285K value | $1,900 | Just under 1.0 |
| Condo, $140K value | Not sourced | HOA-dependent |
Run the numbers on the two-flat first. A modeled $300K appraised value with a combined $2,800 in rent covers the full monthly obligation about 1.3 times. Drop combined rent to $2,200 and the number falls to about 1.0. That $2,200 to $2,800 band comes from a broker marketing page that describes it as typical for a two-flat, so treat it as unverified and test it against a real rent roll. Now stretch the appraisal to a higher modeled value and hold rent at $2,800: coverage drops to about 1.1, because a larger loan balance grows faster than rent does. That is the appreciation-versus-cash-flow tension in one line. Maximizing proceeds and maximizing coverage pull in opposite directions.
The single-family case is weaker. A 3-bedroom at $1,900 against a $285K value lands just under 1.0 with taxes and insurance in. Not disqualifying, but not clean. Where a file falls under 1.0 on long-term rent, a lender may review a sub-1.00 program, an interest-only structure or lower leverage, each with its own trade-offs on pricing and cash out. Qualification stays subject to credit approval and property review. The DSCR fundamentals page walks through how the ratio is built.
Condos are the cheap entry at that $140K median, but HOA dues sit in the obligation, and they can erase whatever spread a low price creates. Skip any condo file where dues are not documented up front.
Can the Appraisal Carry the Cash-Out?
Probably, on a well-bought asset; not reliably on a stretched one. Cicero’s comp depth is the binding constraint on cash-out proceeds, more than rent or credit.
Redfin’s investment-property page counted 55 multi-family units for sale against 5 condos and 2 townhouses, with 19 homes sold in the past month and typical days on market near 60. Homes.com shows 32 multi-family listings. Note the mismatch: those are listings and this is closed sales, so the two counts are not strictly comparable. Even so, the pattern is clear. Multi-unit inventory is deep enough to build a two-to-four-unit strategy on, while the closed-sale record that supports appraisals is thin.
Thin comps produce conservative appraisals. When an appraiser compares a two-flat to single-family sales because few two-flat comps exist, the resulting value can undershoot the income approach. Plan for a lower value than the headline medians imply, and size the refinance so that a value 5 to 10 percent lower still leaves the file above 1.0 and the payoff covered. (Investors who model only the optimistic appraisal tend to find out at the worst moment.)
Honestly, this one is a toss-up on the borderline files. A rehabbed two-flat with documented leases and clean rent history may appraise strongly; the same building with month-to-month tenants and verbal rents may not. Documentation quality often separates the two outcomes.
Pink Line Blocks, MacNeal and the Commuter Tenant
Cicero rental demand depends on regional job access more than on local employment, which makes proximity to the Pink Line and expressways the main screening variable. Redfin puts Cicero at about 83,505 residents and 16,577 jobs, roughly one local job for every five residents.
Most tenants therefore commute out. Census Bureau QuickFacts shows a 2024 ACS population of 82,093 and a mean commute of 29.3 minutes, consistent with a Chicago-bound workforce. The CTA Pink Line is the transit anchor: the 54th/Cermak terminus logged 502,100 boardings and the Cicero Avenue station 258,487 in the latest reported year, per Wikipedia’s station entry citing CTA data. The Metra BNSF station at 26th and Cicero is a minor factor, with only 136 average weekday boardings in dated figures. Underwrite around the Pink Line and CTA bus access, not commuter rail.
Local employers add a floor under demand without moving it much. Industrial operators south of I-290, including an Amazon fulfillment center, Corey Steel and Frank Korinek & Co., plus the Cermak and Cicero Avenue retail corridor with Walmart and Sam’s Club, are named in Homes.com’s local guide. No verified headcounts were found, so treat them as qualitative. The town began as a manufacturing hub, as the Town of Cicero notes; Western Electric’s Hawthorne Works once employed a peak of 45,000. Today’s economy is logistics, light industrial and retail.
Two institutional anchors round it out. Morton College enrolls roughly 3,500 to 3,900 students depending on the source, which is why U.S. News shows 3,618 and other directories differ. And Loyola MacNeal Hospital, a 374-licensed-bed teaching hospital, sits just east in Berwyn as part of Loyola Medicine. Healthcare employment next door does not swing with manufacturing cycles, which supports steady renter demand within commuting distance.
Clyde, Hawthorne and Cermak: Districts Without Data
Cicero’s eight named districts are real submarkets with no reliable public rent or price data, so the honest approach is to underwrite each block from its rent roll. The Town of Cicero lists them: Grant Works, Hawthorne, Warren Park, Drezel, Clyde, Morton Park, Boulevard Manor and Parkholme.
What can be said with support is thin. The Clyde-area 2-bedroom listing at $1,400 is a single snapshot. Berwyn 2-bedrooms nearby ask $2,000 to $2,450, though several look like newer or amenitized buildings, so the comparison is imperfect. If Cicero’s older two-flats price no higher than Berwyn’s but the rent gap is even partly real, there is a rent-to-value edge worth verifying with a rent survey. Verify before underwriting to it.
Adjacent-area medians per Redfin’s guide do not describe Cicero: South Berwyn at $360,000, South Lawndale at $345,000, the Southwest Side at $280,000 and the West Side at $464,500. They show where nearby capital is flowing. They do not tell an investor what a Hawthorne two-flat appraises for.
Location anchors help sort blocks. The Cermak Road corridor is the retail spine. Hawthorne sits near 22nd Street and Cicero Avenue, close to the old Works site. Morton College sits along Central Avenue. Blocks within walking distance of the Pink Line stops have the clearest commuter case; blocks deep in the grid away from both transit and Cermak are harder to defend. Cicero is densely built out, about 85,000 people in 5.87 square miles at roughly 14,500 per square mile, so new land supply is not the risk. Stale rents and thin comps are.
What the Deal Desk Tends to See
The friction point in dense inner-ring markets like this one is rarely the credit file. Lendmire’s deal desk sees the cleaner files come in with a written lease for every unit, proof of rent deposits and a rent figure that matches what the appraiser’s rent schedule will support. Files stall when owner-reported rents run well above the appraiser’s market rent, because qualifying income is generally anchored to the lower of lease or market. Investors on two-flats who refresh leases before applying give the file a much steadier footing.
Where Cash-Out Doesn’t Pencil
Skip the setups where the equity is theoretical. Three patterns stand out.
- Recent purchases priced at the top of the range. If the basis sits near the top of local values and seasoning has barely elapsed, the headline appreciation is doing all the work, and the sample behind it is thin.
- Single-family at the median rent. When median rent is set against a typical local value, modeled coverage falls well below 1.0. Only the 3-bedroom rent tier gets near the line.
- Max-proceeds refinances on marginal coverage. Taking the full available leverage when the file barely clears 1.0 leaves no cushion for a vacancy or a repair.
Investors should also verify current local rental rules, property taxes and insurance costs with qualified local professionals before underwriting. Those were not compiled here.
DSCR vs. conventional financing
Two common ways to finance an investment property in Cicero, IL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Recycling the Proceeds
The point of the refinance is capital for the next acquisition, and the discipline is not to let one over-extended two-flat fund another marginal one. Proceeds go into a down payment, a rehab or a reserve account on the next property, so the second file needs to work on its own coverage, not on the assumption that the first stays flat.
A reasonable framework: refinance at a leverage level that leaves the first property comfortably above 1.0, and treat the extra 5 points of LTV you could have taken as insurance, not as lost capital. That is the same logic behind the refi options Lendmire lays out for seasoned holders. For readers weighing this against a bank product, the side-by-side comparison covers the underwriting differences. Investors ready to test a Cicero two-flat can reach the team at 828-256-2183.
Frequently Asked Questions
How much equity can I pull from a Cicero two-flat?
It depends on the appraised value, the existing payoff, the 75 percent LTV cap, reserves and whether rent covers the new obligation at 1.0 or better. There is no fixed figure. On thin-comp blocks the appraisal is usually the limiting factor, so a conservative value estimate is the safer planning base.
Does six months of ownership really apply if I rehabbed the building?
Seasoning is generally measured from title recording, and the standard guideline is about six months. Rehab work can support a higher appraisal, but lender guidelines on renovation and recent purchases vary, so the file should be reviewed with the lender before the clock is assumed to be met.
Which Cicero districts have the best rent-to-value numbers?
No public source breaks out rent or price data for Cicero’s eight districts, so no honest ranking exists. The stronger screening variable is proximity to the Pink Line stations and the Cermak corridor, combined with a documented rent roll on the specific building.
Should I trust the 24 percent price increase in the headline data?
No. It rests on 19 monthly sales against 33 a year earlier. Other portals show 2 percent and 7.9 percent, so the trend is unclear. Underwrite to the low end of the $275K to $310K range and let the appraisal prove otherwise.
Do condos work for a Cicero cash-out?
Only when HOA dues are low and documented. The $140,000 condo median is attractive on price, but dues sit inside the full monthly obligation and can push coverage below 1.0 even when the purchase looks cheap.
Cicero’s thin comps and contested rents reward the investor who documents every lease, seasons the full period and sizes the refinance for a cautious appraisal, so the ones who do that before applying will come out ahead.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage focused on DSCR investor financing, helping arrange programs through wholesale and investor-lending channels in 41 markets, including Washington, D.C. DSCR loans are evaluated by the lender on property cash flow rather than personal income, subject to lender guidelines, supporting LLC closings and accommodating investors with four or more financed properties. Scotsman Guide Top Mortgage Workplace in both 2025 and 2026.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. dealrun.ai — Find Buyers Cicero IL
3. Rocket Homes
4. Redfin, Cicero investment property
5. Redfin, Cicero housing market
6. Homes.com
9. Zumper, Cicero rent research
10. RentHop
11. Homes.com — Cicero IL Multi Family Homes for Sale
16. Loyola Medicine, MacNeal Hospital
17. recognized by Scotsman Guide in 2025
18. a 2026 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Cicero Illinois · DSCR Cash Out Refinance Evanston Illinois · Cash Out Refinance Investment Property in Tinley Park, Illinois
Guides: Investment Property Cash-Out Refinance in Cicero, IL · Investment Property Cash-Out Refinance in Illinois
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.