
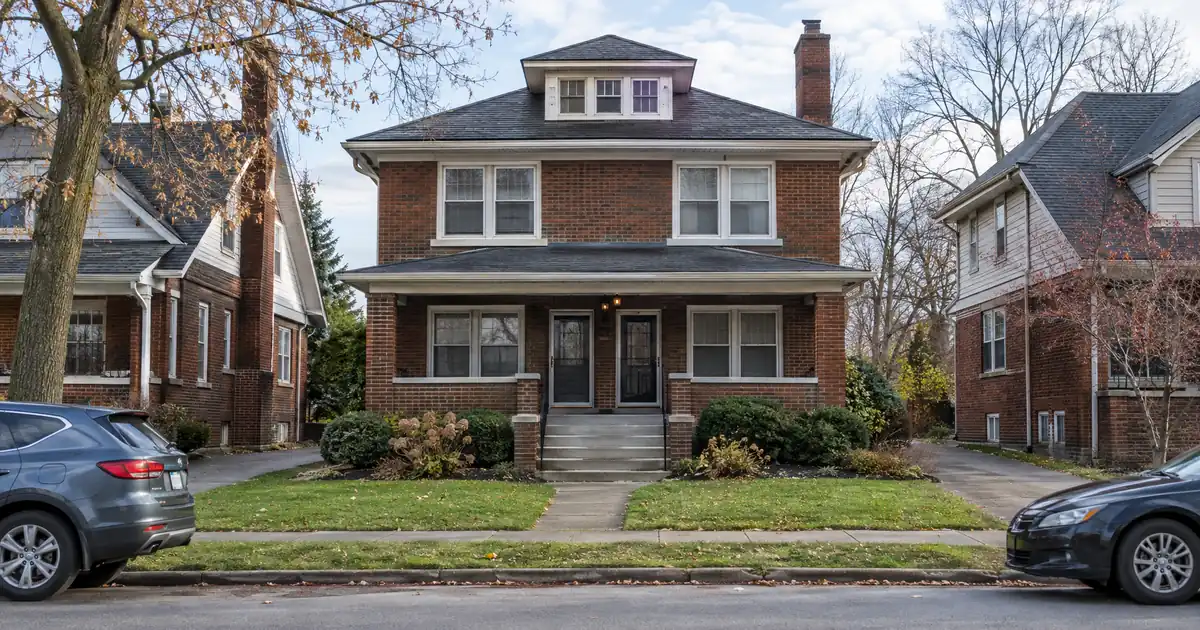
A cash-out in Euclid starts from a low appraisal base, and the 75% LTV ceiling applies to whatever the appraiser concludes the property is worth. Redfin puts the median sale price near $160K, up 12.9% year over year. That is small in absolute terms, so each point of appraisal movement matters more to the size of the draw than it would in a pricier market. For Euclid, Ohio rental property financing, Lendmire (NMLS# 2371349) helps arrange DSCR loans through lenders operating in 41 markets, including Washington, D.C. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
DSCR Cash-Out Calculator
Run the cash-out numbers in Euclid, OH
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Quick Read:
In Euclid, Ohio, a DSCR cash-out refinance is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the appraisal setting the value and the 75% LTV ceiling setting the borrowing limit on that value. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
- Cash-out LTV tops out at 75%, and about 6 months of ownership is typical for seasoning.
- Redfin shows a $160K median sale price, up 12.9%, with median days on market at 37.
- Homes.com shows a $1,522 median asking rent for houses, well above the Census median gross rent of $1,065.
- Duplexes fit best, but Redfin showed only 9 multi-family units for sale in a recent month.
- Older stock means appraisal condition adjustments matter as much as headline rent.
Euclid Market Snapshot
A quick read on the Euclid investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $126,500 median value (Data USA) |
| Typical rents | $1,650 median (Zumper) |
| Population | 52,000+ population (City of Euclid) |
| Employment | About 12,000 employees (2022) (Lincoln Electric) |
What the Appraiser Actually Sees
Euclid’s numbers are best read as a range, not a point. Redfin’s $160K median sale price is the canonical figure used here. Movoto reports $155,000 for a different window, and Data USA shows a median property value of $126,500, up 10.3%. The Data USA figure is Census-based and owner-reported, so it runs below actual sales. All three point the same direction: low entry basis, rising values.
Rising values are the point of a cash-out. A property bought several years ago at a lower basis may now appraise meaningfully higher, and that gap between old basis and new value is the equity a 75% LTV draw taps. Sales dispersion is the counterweight. Redfin’s recent snapshot showed closings from $26,000 for a small 2-bed to $165,000–$205,000 for 3–4 bed homes. Wide dispersion means comp selection can swing the appraised value by tens of thousands of dollars. Same house, different comps, very different proceeds. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
That shapes the strategy. An owner who renovated to a clean standard has a better argument to the appraiser than one whose comps include distressed sales. Whether the appraisal supports the draw depends on lender guidelines and property review.
Rent Side: Asking Numbers Versus Underwritten Numbers
Homes.com lists a median asking rent of $1,522 for homes in Euclid, and Apartments.com shows a $1,621 average for houses. Against a roughly $160K price, that is a strong gross rent-to-value relationship. Treat it as an indicator, not a study: the sources mix property types and measure asking rents, not signed leases.
The conservative counterpoint is city-data.com, which shows Census median gross rent of $1,065. It includes older, lower-rent leases across all unit types. Apartment rents sit lower still, at $597 for a studio and $844 for a one-bedroom per Rent.com. The takeaway is that house and duplex-unit rents run roughly double small-apartment rents, so rent comps built from apartments will understate what a house can earn. Lenders review rent through the appraiser’s market-rent schedule or the lease in place, and either can land below asking.
Here is a modeled illustration, not sourced market data. Assume a workforce 3-bed appraising near $160K and a rent between $1,300 and $1,522. Including taxes and insurance in the full obligation, and borrowing at the 75% LTV cap, coverage lands roughly between 1.2x and 1.4x. The 1.00x benchmark is the common baseline because rent covers the obligation at that level. Some lenders may review lower ratios, but usually with lower leverage, more cash, or stronger compensating factors.
| Property type | Modeled value / rent | Coverage read (with taxes, insurance) |
|---|---|---|
| Workforce 3-bed house | ~$160K / $1,300–$1,522 | Roughly 1.2x–1.4x |
| Side-by-side duplex | ~$249,900 / $2,200–$3,000 | Roughly 1.3x–1.8x |
The duplex row uses a Lake Shore Blvd corridor listing near $249,900 and an illustrative pairing of unit rents from about $1,100 to $1,500 each. Round-down math, one-off listings, modeled inputs. Real files will differ.
Why Duplexes Carry the Coverage
Two rent streams under one loan is the cleanest DSCR structure in this market. Income from both units is combined into one calculation, so a vacant unit does not sink the ratio the way it would on a single-family rental. Lenders differ on how they treat a vacant unit at appraisal, so that is worth raising early.
The catch is inventory. Redfin noted just 9 multi-family units for sale in a recent month, so an investor hoping to buy a second duplex with the proceeds will face competition. This is a genuine toss-up for anyone planning a repeat strategy: the coverage favors 2–4 unit product, but supply favors the more plentiful single-family houses. Small apartment complexes and 5+ unit buildings along Lake Shore Blvd usually fall to commercial or multifamily underwriting, not standard 1–4 unit DSCR programs, so verify eligibility with a lender before counting on them.
Where the Equity Sits: Submarkets
Lake Shore Blvd corridor (ZIP 44123 and 44119). The corridor mixes single-family homes and apartments near the lakefront, and it is where the duplex product concentrates. ZIP 44123 3-bed houses are listed for rent at roughly $1,300 to $1,550 per Rent.com, while similar 3-beds are listed for sale near $155,000 to $160,000 per Movoto. That works out to a gross monthly rent of about 0.8%–1.0% of price. It is arithmetic on separate listings, not a published ratio. Cleveland Clinic Euclid Hospital sits on the Lake Erie shoreline here as a demand anchor.
ZIP 44132 (northeast Euclid). This is the appreciation-supported pocket for cash-out purposes. PropertyIQ reports a $154K median home value, up 8.4%, with homes selling in a median of 53 days. Rising values feed the appraisal directly. The trade-off is a slower sale pace than the citywide 37-day median, so an appraiser may lean on fewer recent comps.
The lakefront and downtown. The City of Euclid is tying Lake Erie to the central business district, with retail, residential, and restaurant development anticipated and a marina planned. SmithGroup says roughly 95% of the nearly five miles of shoreline was private before the plan, and the project has delivered a public pier and a three-quarter-mile trail. It also helped secure more than $13 million in funding. Long-term appreciation upside is plausible but unquantified. Do not underwrite to it.
Neighboring comps (not Euclid). South Euclid is a separate city, but it works as a benchmark: Redfin shows a $195K median there, and Zumper a $1,650 median rent. Euclid’s price sits well below that. The Cleveland-side Euclid-Green neighborhood shows a $90K median. Neither is Euclid, so use them for context only.
Demand Anchors and What They Mean for Holding Period
Euclid’s two largest industries are manufacturing and healthcare, according to the city’s annual financial report, and it is home to the world headquarters of Lincoln Electric. Data USA counts about 23.7k employed residents, led by health care and social assistance at 4,757, retail trade at 2,721, and manufacturing at 2,609. Population sources conflict, so “roughly 48,000 to 52,000” is the honest range; the U.S. Census Bureau is the authoritative reference. The city sits about 15 minutes northeast of downtown Cleveland.
AreaVibes reports the number of renter-occupied households is 50% higher than the national average, which supports deep renter demand. The Euclid hospital campus is a stable anchor rather than a growth catalyst, though Cleveland Clinic’s Main Campus expansion about 15 minutes west is expected to add 2,000 employees, per NEOtrans. Steady healthcare and manufacturing employment argues for long-term leases, which is what a cash-out refinance is built around.
Working DSCR brokers see a recurring pattern in older inner-ring markets like this one: the rent looks fine on paper, and the file stumbles on the appraisal, not the coverage. Condition adjustments on pre-1970 stock pull value down, and the draw shrinks with it. Owners who document updated systems and use well-matched comps before ordering the appraisal tend to have the smoother review.
That stock issue is real here. NeighborhoodScout reports 64.19% of housing was built between the 1940s and 1960s, and single-family detached homes are 54.01% of units. Budget for systems, and expect the lender to look hard at condition.
The Mechanics of the Draw
Program guidance typically runs as follows, subject to lender guidelines and property review:
- LTV: cash-out tops out at 75%, and the draw depends on rent used for lender review, the full monthly obligation, reserves, and that ceiling. It is never a guaranteed figure.
- Seasoning: about 6 months of ownership, measured from title recording.
- Credit and reserves: a 620 floor, with better tiers at 660, 680, and 700, and reserves of about 6 months of PITIA.
- Coverage: 1.00x is the standard baseline.
Loans to LLC-titled entities are common for portfolio holders, subject to lender program eligibility. Anyone weighing this against a traditional loan can read Lendmire’s DSCR-versus-conventional breakdown, and Lendmire’s DSCR walkthrough covers how coverage is calculated. For structure options, including rate-and-term and cash-out refinancing, see the refi options. Lendmire’s Ohio DSCR platform sets out the statewide picture. Investors should verify current local rental rules, taxes, and insurance with qualified local professionals.
Anyone with a seasoned Euclid property can request a scenario quote or call 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Euclid, Ohio?
The file is reviewed on the property’s rent against its full monthly obligation, with a 1.00x baseline typical. The loan must also fit under the 75% LTV cap, and the borrower needs roughly 6 months of ownership, a 620 minimum credit score, and about 6 months of reserves. Final eligibility depends on lender guidelines, appraisal, and credit review.
What are the requirements for an investment property loan in Euclid, Ohio?
Expect a property in a reviewable 1–4 unit category, documented rent, adequate reserves, and a qualifying credit score. Manufactured homes, log homes, and barndominiums fall outside these programs. Older Euclid stock invites close attention to condition at appraisal.
Does a duplex help an Euclid cash-out more than a single-family rental?
Usually yes on coverage, because two rents are summed into one calculation. The trade-off is thin inventory when reinvesting the proceeds, and lenders may price or cap 2–4 unit properties more conservatively than single-family. Single-family houses carry easier resale and more available comps.
DSCR vs. conventional financing
Two common ways to finance an investment property in Euclid, OH. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Which Euclid areas look strongest for a cash-out appraisal?
ZIP 44132 shows the clearest recent momentum, with a $154K median value up 8.4%. The Lake Shore corridor offers the stronger rent-to-value pairing and more duplex product. Neither is guaranteed to appraise well, so comp quality matters more than the ZIP code.
What documents matter most for an Euclid DSCR cash-out review?
Leases or a market-rent appraisal, proof of ownership and seasoning, and reserve statements carry the most weight. Lendmire arranges DSCR investor loans and the review centers on property income rather than traditional personal-income documentation.
Two Ways to Play the Draw
The real decision for an Euclid owner comes down to two paths. One is to pull equity now against a modest appraisal, using the 75% ceiling and a clean 1.2x-plus coverage read, and redeploy it into another sub-$160K rental before prices rise further. The tradeoff is a smaller draw and a larger share of the next deal funded by a single appraiser’s comp choices. The other is to hold another year or two and let lakefront work and steady healthcare and manufacturing employment build the appraisal, at the cost of leaving equity idle while duplex inventory stays this thin.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
As a DSCR and non-QM mortgage broker, Lendmire (NMLS# 2371349) connects investors with wholesale lending channels across 41 markets, including Washington, D.C. The property’s rental income, not the borrower’s traditional personal-income documentation, is central to lender review, an approach that suits self-employed operators and portfolios beyond four financed properties. The firm was recognized by Scotsman Guide as a 2025 Scotsman Guide Top Workplace and recognized by Scotsman Guide as a 2026 Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Euclid housing market
2. Redfin
4. Zumper
7. Movoto
8. Homes.com
10. city-data.com
11. Rent.com
12. Rent.com
13. Movoto
14. Cleveland Clinic Euclid Hospital
15. PropertyIQ
16. City of Euclid: Waterfront Improvements Plan
17. SmithGroup
18. City of Euclid 2024 Annual Comprehensive Financial Report
19. U.S. Census Bureau QuickFacts: Euclid
20. AreaVibes
21. NEOtrans
23. a 2025 Scotsman Guide Top Workplace
24. recognized by Scotsman Guide as a 2026 Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Ohio
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.