
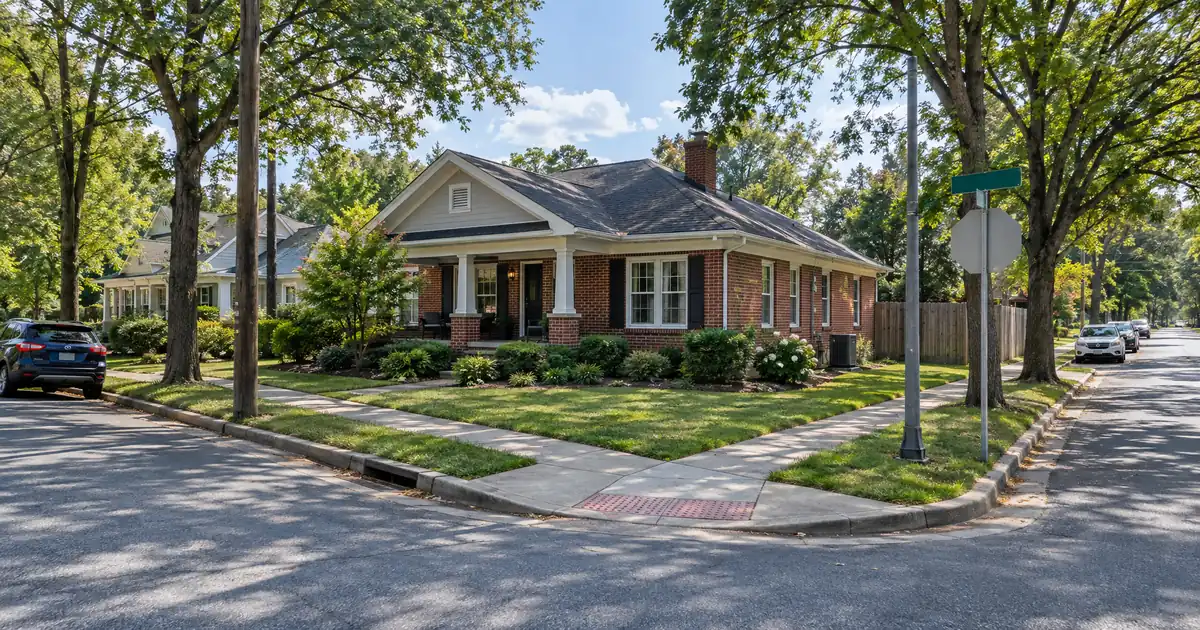
Matthews home prices climbed 7.0% year over year, with a Redfin median sale price of $535K, while Zillow shows average rent up just $6 over the prior year and tags the rental market “COOL.” That gap between price and rent decides almost every cash-out conversation in this Charlotte suburb. Owners here are sitting on equity, but the rent doesn’t always carry a big loan against it.
For real estate investors in Matthews, North Carolina, Lendmire (NMLS# 2371349) helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. This piece covers the equity-extraction side: what a cash-out can realistically pull from a Matthews rental you already own, and where the coverage number gets tight.
DSCR Cash-Out Calculator
Run the cash-out numbers in Matthews, NC
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
Key Takeaways:
A DSCR cash-out refinance on a Matthews, North Carolina rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the loan sized against current value. Proceeds depend on rent used for lender review, reserves and a 75% LTV ceiling, not on appreciation alone. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
- Single-family rent-to-value runs about 0.42% here, per Homes.com rent against the Redfin median.
- Full-leverage cash-out on a median-priced house lands well under 1.00x coverage.
- Townhomes, at a lower basis, are the likelier fit for the coverage ratio.
- Rents are flat to down, so size the refinance on today’s rent.
- Seasoning runs about 6 months from title recording on typical programs.
Matthews Market Snapshot
A quick read on the Matthews investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $445,100 median value (Data USA, Matthews) |
| Typical rents | $1,516 asking (Matthews Real Estate Investment) |
| Cap rates | 5.0% cap rate (Matthews Real Estate Investment) |
| Employment | ~40,000 system employees (Business North Carolina, Novant) |
| Vacancy | 6.2% (Matthews Real Estate Investment) |
Where the Cash-Out Math Breaks
Full-leverage cash-out on a median-priced Matthews house doesn’t clear 1.00x. Rent against value runs well under half a percent monthly, based on the median rent and median sale price figures published by Homes.com and Redfin. Include taxes and insurance and the coverage number sits well below the benchmark.
Run the numbers on a modeled single-family rental valued at $535K, using a modeled rent of $2,252. At 75% LTV, coverage on full PITIA (taxes and insurance included) comes out around 0.7x. Not close. Drop leverage toward the 45-50% range and the ratio approaches 1.00x, but that cuts the proceeds you came for. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
Below 1.00x isn’t automatically a dead end. Some lenders review sub-1.00 programs, interest-only structures or lower-leverage tiers, usually with stronger credit, bigger reserves and closer file review. Whether any of it fits depends on lender guidelines, credit approval and property review. It just isn’t the clean 75% pull that a cheaper charlotte submarket might offer.
Matthews is an appreciation-led market, not a cash-flow one. If your equity came from price growth and you need the cash for the next acquisition, expect to right-size the loan to the rent. How the qualification works is simple: monthly rent divided by the full monthly obligation, with a 1.00x baseline common across standard programs.
The Equity Is Real. The Rent Growth Isn’t.
Rents around Matthews are soft right now, and underwriting should assume no recovery. Apartment List shows a $1,498 overall median rent, down 5.2% year over year, though it still runs 14.3% above the Charlotte metro median. Appraisers and lenders often set market rent conservatively on a refinance, so a lease signed at a high number may not carry the file.
The metro backdrop points the same way. The Matthews Real Estate Investment Services Charlotte multifamily report (a brokerage with no relation to the town) shows 6.2% vacancy and a $1,516 average asking rent, down 3.2% year over year. More than half of Charlotte apartment properties are offering concessions. Those concessions compete directly with small Matthews rentals.
There is good news underneath. Northmarq reports about 4,800 net move-ins in its latest quarter, a peak for the region, and expects vacancy to hold steady as supply pressure eases. Its earlier report ties renter demand to roughly 30,000 jobs added over two years. Rent growth is forecast to turn modestly positive, around 1.8%. That’s a forecast. Don’t size a loan against it.
The price side is murkier. Redfin’s $535K and a local agent’s roughly $481K median (an agent view, showing a balancing market) disagree on both level and direction. Treat the honest range as roughly $480K to $535K, and expect an appraiser to land somewhere inside it.
Townhomes Are the Better Basis
Townhomes are the lower-basis rental product in Matthews, which makes them the likeliest place for rent to cover a cash-out. Redfin’s townhouse page lists 54 townhomes for sale at a $405K median listing price, about $130K under the single-family sale median. New infill here tends to arrive as townhomes, with Sycamore Trail starting in the $300,000s, per Real Property Management Value.
Here’s the catch. That’s a listing snapshot, and I can’t point to a sourced townhome rent band. A lower basis only helps if rent drops proportionally less than price. Pull actual townhome lease comps before you assume coverage.
The same Redfin page shows most Matthews homes for sale sitting around 114 days. Good news for buyers with negotiating room. Less good if you need to unwind a refinance through a sale. Matthews is also largely built out, so limited new supply supports the comp base for existing rentals, though that source is a property manager’s description and should be treated qualitatively.
Duplexes are the best-supported small multi-unit type, since the town’s ordinance recognizes two-family buildings. But stock isn’t abundant, and there’s no sourced count. Triplexes and fourplexes? Don’t count on finding them here. Charlotte’s nearer-in submarkets carry more of that inventory, and Matthews isn’t a fourplex market.
Submarkets Worth Pulling Comps In
Focus on the corridors where renters actually concentrate: downtown, NC-51 and the Idlewild Road area. Per-submarket prices and rents aren’t available from reliable sources, so treat this section as tenant-base guidance, not pricing.
Historic Downtown and Trade Street. Loft-style homes and townhomes around the rail-town core draw young professionals who want walkability. This is the most distinctive rental story in town, and the place where a cash-out on a well-located attached unit is most likely to hold up on comps. The depot dates to the railroad’s arrival in 1874, and the town’s farmers market bills itself as the largest producer-only market in the Charlotte region. Lifestyle demand is real.
Idlewild Road and the CPCC Levine area. Central Piedmont Community College has a campus here, and new communities line the corridor, including a 55+ development and apartments near I-485. Renters include students and healthcare workers. No enrollment figure is available, so don’t lean on one. New product nearby can also pressure older unit rents.
NC-51 and Sycamore Commons. Larger apartment communities along this corridor serve retail and service workers and commuters. That’s a tenant base with steady employment, though apartment concessions in the wider metro keep pressure on small-rental pricing.
East John Street and the Sportsplex. Newer apartments near the Four Mile Creek Greenway. Fine for demand, but again apartment-heavy competition.
Crestdale and Brightmoor. Skip these for rental cash-out. They’re primarily owner-occupied single-family, with thin rental comps, and thin comps make a refinance appraisal harder to support.
One more local wrinkle: ZIP 28104 sits in Union County school assignment while 28105 is Charlotte-Mecklenburg, per Real Property Management Value. Treat that as a comps issue. An appraiser may find different comparable sets by ZIP, so pull rent and sale comps from the same ZIP as the subject.
The Demand Anchors (and the Transit Gap)
Hospital expansion and corporate employment carry long-term renter demand here. Novant Health’s Matthews Medical Center is adding a four-story, 150,000-square-foot tower in what Business North Carolina headlines as a $170M expansion. The system has nearly 40,000 employees overall, which isn’t a Matthews-only figure. Atrium Health runs a hospital in nearby Indian Trail, 3.5 miles from the Matthews site. Harris Teeter is headquartered in town.
Most residents commute. Data USA puts the population near 30.6k, homeownership at 64.4% and average commute at 25.2 minutes, and Census QuickFacts is the authoritative source for the current count. Uptown sits about 10 to 11 miles northwest, and Ballantyne and SouthPark draw the finance and corporate commuters. Matthews has no rail; the planned LYNX Silver Line has been slow to develop. Demand is by car along US-74 and I-485.
Furnished mid-term stays for traveling clinicians around Novant are plausible. I found no Matthews-specific data, so treat it as a thesis, not an underwriting input.
What Seasoning and the 75% Cap Mean Here
Typical DSCR cash-out programs cap leverage at 75% LTV and look for about 6 months of ownership measured from title recording. The baseline is a 1.00x DSCR and about 6 months of PITIA in reserves (more above $1,500,000). Credit tiers usually start at a 620 floor and step up through 660, 680 and 700, with better leverage and pricing at higher scores. All of it is subject to lender guidelines. The cash you can pull depends on rent used for lender review, PITIA, reserves and that LTV ceiling. It’s not a guaranteed figure.
DSCR files in markets like this one typically look the same. The appraised value comes in strong, the market rent comes in conservative, and the gap between the two sets the real leverage. Investors who go in expecting 75% often settle lower once full PITIA is counted. The files that move smoothly arrive with a lease, a rent survey and reserves documented before anyone asks.
The cash-out itself works well when the proceeds redeploy somewhere with a better rent-to-value ratio than Matthews. A Matthews owner with a $535K rental and strong equity might pull a modest, coverage-constrained amount and use it as down payment on a lower-priced charlotte-area multi-unit. The 0.42% rent-to-value here is the thing you’re trading away from.
There’s a cash-out qualification details page for the mechanics, and the refinance side covers rate-and-term comparisons. Comparing conventional and DSCR investor loans matters if you’re weighing a W-2 cash-out against a property-income one. For statewide context, see DSCR loans in North Carolina.
Where many non-QM platforms require reserves that don’t match the investor’s file, a broker can route the same property to lenders with different reserve and leverage structures. LLC-held rentals are common, subject to lender program eligibility. For a look at what a specific property supports, see what the numbers look like or call 828-256-2183.
DSCR vs. conventional financing
Two common ways to finance an investment property in Matthews, NC. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
The Next 6-24 Months
The cash-out case in Matthews will improve if the Charlotte supply glut keeps easing, but probably not dramatically. Northmarq expects vacancy to hold steady, the Matthews brokerage forecasts rent growth of about 1.8%, and Novant’s expansion should keep healthcare-adjacent demand stable. That points to a flat-rent stretch with a slow recovery, not a rebound.
The smart play for owners is to pull what today’s rent supports rather than wait for higher coverage. If rents turn positive, a later refinance captures the gain. Investors who try to stretch leverage now carry a file that depends on a rent recovery that’s only a forecast. Matthews equity will keep looking better than Matthews rent for a while yet.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Matthews?
Qualification centers on the property’s rent against its full obligation (principal, interest, taxes, insurance and any HOA dues), with 1.00x a common baseline. Lenders also look at credit tiers starting near 620, about 6 months of reserves and roughly 6 months of seasoning. Eligibility depends on lender guidelines, credit approval and property review.
What are the requirements for an investment property loan in Matthews, North Carolina?
Expect a property-income test, a credit score in the lender’s tier, reserves and title seasoning for cash-out. Loan amounts can reach $3,000,000 on standard programs, with smaller balances routed through select lenders in the network. Manufactured homes, log homes and barndominiums fall outside these programs.
Does the 28104 versus 28105 split matter for a refinance?
It can affect which comps an appraiser pulls. ZIP 28104 is in Union County school assignment and 28105 is Charlotte-Mecklenburg, so sale and rent comps may differ by ZIP. Pull comparables from the same ZIP as the property.
Can a Matthews single-family rental support 75% LTV cash-out?
These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Usually not at median prices. Rent-to-value of about 0.42% puts full-leverage coverage well below 1.00x once taxes and insurance are counted. Lower leverage, sub-1.00 programs or interest-only structures may be reviewed, subject to lender guidelines.
What loan-amount ranges may DSCR lenders review for Matthews rental properties?
Lendmire arranges DSCR investor loans. Standard programs generally run up to $3,000,000, with smaller balances routed through select lenders in the network. Final eligibility follows lender program guidelines.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage focused on investor financing, arranging DSCR loans in 40 states plus Washington, D.C. — 41 markets total. Qualification is based on the property’s income rather than personal income documentation, subject to lender guidelines, making it a fit for LLC-held rentals and scaling portfolios. The firm was recognized by Scotsman Guide as a 2026 Top Workplace and recognized by Scotsman Guide in 2025. See Lendmire’s 2026 Top Workplace announcement for details.
Investors should verify current local rental rules, taxes and insurance with qualified local professionals.
Get Started
Ready to find the right loan for you?
See your offer in seconds. No credit pull, no obligation.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Matthews housing market
2. Zillow Rental Manager, Matthews
3. Homes.com, Matthews rentals
4. Data USA
5. Matthews Real Estate Investment Services, Charlotte multifamily report
6. Business North Carolina, Novant expansion
7. Apartment List, Matthews rent report
8. Northmarq, Charlotte multifamily report
10. Real Property Management Value
11. ordinance
12. matthewsnc.gov — Farmers market
13. Central Piedmont Community College
14. Novant Health’s
15. Atrium Health
16. recognized by Scotsman Guide as a 2026 Top Workplace
17. recognized by Scotsman Guide in 2025
18. Lendmire’s 2026 Top Workplace announcement
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Matthews, North Carolina: Pulling Equity from a Thin-Rent Market · DSCR Cash Out Refinance in Huntersville, North Carolina: The 2026 DSCR Financing Guide to Birkdale Village · DSCR Cash Out Refinance in Brevard, North Carolina: How Much Equity Investors Can Pull in Brevard
Guides: Investment Property Cash-Out Refinance in North Carolina
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Legal disclosures. Lendmire (NMLS# 2371349) is a state-licensed mortgage brokerage that arranges financing through wholesale lender relationships. Lendmire is not a direct lender, depository institution, or registered financial advisor. The discussion above is general informational content about real estate financing — it is not financial, legal, or tax advice, and readers should consult licensed professionals for guidance on their individual circumstances. Loan inquiries are subject to lender underwriting; this article does not represent a commitment to lend. Loan terms, rates, and qualification standards vary by borrower, property, and state, and are subject to change at any time. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.