
One automotive plant employs about 2,000 people in a city of 13,844 residents, per Warren County Economic & Community Development and Census Bureau QuickFacts. That ratio shapes everything about a cash out refinance investment property file in Mcminnville, Tennessee. Tenant demand rests on a thin, wage-earning base, and the comp pool for valuing a rental is thinner still.
TL;DR: A DSCR cash-out refinance in Mcminnville, Tennessee is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the rent schedule and the appraised value decide how much equity comes out.
DSCR Cash-Out Calculator
Run the cash-out numbers in Mcminnville, TN
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out caps at 75 percent LTV, with about 6 months of seasoning from title recording.
- Single-family asking rents near $1,600 against list prices near $265,000 put coverage close to the 1.00x line.
- One fourplex sale at $365,000 shows a much stronger rent-to-price ratio, but it is a single data point.
- Valuation, not rent, is the likely constraint on proceeds.
Mcminnville Market Snapshot
A quick read on the Mcminnville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| University enrollment | First students July 1966 (TCAT McMinnville) |
| Employment | ~2,000 Yorozu employees (warrencountyecd.com — Warren County Economic) |
Start in the 37110 Core
ZIP 37110 is where the cash-out files here will mostly sit. Zillow’s 37110 listings show a wide band: 3-bed, 2-bath houses listed around $264,900 and $267,400, a 4-bed foreclosure at $259,900, and a historic brick house at $459,900. The spread tells you the appraiser has no clean median to lean on. Condition and size adjustments carry the value.
No reliable neighborhood-level price or rent series exists for Mcminnville. Sources give ZIP and street-level listings only, so this article treats 37110 and the secondary ZIP, 37111, as the working geography. Rental listings for houses on Couch St, Cascade Ave and Black St in 37111 ask between $1,550 and $1,895 per Zillow’s rental snapshot. Those are asking rents on a handful of listings. Treat them as a sample, not a market statistic.
Downtown and the Courthouse Square area carry older housing stock and a walkable core, per the McMinnville-Warren County Chamber of Commerce. No price data supports it, so it stays a qualitative angle. Skip the outlying rural-residential roads. Three-bed homes on acreage listed at $199,900 to $299,999 are poor rental-coverage candidates and thin on comps.
The Two Rent Numbers That Don’t Agree
Zumper puts the average Mcminnville rent at $725 and flat year over year. It also says 72 percent of available inventory is two-bedroom units. That figure describes small, older apartments. It is not a single-family comp.
Single-family asking rents sit at $1,550 to $1,895. The market splits in two: cheap apartments and pricier houses. The appraiser’s rent schedule on the subject property decides the file, not a citywide average. Underwriting a house off the Zumper number is the quickest way to build a wrong coverage estimate.
Single-Family: Close to the Line
Run the numbers on a modeled house. Assume a 3-bed, 2-bath rental that would list near $265,000 and rents for $1,600. That is a rent-to-price ratio of about 0.6 percent. Listing-derived and rough, but it is the best the sources support.
At 75 percent LTV with taxes and insurance included in the monthly obligation, coverage lands close to the 1.00x line. A 1.00x baseline is common because rent covers the payment at that level. Some lenders may review lower scenarios, but those usually need stronger compensating factors, lower leverage or more cash in. A $1,500 appraisal rent instead of $1,600 could tip the file under 1.00x.
If it tips, the file isn’t dead. Options a lender may review include a sub-1.00 program, an interest-only structure, or a lower LTV that trims the loan. Qualification stays subject to lender guidelines, credit approval and property review. Credit tiers run 620, 660, 680 and 700, with 620 as the floor, and reserves typically run about 6 months of PITIA.
The Fourplex Case
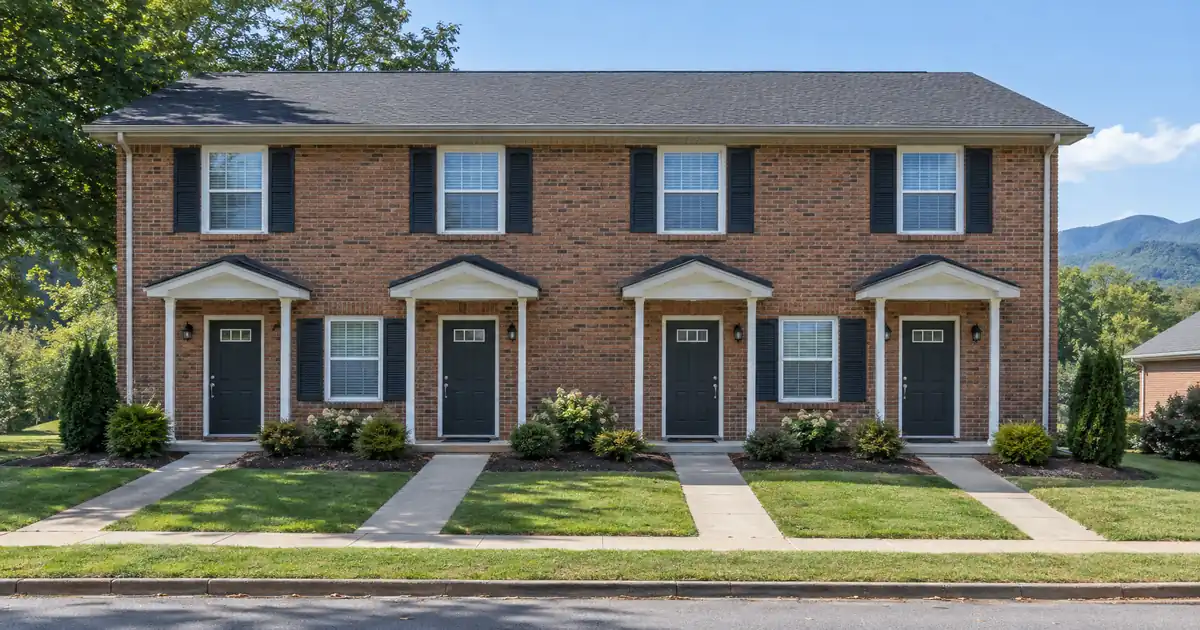
The multi-unit math reads differently. A fully leased four-unit building in 37110 sold for $365,000, per Redfin’s sale record. Each unit is a 2-bed, 1-bath of about 1,000 square feet. Individual units have been advertised at $1,050 and $950. That works out to roughly 1 percent of price or a bit above on asking rents. Against the single-family ratio, that is materially stronger.
On those assumptions, coverage including taxes and insurance clears 1.00x with room at 75 percent LTV. This is one property’s asking rents. It is not a market statistic. The same building shows 362 days on market on a brokerage listing page, which may include relists.
Inventory is thin. One Homes.com snapshot showed 11 multi-family listings from $89,900 to $379,500, against an average of 56 days on market for Mcminnville homes. Small balances at that range route through select lenders in the network rather than standard programs, which go up to $3,000,000.
Honestly, it’s a toss-up between the two property types. The fourplex has better coverage and a harder appraisal. The house has easier comps and tighter coverage. An investor holding either can be right.
Valuation Is the Constraint
For equity extraction, the binding number is rarely coverage. It is the appraised value. Movoto shows the median list price at $315K, down 3 percent year over year, and $191 per square foot, down 2 percent. Those are asking prices. They are not closed sales, and no multi-year appreciation series exists. Zillow’s Tennessee page shows a statewide average of $336,445, up 0.4 percent, so Mcminnville sits well below it.
With flat-to-soft pricing, equity comes from the original basis and from improvements, not from market lift. A property bought below current value, then renovated, holds more cash-out room than one that depends on appreciation. Cash-out is capped at 75 percent LTV. Equity available depends on rent used for lender review, PITIA, reserves and that ceiling. It is not a guaranteed cash figure.
Working DSCR brokers see a recurring pattern in small markets with sparse multi-unit sales: the appraiser leans on one or two comparables, then adjusts hard. Files that arrive with a documented comp set and a lease-backed rent schedule hold value better in appraisal reconsideration than files that arrive with an asking-rent screenshot.
Seasoning, Documents and Where Files Stall
Cash-out requires about 6 months of ownership measured from title recording. Files assuming that clock away get kicked back. If the property was recently purchased, the settlement statement documents the date.
The recurring friction points on small-market files:
1. Entity documents. LLC-titled borrowers need operating agreements and good-standing evidence, subject to lender program eligibility.
2. Lease evidence. In-place leases and rent deposits support the rent schedule, particularly on a fourplex where one vacant unit moves the number.
3. Reserves documentation. Statements showing about 6 months of PITIA, with a higher requirement above $1,500,000.
4. Title clearing. Older housing stock near downtown turns up lien and ownership-history items. Clearing title early prevents a late reissue.
Keep the property types clean. Manufactured homes, log homes and barndominiums fall outside the network’s DSCR programs, which matters on rural parcels outside the core.
Who Rents Here
Demand rests on industrial wages. The city lists industrial, agricultural, education, healthcare and government employment, and describes its position between interstates 24 and 40. Yorozu is the largest automotive supplier in the Upper Cumberland region per the county economic development site. Bridgestone’s truck and bus tire plant in Morrison, outside the city proper, is expanding by $550 million and adding 380 jobs, taking headcount from 1,100 to more than 1,400, per the Tennessee Department of Economic and Community Development. Both support lease-renewal assumptions.
The nursery sector adds a second layer. The city says more than 400 nurseries operate in and around Mcminnville, and TNECD ranks Warren County first among Tennessee’s 95 counties in nursery, greenhouse, floriculture and sod production. Seasonal work is likely to keep workforce rentals steady. That link is inference.
Ascension Saint Thomas River Park is a full-service hospital with 24/7 emergency care. It is a natural tenant pool for rentals near the Sparta St corridor, and it sits under a mile from the fourplex above. It is a small facility and no employee count was found, so don’t oversell it. No large residential university exists in the city. Skip student housing.
The median household income was $47,179, per Point2Homes. Mcminnville is a workforce-rent market, not a premium one.
Turning Proceeds Into the Next Deal
Proceeds only matter if they have somewhere to go. On Mcminnville numbers, the sharper play is often rolling cash-out into the next small multifamily, where rent-to-price runs stronger, rather than a second house at 0.6 percent. Thin inventory makes that a patient search. Investors weighing how the cash-out works should run both sides before pulling equity. For broader program options, see the refi programs and how conventional and DSCR financing compare on investor loans. Tennessee DSCR investor loans covers the state-level view.
Investors who want a coverage read on a specific property can send the scenario over for review or call 828-256-2183. Verify current local rental rules, taxes and insurance with qualified local professionals before building the file.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Mcminnville, Tennessee?
The lender evaluates the property’s rent used for lender review against its full monthly obligation, with 1.00x as the common baseline. Credit tiers run 620, 660, 680 and 700, with 620 as the floor. Reserves, appraised value and seasoning all matter, all subject to lender guidelines. The guide “What Is a DSCR Loan” covers the mechanics.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Mcminnville, TN, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property cash-out loan in Mcminnville?
Expect a 75 percent LTV ceiling, about 6 months of ownership from title recording, and about 6 months of PITIA in reserves. Loan amounts go up to $3,000,000 on standard programs, and smaller balances route through select lenders. Entity documents, leases and a rent schedule round out the file.
Can I use Zumper’s average rent as my comp?
No. The $725 average is dominated by small two-bedroom apartments. Single-family asking rents in sampled listings run $1,550 to $1,895. The appraiser’s rent schedule on the subject property is what the lender uses.
Why does a fourplex appraisal take more care than a house?
Multi-unit comps are few. With one or two sales to lean on, the appraiser adjusts heavily, and value becomes the constraint on proceeds. Bring in-place leases and a recent in-neighborhood comp set to support reconsideration if the value comes in light.
Watchlist for the Next Quarter
1. Listing medians. If the downward drift in list price and price per square foot continues, appraised values come in softer.
2. Fourplex and duplex inventory. A second or third closed multi-unit sale would give appraisers more than one comp.
3. Plant hiring. Watch Bridgestone’s hiring pace and any Yorozu headcount update, since both anchor the workforce tenant base.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire is a non-QM mortgage brokerage (NMLS# 2371349) arranging DSCR investor loans in 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The lender evaluates DSCR loans on rental income rather than personal income, subject to lender guidelines, which fits LLC-owned portfolios, self-employed investors and operators scaling past conventional loan caps. Lendmire has been recognized as a 2025 Scotsman Guide Top Mortgage Workplace and a 2026 Scotsman Guide Top Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Warren County Economic & Community Development
6. McMinnville-Warren County Chamber of Commerce
7. Zumper
9. $1,050
10. $950
11. Remaxcolumbiatn.com — Property White St Mcminnville TN
13. Movoto
16. Tennessee Department of Economic and Community Development
17. TNECD, Where Growth Takes Root
18. Ascension Saint Thomas River Park
19. Point2Homes
20. a 2025 Scotsman Guide Top Mortgage Workplace
21. a 2026 Scotsman Guide Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Mcminnville, Tennessee: Fourplex Equity on a Factory-Town Payroll · Cash Out Refinance Investment Property Johnson City Tennessee · Cash Out Refinance Investment Property in Union City, Tennessee: How Plant-Town Rents Clear 75% LTV
Guides: Investment Property Cash-Out Refinance in Tennessee
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.