
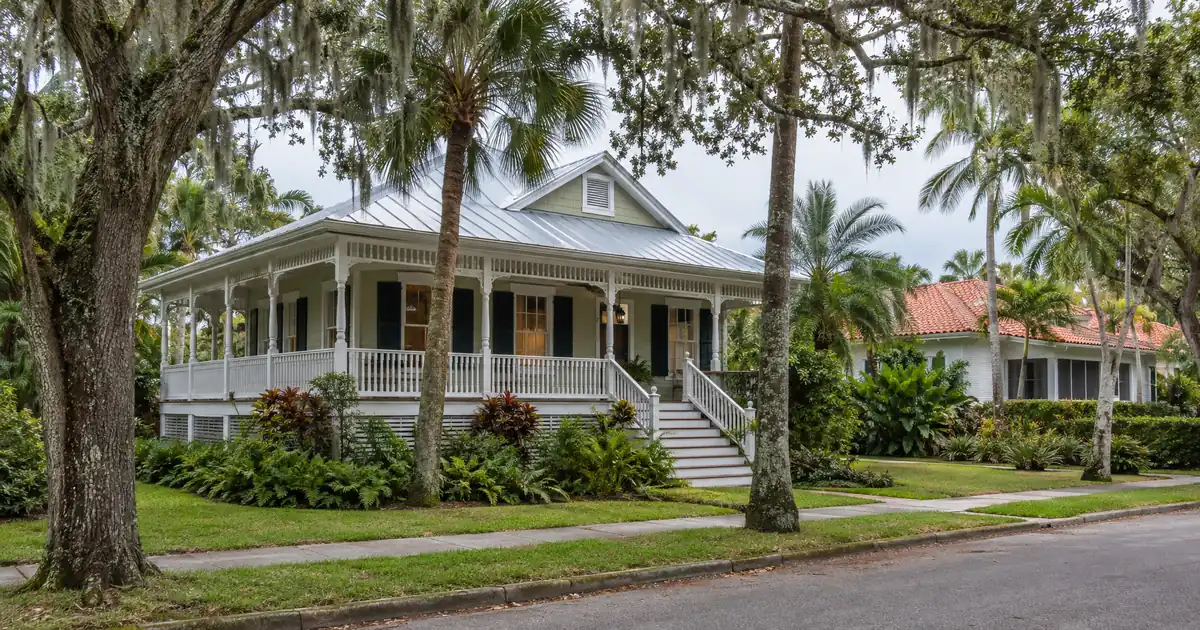
A cash-out refinance in Miami Lakes starts with a 75 percent loan-to-value ceiling and a rent-coverage test, and at a median sale price of $690K, down 1.3 percent year over year, per Redfin, both press hard on the same property. Homes now take 79 days to sell on average. Equity exists on paper here. Whether it can be pulled out depends on whether rent can carry a larger balance.
At a Glance: A cash-out refinance on a Miami Lakes rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, including taxes and insurance, and the town’s high price-to-rent ratio makes that coverage test the binding constraint, not the equity itself. Redfin’s median sale price is $690K.
DSCR Cash-Out Calculator
Run the cash-out numbers in Miami Lakes, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Cash-out ceiling is 75 percent of appraised value, with about 6 months of seasoning from title recording.
- Modeled coverage on entry-level single-family rentals lands near or below 1.00 at full leverage.
- Townhomes carry the lowest price point and the most workable coverage.
- Lakefront and gated homes above $1.3M are poor fits for this structure.
Where the 75 Percent Ceiling Meets a $690K Median
The ceiling is rarely the problem in Miami Lakes; coverage is. A 75 percent cap on a high-priced, suburban, overwhelmingly single-family stock produces large loan balances against rents that have gone flat, so the rent-to-debt ratio gives out before the equity does.
Consider the core facts. Data USA shows a population near 30.7k and median household income of $97,255, and growth is essentially flat: the town is built out. Renters occupy 3,996 units, about 36 percent of housing, so the rental pool is real but finite. Nobody should underwrite appreciation in a market where the median price is sliding and days on market climbed from 55 to 79.
Redfin’s price per square foot is reported up 22.1 percent, which contradicts the falling median. Mix shift is the likely explanation. Skip that number as a valuation argument.
The practical takeaway: size the cash-out to today’s rent, not to a hoped-for appraisal. A longer marketing time also suggests appraisers lean on conservative comps, which trims the 75 percent figure before the lender applies it. Program details follow the refinance pathway for investor properties and stay subject to lender guidelines.
The Coverage Math by Product Type
Townhomes and older 3/2 houses carry the best coverage; nothing in the stock clears comfortably at full leverage. The figures below are modeled assumptions, not sourced market facts: rent divided by full PITIA at 75 percent LTV, with taxes and insurance included and a principal-and-interest component built on an assumed high-6s financing cost. The coverage bands are rounded down.
| Product | Price band (agent est.) | Rent band (agent est.) | Modeled coverage |
|---|---|---|---|
| Entry 3/2 house | $575K–$750K | $3,500–$4,800 | about 0.80–1.05 |
| Townhome | $425K–$625K | $2,800–$3,800 | about 0.85–1.10 |
| Premium lakefront | $1.3M+ | Not sourced | Well below 1.00 |
Price and rent bands come from a local agent guide. They are estimates, not official data, and the rent bands are wide. Pairing the top of the rent band with the bottom of the price band is how these deals look better on paper than in underwriting.
Run the numbers on a hypothetical 3/2 house worth about $650K that rents for $3,800. Coverage at 75 percent LTV lands in the low 0.9s. Drop leverage to 65 percent and the same rent sits around 1.0. Sub-1.00 coverage can be reviewed under sub-1.00 programs, reduced leverage or interest-only structures, but each comes with trade-offs in pricing, proceeds or reserves, and qualification stays subject to lender guidelines, credit approval and property review. The baseline 1.00 benchmark is how DSCR coverage is calculated across most standard programs.
DSCR files in markets like this one typically look like a high-balance, moderate-rent property where the first-pass ratio comes in under the benchmark and the work becomes restructuring: trimming the requested proceeds, lifting documented rent with a current lease or appraisal rent schedule, and confirming reserves. The files that move cleanly are usually the ones where the borrower decided on a smaller cash-out before the numbers were run, not after.
Rent Sources Disagree (and That’s the Underwriting Problem)
Town-wide rent averages understate what a house rents for, but house-specific figures run higher than lenders will credit without support. Redfin shows an average rent of $2,394, with neighborhood medians of $2,400 in Royal Oaks and $2,500 in The Moors. RentHop puts 2-bedrooms at $2,650, down 13.97 percent year over year, and 3-bedrooms at $3,200, down 3.95 percent, while 4-bedrooms sit at $5,124, up 8.25 percent.
Direction matters more than level. Mid-size rentals are soft and larger homes are firmer. That tilts the best coverage toward properties near the top of the bedroom range, which are also the expensive ones, so the benefit cancels.
An aggregator-style estimate puts 3-bedroom houses near $3,800. That is a plausible input, but only an estimate. The appraiser’s rent schedule will land somewhere between the town-wide averages and the house-specific bands. Underwrite to the lower end.
Royal Oaks, The Moors and the Gated Premium
Royal Oaks, a gated community split east and west along NW 82nd Avenue, posts a median rent of $2,400 against owner prices that start well above the town median. The Moors posts $2,500. Neither rent figure supports a cash-out balance at prices in the $800K–$1.2M mid-range for four-bedroom homes.
Gated and lakefront product at $1.3M–$2.5M or more is a different conversation. Rents in that tier are not sourced here, and the coverage would almost certainly fall well below the benchmark. Those owners are better served by a lower-leverage refinance or a different capital source.
The original Graham-built sections east of the Palmetto, including the Main Street area, carry the entry-level 3/2 stock. That is where the most workable single-family coverage sits, and townhome communities like Lake Sarah and Bridgewater sit below it on price.
The 541-Unit Question
New rental supply is the one risk that could push coverage down after a cash-out closes. The Graham Companies is the largest landowner in town, with about 3,000 acres, and has proposed a 541-unit apartment project on 22.2 acres, reported by The Kren Group and still in planning review. An earlier 220-unit version was deferred by the Town Council, per The Real Deal.
Nothing is built. Treat it as a watch item. But a borrower pulling maximum proceeds today is betting that rents on townhomes and condos hold through a large supply delivery. Concentrated ownership also cuts both ways: one landlord sets much of the apartment benchmark, and small investors have little institutional competition on the single-family side.
Six Months, Then What
Seasoning runs about six months from title recording. A buyer who just purchased in a flat market is not sitting on appreciation, so the refinance draws on whatever basis and improvements the property actually has. Cash-out proceeds are not a guaranteed figure: they depend on rent used for lender review, PITIA, reserves of about six months and the 75 percent ceiling. The credit floor is 620, with tiers at 660, 680 and 700, and standard programs reach up to $3,000,000.
Buyers who purchased below the current median, in the older 3/2 tier, have the most room. Those who bought near peak have little.
What the Proceeds Should Do
Pulling cash from a thin-coverage Miami Lakes house to buy another thin-coverage house compounds the problem. Higher-coverage markets elsewhere in Florida or other states may convert the proceeds better, and Lendmire’s Florida DSCR loan programs cover that comparison. The refi options page lays out the structure, and the guide “Where DSCR and Conventional Diverge” matters if the borrower’s personal income could carry a conventional file instead.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges these loans through wholesale channels. Investors can request a scenario review or call 828-256-2183 to test a specific property before ordering an appraisal. Taxes, insurance and local rental rules vary, so verify current details with qualified local professionals.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Miami Lakes, FL, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Frequently Asked Questions
Can a Miami Lakes rental clear 1.00 coverage on a cash-out?
Sometimes, usually only at reduced leverage. Modeled coverage on entry-level houses and townhomes runs roughly 0.80 to 1.10 at 75 percent LTV including taxes and insurance, so a lower LTV or documented higher rent is often what gets the ratio over the benchmark. Eligibility stays subject to lender guidelines.
Does rising equity matter if the median price is falling?
Not much. The median price is down 1.3 percent year over year and homes take 79 days to sell. Equity built through earlier purchase timing or improvements still counts, but the appraisal is the gate, and conservative comps trim proceeds.
Which Miami Lakes property types work best for a cash-out?
Townhomes and older 3/2 houses near the Main Street area. They sit at the lowest price points in town, so the same rent covers a smaller balance. Premium lakefront and gated homes above $1.3M are poor candidates.
How does the proposed 541-unit project affect a refinance decision?
It affects the risk, not the math today. The project is still in planning review, but if built it would compete with townhome and condo rentals. Borrowers who pull maximum proceeds should stress-test coverage against softer rents.
What seasoning and reserves apply?
About six months of ownership from title recording and about six months of PITIA in reserves, rising to about nine months above $1,500,000. Exact requirements depend on the lender and program.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a mortgage brokerage specializing in DSCR investor loans, helping arrange financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. The model centers on property-level rental income reviewed by the lender rather than W-2 documentation, subject to lender guidelines, which suits entity-owned and multi-property investors. Lendmire is a 2026 Scotsman Guide Top Mortgage Workplace, and was recognized by Scotsman Guide in 2025.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin: Miami Lakes housing market
3. Point2Homes: Miami Lakes average rent
4. Rangelyadames.com — Miami Lakes Real Estate Guide
5. Redfin: Miami Lakes rental market
6. RentHop: average rent in Miami Lakes
7. Main Street Miami Lakes: The Graham Companies
8. The Kren Group: 541-unit proposal
10. a 2026 Scotsman Guide Top Mortgage Workplace
11. recognized by Scotsman Guide in 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Miami Lakes, Florida: The 2026 DSCR Financing Guide to Main Street · Cash Out Refinance Investment Property in Cutler Bay, Florida: Equity Math Ahead of Southplace · DSCR Cash Out Refinance in Pembroke Pines, Florida: Two Submarkets, Two Equity Stories
Guides: Investment Property Cash-Out Refinance in Miami, FL · Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.