
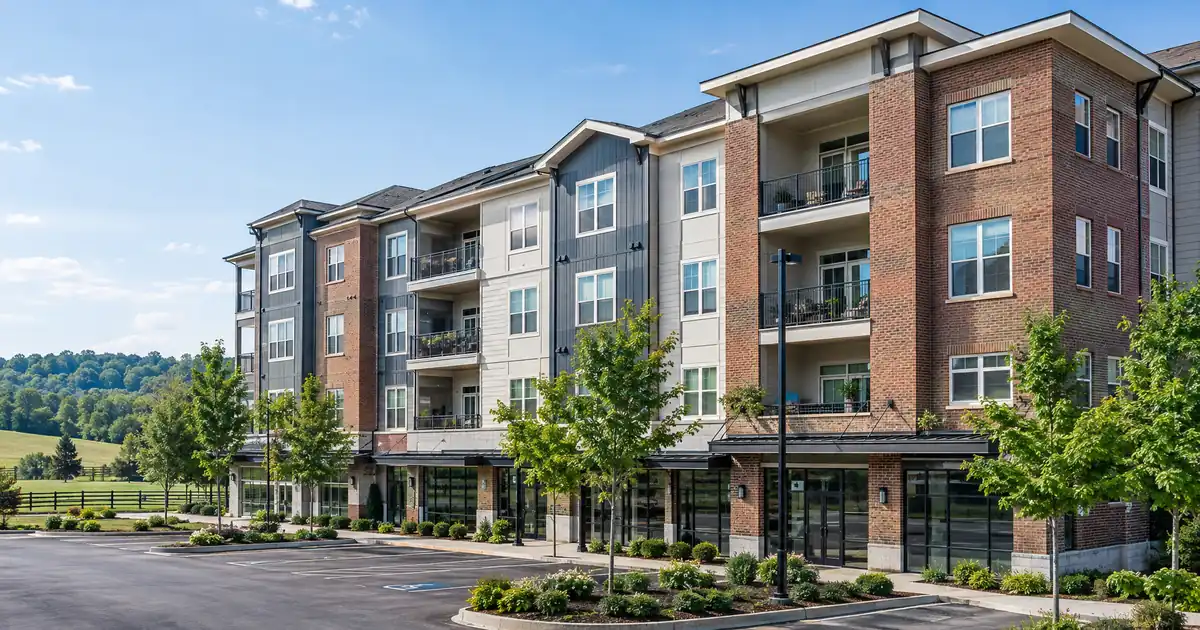
If you own a rental in Nicholasville and you’re counting on the city’s price growth to fund your next deal, here’s what most brokers skip: appreciation sets your paper equity, but rent sets how much of it a DSCR lender will release. The two numbers rarely agree on a single-family house at the city’s median value. They agree much more often on a duplex.
At a Glance: A DSCR cash-out refinance in Nicholasville, Kentucky fits investors who already own a seasoned rental and want equity for the next purchase; the loan is underwritten primarily on the property’s rental income measured against its full monthly obligation, so duplexes and small multifamily with 2–3 bedroom units tend to clear the coverage test that single-family homes strain.
DSCR Cash-Out Calculator
Run the cash-out numbers in Nicholasville, KY
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Median sale price: $345K, up 7.0% year over year (Redfin).
- Cash-out ceiling: 75% LTV after roughly 6 months of ownership, subject to lender guidelines.
- Three-bedroom house rents cluster near $1,750–$1,800, which is thin against that median.
- Two-unit properties give the best rent-to-value lift in the evidence available.
- Brannon Crossing adds new apartment supply that competes with small-investor rentals.
Nicholasville Market Snapshot
A quick read on the Nicholasville investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Recent appreciation | +7.0% yoy (Redfin) |
| Population | ~30,000 population (rounded) (Greater Lexington (lookatlex)) |
| Employment | 1,900+ employees (City of Nicholasville) |
The Equity You Have vs. the Equity a Lender Releases
The cash-out ceiling is 75% of value, and rent decides whether you get near it. Lendmire (NMLS# 2371349), a DSCR-focused mortgage broker arranging investor loans across 41 markets (40 states plus Washington, D.C.), works from typical program guidelines: about 6 months of ownership measured from title recording, a 1.00 minimum coverage ratio, and about 6 months of reserves. Credit tiers run from a 620 floor up through 660, 680, and 700, with stronger scores generally improving positioning. Each of these is subject to lender guidelines, credit review, and property review.
Coverage here means monthly rent divided by the full monthly obligation: principal, interest, taxes, insurance, and any HOA dues. Cash-out makes the denominator bigger, because you’re borrowing more against the same rent. That’s the whole tension. A property that covered comfortably at purchase can look tight once it’s re-levered to 75%.
The tighter the coverage, the lower the leverage a lender will typically want to see. Some programs review sub-1.00 files, but usually with less leverage, more reserves, or stronger credit. Whether that trade is worth making depends on what the cash is for. If the proceeds fund a second property with better coverage, a lower-leverage cash-out can still be a sound move. If the proceeds just cover a gap, look at the property first.
The guide “What Is a DSCR Loan” is worth a read if the ratio mechanics are new. What follows is the Nicholasville-specific math.
What a $345K Median and 7% Growth Really Mean
Nicholasville’s median sale price reached $345K in the latest month reported, up 7.0% year over year, at about $192 per square foot, per Redfin. The same source shows homes sitting 100 days on the market versus 62 a year earlier, and scores the market “somewhat market-rate” at 39 out of 100.
Read those together. Values are climbing while buyers take longer to commit. For a cash-out borrower, that is mostly fine: the appraisal is what matters, and a 7% gain builds equity on paper. But slower absorption means an appraiser leans harder on closed comps than on asking prices, and a softening pace is a reason to keep leverage below the cap rather than at it.
The city has grown a lot. Census Bureau QuickFacts shows 32,197 residents (median age 37.7), and Wikipedia notes a 2020 Census count of 31,490, up 440.23% since 1970. Growth on that scale is real demand, but it also means the newest construction sets the price benchmarks, and older rentals get compared to it.
Rent Reality: The Portals Disagree
Rent-portal data for Nicholasville doesn’t converge, so treat any single figure with suspicion. RentCafe reports an average apartment rent of $1,433 (up 6.12%) and 2-bedroom units at $1,406. Trulia puts a 2-bedroom house at $1,125, a 3-bedroom at $1,750, and a 4-bedroom at $2,395. Rentometer lands at $1,158 for two bedrooms and $1,806 for three.
A defensible working range: roughly $1,100–$1,400 for two-bedroom units, and $1,750–$1,800 for three-bedroom houses. Rent growth is mixed, from +6.12% at RentCafe to +2% at Trulia. Zumper even reports two-bedroom prices down 3.7%. Underwrite flat to modestly rising, not a boom.
Now the modeled math. These are assumptions, not market data: a 3-bedroom house valued at the $345K median renting at $1,750, and a duplex at the same assumed value with two 2-bedroom units totaling $2,500 (inside the $2,200–$2,800 combined range the portal figures imply). Coverage includes taxes and insurance, and is rounded down.
| Scenario (modeled) | At 75% LTV | At 60% LTV |
|---|---|---|
| 3-BR house, $1,750 rent | Mid-0.8s | About 1.0 |
| Duplex, $2,500 combined | About 1.2 | About 1.4 |
The single-family house at max leverage lands well under the 1.00 benchmark. Getting it near 1.0 means pulling back to roughly 60% LTV, which shrinks the cash-out meaningfully. Under 1.00 on long-term rent alone, an investor might look at a sub-1.00 program, an interest-only structure, or a lower-LTV request. A lender would review any of these against credit, reserves, and the appraisal. None is assured. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
The duplex clears at the ceiling. One caveat: a duplex won’t necessarily appraise at the city median, and no sourced count of duplexes, triplexes, or fourplexes exists here. Run the actual property, not the illustration. (An aggregator like Hud Housing Network shows 2-bedroom bands of $942–$1,412, and the width of that band is itself the warning.)
Brannon Crossing: Growth Edge, Thin Yield
Brannon Crossing, at the north end near the US-27 and Lexington Road approach, is where the city’s growth is concentrated. LEX18 reported the annexation of about 120 acres for retail, a grocery, a hotel, and a site plan with 13 apartment buildings. Movoto shows a median listing price near $524K here, though that’s a brokerage listing figure and indicative only.
That price sits far above the $345K citywide median, so rent-to-value is weakest here for single-family. Owning a house in the area builds equity on paper, but a 75% LTV ask against a $524K value needs rent that the portal ranges don’t show for houses. Consider that honestly before assuming the highest-value neighborhood is the best cash-out candidate. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Supply matters too. Listings on Homes.com show The W, Ashgrove Farms Townhomes with two- and three-bedroom plans, and The Avenue with one- to three-bedroom units. That is new 2–3 bedroom product going after the same renter your duplex serves. It’s a listing signal, not a vacancy statistic. Still, an underwriter reviewing your rent schedule will look at the newest comps, and a lease priced above them invites questions.
Skip the Assumption That Newer Means Better
Honestly, this one is a toss-up. New construction near Brannon Crossing offers cleaner condition and strong appreciation optics. Older stock closer to the core generally has lower basis and better rent-to-value, but more maintenance risk. An investor buying for appreciation could argue for the new side. An investor buying for cash-out capacity, which is what this article is about, gets more from the lower basis.
The Older Core and the Commuter Spine
Away from Brannon Crossing, no sourced neighborhood-level rent or price data exists, so this part stays qualitative. The North Main Street and downtown courthouse area has older housing and potential for small multi-unit conversions or existing duplexes. The US-27 corridor is the commuter line into Lexington. On the south side, the City of Nicholasville describes the Jenette Farm Industrial Park as industrial-zoned with US-27 access, which suggests workforce-rental demand nearby, though no housing data confirms it.
What the data does support is the unit mix. Point2Homes shows 2-bedroom units at 40% of rentals and studios at about 1%, with most apartment rentals built between 1970 and 1999. So the core of demand is 2–3 bedroom units in older buildings. A studio-heavy or 1-bedroom-heavy building matches a small slice of that. A duplex with 2–3 bedroom units on each side fits the pattern.
Who Rents Here, and Why It Holds
Nicholasville’s tenant pool leans on Lexington. Business View Magazine says many residents commute to Lexington for work, calling the housing market very market-rate with a diversified employer base. Data USA puts the Jessamine County commute at 23.8 minutes, and health care as the largest county industry at 4,207 workers, ahead of retail (3,725) and educational services (2,999).
Local anchors add depth. The city’s economic development page says Alltech is headquartered here with more than 1,900 employees, and CommonSpirit describes Saint Joseph Jessamine as the county’s first and only full-service 24/7 emergency room. Hospital and corporate staff are a realistic pool for 2–3 bedroom rentals. RentCafe puts renters at 37% of households, or 4,426 renter-occupied units, a modest but stable base.
The tradeoff: tenant demand is partly tied to Lexington’s job market, not only local employers. That gives a lender a durable demand story, and it also means a Lexington downturn would reach your rent roll.
What Deal Desks Tend to See in Markets Like This
In suburban markets adjacent to a larger job center, the common friction point on cash-out files is the gap between appraised value and in-place rent. Owners see a 7% value gain and assume proportional borrowing power, then discover that coverage, not equity, is the binding constraint. The cleaner files tend to arrive with a current lease, a rent comparable pulled from the newest nearby buildings, and an insurance quote refreshed before submission, because those inputs move the coverage number more than the appraisal does.
Where the Proceeds Go
Pulled equity is only as good as the next deal. Say you refinance a seasoned Nicholasville duplex and redeploy the proceeds into another two-unit property with 2–3 bedroom units. Each step keeps coverage healthy, and the portfolio compounds. Now say you pull the maximum from a single-family house that barely covers, and use it to buy a similar house at a similar price. You’ve doubled a thin-coverage position.
For portfolios past four financed properties, the conventional lane runs out and DSCR is typically a practical path when conventional options are a poor fit. For a single rental held personally by a high-W-2 borrower, the comparison may favor conventional financing. The break-even is somewhere around the third financed property, or earlier if your traditional personal-income documentation doesn’t show your rental income cleanly.
Investors weighing options can read the cash-out refinance walkthrough for the general mechanics. For state-level context, see Lendmire’s Kentucky DSCR financing page. And before any of it, verify current local rental rules, taxes, and insurance with qualified local professionals.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Nicholasville?
Qualification centers on the property’s rent relative to its full monthly obligation, with a 1.00 benchmark common, plus credit (tiers start at a 620 floor), about 6 months of reserves, and roughly 6 months of ownership. Leverage caps at 75% for cash-out. Exact eligibility depends on lender guidelines, credit profile, and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Nicholasville, KY. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Nicholasville, Kentucky?
Expect a rental property with documented or market-supported rent, a credit score that meets the program tier, reserves, and an appraisal. Borrowers can typically close in an LLC, subject to lender program eligibility. Manufactured homes, log homes, and barndominiums fall outside these programs.
Does a single-family rental in Nicholasville work for max cash-out?
Usually not at the median. A 3-bedroom near $1,750–$1,800 against a $345K value models in the mid-0.8s at 75% LTV including taxes and insurance, so lower leverage or a different structure is the likelier path. A duplex has the stronger chance of clearing 1.00 at the cap.
Does Brannon Crossing new construction help or hurt a refinance?
It can do both. Higher values, well above the typical Nicholasville home by one listing source, expand equity on paper, but rent-to-value is weakest there. New apartments and townhomes also compete with small-investor rentals, so conservative rent assumptions are safer.
Can Lendmire help structure a DSCR cash-out refinance scenario for a Nicholasville rental property?
Yes. Lendmire arranges DSCR investor loans, and its cash-out programs generally allow up to 75% LTV after about 6 months of seasoning, subject to lender guidelines. Reach the team at 828-256-2183 or see how the math pencils.
The Question Worth Answering First
Lexington’s pull will keep Nicholasville’s rental demand steady, and Brannon Crossing’s supply will keep rents honest. So look at your own rent roll: if the property you own sits near the city’s median value and rents like a 3-bedroom house, is the equity you’re planning to pull one a lender will actually release, or is the missing piece a second unit?
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
A non-QM mortgage broker (NMLS# 2371349), Lendmire arranges DSCR financing for real estate investors in 41 markets: 40 states plus Washington, D.C. Because these loans are underwritten primarily on property cash flow rather than personal income documentation, the structure suits self-employed buyers and entity-owned portfolios. Lendmire places loans through wholesale investor lenders and is not a direct lender. It has been recognized by Scotsman Guide as a 2026 Top Workplace and named a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Redfin, Nicholasville Housing Market
2. Greater Lexington (lookatlex)
3. City of Nicholasville, Economic Development
4. Census Reporter, Nicholasville Profile
5. Wikipedia
6. RentCafe, Nicholasville Rent Trends
7. Trulia
8. Rentometer
9. Zumper
11. LEX18, Brannon Crossing Development
12. Movoto
13. Homes.com
14. Point2Homes
15. Businessviewmagazine.com — Nicholasville Kentucky Jessamine County
16. Data USA, Jessamine County
17. CommonSpirit
18. recognized by Scotsman Guide as a 2026 Top Workplace
19. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance Nicholasville Kentucky · Cash Out Refinance Investment Property Erlanger Kentucky · Cash Out Refinance Investment Property Without W-2 in Mount Sterling
Guides: Investment Property Cash-Out Refinance in Kentucky
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.