
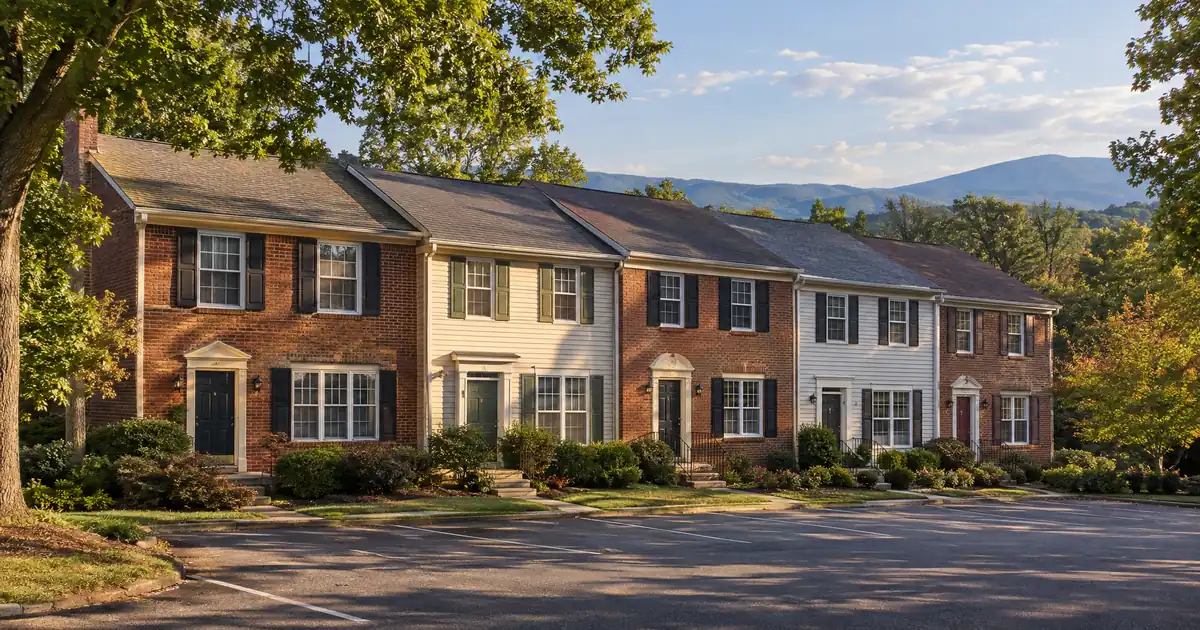
Three things are moving in Warrenton over the next 6 to 18 months, and each one bears on a cash-out appraisal. A 386-unit apartment and townhome proposal for Warrenton Village Center is on the table, with approval and construction status unverified. Redfin shows a median sale price of $499,728, down 12.0% year over year. Other portals show the market much higher. Owners sitting on equity should understand how a lender will read that mess before ordering anything.
TL;DR: A DSCR cash-out refinance on a Warrenton, Virginia investment rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with a lender-ordered appraisal setting value, then reserves and seasoning verified from title recording before proceeds are sized.
DSCR Cash-Out Calculator
Run the cash-out numbers in Warrenton, VA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Published price sources disagree widely, so the appraisal sets the equity number, not a portal median.
- Rent-to-value is thin here. Lower LTV or lower-priced product types usually decide whether coverage reaches 1.00.
- FAA facilities on the Vint Hill site anchor about 600 technical employees.
- Cash-out tops out at 75% LTV, with about 6 months of seasoning from title recording.
Lendmire is a DSCR-focused mortgage broker. Lendmire’s DSCR program footprint covers Warrenton, Virginia as part of a 41-market reach that includes Washington, D.C. The broker arranges these loans through wholesale lending channels. Lenders review eligibility and approve. Details are on the Virginia DSCR investor loans page.
Warrenton Market Snapshot
A quick read on the Warrenton investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | 12 sales (Redfin Warrenton Housing Market) |
| Population | 10,176 population (Census Reporter (ACS)) |
| Employment | About 600 employees (FAA) |
Why the Appraisal Is the Whole Game in Warrenton
The valuation is the weakest link on Warrenton cash-out files. Price sources don’t agree, and the comp pool is small.
Take the published numbers. Redfin’s town median is about $500K. Movoto reports a median sold price of $750,000 with 28 days on market. Its listing page shows a median list price of $799K, up 3% year over year, and describes a market that is slowing. Zillow’s home value index lands at $675,188. These sources measure different things: sold versus listed, town versus ZIP, and all home types mixed together. No single figure is “the” median, and none should go into a cash-out projection.
Small samples make it worse. Redfin has reported a median of $604K from only 12 homes sold in a single month. A swing like that can be a change in which homes sold, not appreciation. An appraiser working a modest-lot townhome may lean on very few comps.
The operating rule is simple. Don’t underwrite a cash-out on an assumed jump in value. Build the file so it still works if the appraisal comes in flat. If it comes in light, the path is appraisal reconsideration with documented in-town sales and condition adjustments. That is routine, not a crisis.
The Tenant Base: Federal, Clinical, and Commuting
Warrenton’s rental demand rests on employment that can’t easily relocate. The FAA’s Air Traffic Control System Command Center moved to Warrenton in 2011, and the Potomac TRACON sits in the same place. FAA puts the combined workforce at about 600 highly technical employees. The Potomac TRACON handles airspace over Reagan, Dulles, BWI, Andrews, and Richmond. There’s no direct peer for that among Virginia towns this size.
Fauquier Health is the second leg. It’s a 97-bed acute-care hospital with a Leapfrog Top General Hospital designation, and a third-party profile puts staff near 1,000 (approximate, may be dated). Nurses, techs, and allied health workers are a steady pool for 2-3 bedroom rentals near Hospital Drive.
Resident occupations fit the pattern. Data USA lists professional and technical services at 714 residents, health care at 663, and education at 662. Town planning documents say nearly six in ten residents work outside town. Census Bureau QuickFacts shows a population of 10,176 and a mean commute of 30.3 minutes.
One thing to drop: student rentals. Laurel Ridge Community College has a Fauquier Campus in Warrenton, but there’s no four-year university. Commuter demand and staff housing are the thesis, not dorm overflow.
Can the Coverage Number Clear? Run It Two Ways
At current price levels, the rent-to-debt ratio is the constraint on most Warrenton cash-out files. Modeled with full taxes and insurance in the payment, coverage near 1.00 shows up only on lower-priced product.
Start with the rent data. It is messy. Apartments.com puts the average apartment rent at $1,190, and its rent trends page shows $1,288 or more for a three-bedroom, up 1% year over year. Zumper’s all-property average is $2,517, roughly double the apartment band. Dwellsy shows a 7.2% decrease over its window, while Zumper shows an increase. The aggregators disagree in direction. A small town’s averages swing on a handful of listings, so the lender’s rent schedule and leased comps are what count.
Here are two modeled scenarios. The rents and prices are assumptions, not sourced market figures, and coverage is rent divided by full PITIA (principal, interest, taxes, insurance).
Scenario one. Say you own a detached house valued at $600,000 and refinance at 75% LTV. Assume a market rent of $2,517. Coverage lands around 0.7x including taxes and insurance. That’s well under the 1.00 benchmark, so the property doesn’t work on long-term rent alone at that leverage. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
Scenario two. Run the numbers on a $400,000 townhome at 75% LTV with an assumed $2,500 rent. Coverage comes out right around 1.0x including taxes and insurance. That’s borderline, and any insurance increase pushes it under. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
For the first scenario, a lender would review options. Those include lower LTV, a sub-1.00 program, or an interest-only structure. Each brings its own pricing, reserve, and leverage terms, and eligibility depends on the borrower, the property, and lender guidelines. Most standard programs are built around a 1.00x baseline because rent covers the payment at that level. Some lenders will look below it with compensating factors. That’s a lender decision, not an assumption.
Working DSCR brokers see a recurring pattern in high-price, thin-rent exurban markets like this one. Owners arrive with a portal estimate of value and a listing-site estimate of rent, and neither survives the appraisal and rent schedule. The files that hold together carry a conservative value, a lender-ordered rent figure, and a lower LTV than the 75% cap. Files built to the ceiling are the ones that need a restructure late.
Submarkets: Where Coverage Has a Chance, and Where It Doesn’t
No reliable neighborhood-level rent or price medians exist for Warrenton, so this is qualitative. The tenant mapping below is inference from where employers sit.
Vint Hill is the strongest demand story. The former Army signals station hosts the FAA facilities, engineering and technology firms, and a Laurel Ridge site. A major local employer is converting former barracks into market-rate rentals. Federal-workforce tenants give long-term leases a stable base. Watch new apartment supply there, since it competes with 1-2 bedroom rentals.
Hospital Drive and the Fauquier Health area fits clinical staff. Think 2-3 bedroom townhomes and smaller houses. This is the most natural place to find product priced low enough to approach 1.00.
Old Town is older houses and small conversions near the courthouse, restaurants, and shops. Character helps tenant demand. Older stock can produce condition adjustments on appraisal, so document updates.
The Route 29 corridor south of town serves service workers and community-college staff. It’s less glamorous, and likely the lower-priced end of the town’s product.
Brookside is a master-planned, owner-occupant community at the top of the price range. Rent-to-value is weak there. Skip it for cash-out unless the numbers clear at a much lower LTV.
Supply matters for the strategy. About 75.0% of the housing inventory is single-family, and just 1.8% of land is in multifamily use per the town’s housing background study. Only about 40 multifamily units have been built since 2010. That data is dated. It supports a scarcity argument for duplexes and small multi-unit properties, though it also means few deals. The stronger play might be a small multi-unit over a single-family house for coverage, but underwrite each unit against the apartment rent band, not the house band. Reasonable investors could argue the other way if a three-bedroom house rents at a premium.
How the Cash-Out Mechanics Work Here
The mechanics are straightforward. Friction comes from seasoning and reserves documentation.
1. Confirm seasoning. Programs typically look for about 6 months of ownership, measured from title recording. The settlement statement documents it. Files that assume this away get kicked back.
2. Set the LTV ceiling. Cash-out tops out at 75% of appraised value. That differs from the higher purchase cap, and the two shouldn’t be mixed in a projection. Equity available depends on rent, PITIA, reserves, and that ceiling, so it isn’t a guaranteed cash figure.
3. Document reserves. Reserves usually run about 6 months of PITIA, and higher on larger balances. Bank statements, sourced and seasoned, are what a lender reviews.
4. Paper the entity. If the property is LLC-titled, operating agreement and entity documents should be in order, subject to lender program eligibility.
5. Plan the proceeds. The cash-out is capital for the next deal, so size the next purchase against the proceeds after the appraisal, not before.
For the full program detail, see the cash-out qualification details and refinance details. Payment structure versus bank underwriting is covered in “Where DSCR and Conventional Diverge”, and the guide “What Is a DSCR Loan” explains the coverage calculation. To test a specific property, compare DSCR options or call 828-256-2183.
DSCR vs. conventional financing
Two common ways to finance an investment property in Warrenton, VA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Verify current local rental rules, taxes, and insurance with qualified local professionals before you commit. Program details can change, and qualification is subject to lender overlays.
What to Ask Before You Order the Appraisal
Seasoned owners have the equity on paper. The real question is how a lender will value the house against a thin comp pool, and whether the rent schedule carries the coverage number at the LTV you want. If the answer depends on a portal median, rework it before the file goes in.
If a Warrenton appraiser pulled only a handful of recent sales for your rental tomorrow, would the value you’re counting on still hold?
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Warrenton, Virginia?
Qualification centers on the property’s rent against its full PITIA, with 1.00 as the usual benchmark. Lenders also review credit, with a 620 floor and higher tiers at 660, 680, and 700, plus documented reserves. Given Warrenton’s price-to-rent relationship, expect lower LTV or a lower-priced property type to be part of the conversation. Final eligibility rests with the lender.
What are the requirements for an investment property loan in Warrenton, Virginia on a cash-out?
Typical guidance is about 6 months of ownership from title recording, a 75% LTV cap, and reserves of about 6 months PITIA. Loan amounts run up to $3,000,000 on standard programs. Manufactured homes, log homes, and barndominiums fall outside these DSCR programs, which matters in a horse-country market where some rural properties are barn-style. All of it is subject to lender guidelines.
Does the FAA workforce make Warrenton rents more stable?
It supports tenant demand, since the roughly 600 technical jobs at the Command Center and TRACON are difficult to relocate. It doesn’t fix the rent-to-value gap, and it doesn’t guarantee coverage on any given property. Hospital and county employment add a second and third demand source.
Will the proposed Warrenton Village Center apartments affect cash-out plans?
Possibly, and the effect is worth weighing. If the 386-unit proposal proceeds, it would be the first meaningful new apartment supply in years and could compete with 1-2 bedroom units. Its approval and construction status weren’t verified, so check it before underwriting rent growth on small multi-unit properties.
Can Lendmire help investors explore DSCR financing for properties outside Virginia?
Yes. Lendmire, NMLS# 2371349, arranges DSCR investor loans. Qualification is generally reviewed around the property’s rental income, not the borrower’s W-2 history.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire, NMLS# 2371349, is a non-QM mortgage broker serving real estate investors in 41 markets, including Washington, D.C., through DSCR investor loan programs. Qualification is generally reviewed around the subject property’s rental income rather than a borrower’s W-2 history, a practical fit for LLC-titled portfolios and self-employed investors, subject to lender program eligibility. All scenarios remain subject to lender review and program guidelines. The brokerage is a 2025 Scotsman Guide Top Workplace and was recognized by Scotsman Guide as a 2026 Top Workplace, two consecutive Top Mortgage Workplace recognitions.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Redfin
3. FAA Air Traffic Control System Command Center
6. Movoto reports a median sold price of $750,000
8. Zillow — Home Values Warrenton VA
9. FAA Potomac Consolidated TRACON
10. Fauquier Health
12. Census Reporter, Warrenton
13. Laurel Ridge Community College, Fauquier Campus
14. Apartments.com
15. Apartments.com — Rent Market Trends Warrenton VA
16. Zumper’s all-property average
17. Dwellsy
18. a 2025 Scotsman Guide Top Workplace
19. recognized by Scotsman Guide as a 2026 Top Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Virginia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Disclosure information. Lendmire is a state-licensed mortgage brokerage under NMLS# 2371349. Lendmire is not a depository institution, direct lender, or financial advisor — all loans referenced are placed through wholesale lender partners and are subject to each lender's underwriting standards. This article is provided for general informational purposes and is not a commitment to lend, nor does it constitute financial, legal, or tax advice. Loan programs, terms, rates, and qualification standards change without notice and depend on borrower profile, property type, and the state in which the subject property is located. Equal Housing Opportunity provider. NMLS Consumer Access: nmlsconsumeraccess.org.