
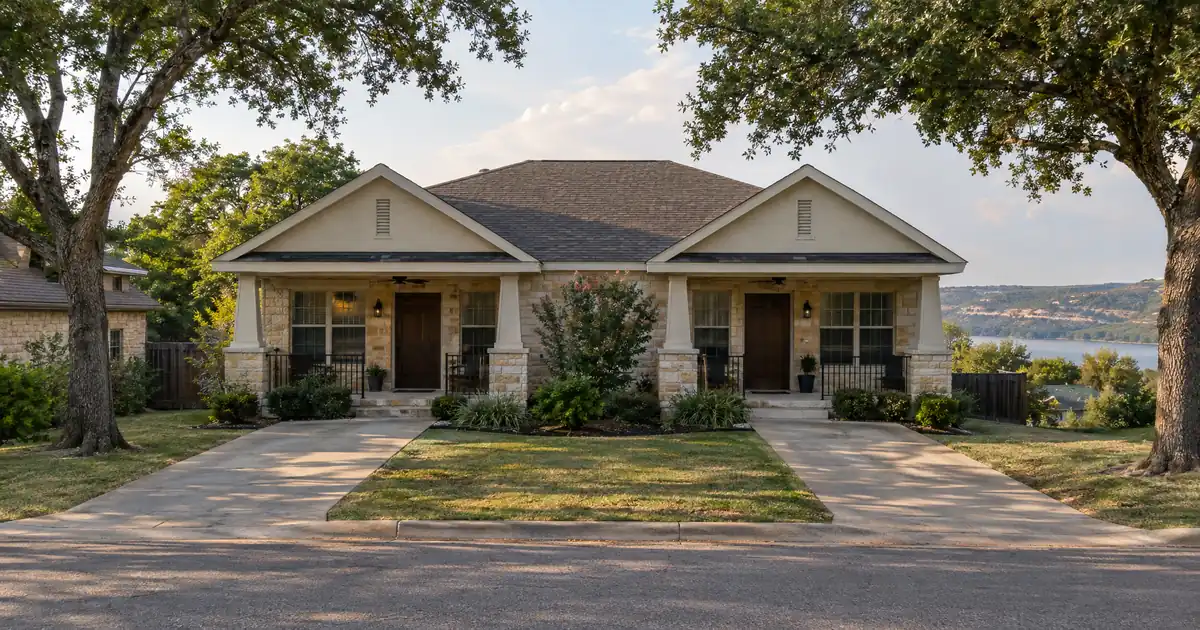
Downtown Marble Falls, the walkable pocket around Main Street and Old Oak Square, is where a cash out refinance on an investment property has the best chance of working. Its stock leans toward duplexes, cottages, and attached homes rather than detached houses, and stacked unit income is what helps coverage here. The same pocket also shows why the equity story is harder than most Texas investors expect. Prices have slid, rents have softened, and the 75 percent loan-to-value ceiling gives no credit for what a property was worth at its peak.
For Marble Falls, Texas rental property financing, Lendmire (NMLS# 2371349) helps arrange DSCR loans through lenders operating in 41 markets, including Washington, D.C. This article covers the extraction side only: what the appraisal does to proceeds, which property types carry the coverage, and where the numbers break.
DSCR Cash-Out Calculator
Run the cash-out numbers in Marble Falls, TX
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version: A cash-out refinance on a Marble Falls, Texas rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, with the 75 percent LTV ceiling applied to a current appraisal and roughly six months of ownership required. Available equity follows today’s value, not the purchase story.
- Zillow puts typical value at $452,030, down 6.0 percent. Redfin shows a $298K median sale price.
- Single-family rent-to-value at the median runs well under 1 percent. RentCafe reports 59 percent of housing is renter-occupied, mostly in small complexes.
- Seasoning of about six months and a 75 percent LTV cap frame every file.
Marble Falls Market Snapshot
A quick read on the Marble Falls investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $338,800 median value (Data USA) |
| Typical rents | $1,360 median gross (Point2Homes) |
| Employment | 445 employees (Marble Falls EDC highlights) |
Why Appreciation Can’t Be Assumed Here
Marble Falls prices are falling, so equity extraction has to be underwritten at current value, not at purchase price or at a remembered peak. Redfin’s market data shows a decline in the three-month median sale price and in median price per square foot compared with a year earlier, with the drop in price per square foot being the steeper of the two. Zillow also shows a decline, though a smaller one. The exact figures vary by source and methodology, as the next paragraph lays out.
The sources disagree on the level, and the spread is large. Zillow’s typical value of $452,030 and Redfin’s $298K median sale price differ by geography and methodology, so no single “median” is right. Movoto lists $426,995 and the Census-based figure at Data USA is $338,800. They all point the same way, though: flat to down.
Run the leverage math on a modeled owner. Say you bought at 80 percent LTV and the property has since lost 6 percent of its value. Your current LTV sits near 85 percent, well above the 75 percent ceiling, so there is nothing to pull out. Even at flat value, an 80 percent purchase loan has to see roughly 7 percent appreciation before cash-out headroom opens. Owners who bought with 25 percent or more down, or who bought below market in older in-town homes, are the ones with realistic room.
Redfin does show demand improving: 52 homes sold in May versus 36 a year earlier, with 74 median days on market. That is a thinner market, but not a frozen one.
Where the Coverage Comes From (Duplexes, Not Houses)
Small multi-unit and attached product carries Marble Falls coverage because single-family rents are too low relative to value. Applying Zumper’s $1,550 median rent to Zillow’s $452,030 value gives monthly rent-to-value of about 0.34 percent. Against Redfin’s $298K, it is about 0.52 percent.
Add full PITIA with Texas-level property taxes and insurance, and a single-family house at the median does not clear 1.00 coverage. Say it plainly: those numbers don’t work.
RentCafe’s Census-based housing mix explains why small-format rentals matter. Of local apartments, 78 percent sit in complexes under 50 units and 17 percent are single-family rentals. Sample duplex-unit asking rents run about $1,100, with one-bedrooms near $850 and two-bedrooms starting around $1,025. Two units at $1,100 produce roughly $2,200 in gross rent on one lot, well above the $1,550 single-family median. That stacked income is the difference between a file that covers and one that doesn’t. Treat those listing rents as asking figures, not leased rents, and underwrite with a haircut.
Consider the stronger play for a thin-coverage owner: refinance the duplex, not the house. It is a genuine toss-up on appreciation, since neither type is gaining value, but the duplex at least produces the income side of the ratio. How rental-income qualification works is straightforward: monthly rent divided by the full monthly obligation, with 1.00 the common baseline subject to lender guidelines.
The Appraisal Problem on Multi-Unit
Thin multi-unit inventory can cap appraised value, and that caps proceeds. Homes.com lists 24 multi-family properties in Marble Falls, averaging 92 days listed. The asking range, from $850 to $5,000,000, is too wide to be a usable duplex comp set. An appraiser working with that data may pull comps from outside the city.
Budget for a conservative number. If the appraisal lands at the low end, the 75 percent ceiling applies to that value, not the one in your head. The equity-extraction mechanics hinge on this single input more than any other.
Lake Frontage Is a Different Animal
Lakefront on Lake Marble Falls and Lake LBJ, running toward Horseshoe Bay along FM 2147, commands premiums and skews toward second homes. It isn’t the core long-term-rental submarket. An owner holding lakefront and hoping to extract cash on lease income should expect rent coverage to trail the value, because price is driven by lifestyle demand rather than workforce rents.
Rental demand sits elsewhere. According to Data USA, the resident workforce numbers about 3.8 thousand, led by construction at 590 workers, retail at 586, and accommodation and food service at 496. The average commute is 14.9 minutes. Baylor Scott & White Medical Center–Marble Falls anchors the healthcare side; the Marble Falls EDC reported 445 employees at a $58,000 average wage, excluding physicians, in an older tally. Treat that headcount as dated.
The Apartment Corridor and the Concession Squeeze
Competition from new apartments is the second pressure on cash-out files. The corridor along Gateway Parkway, Mustang Drive, Brazos Street, and 6th Street houses workforce renters, and new supply is arriving. According to Redfin’s listing snapshots, FLATZ 830 shows 77 units available and Prose Thunder Rock shows 149, while Residences at Panther Hollow advertises 10 weeks free. RentCafe lists a first-month-free special on a two-bedroom at $1,025, and Apartments.com counts 173 newly constructed apartments.
These are listing snapshots, not a vacancy rate. Still, concessions on new product pull effective rents down for older duplexes. Apartments.com shows average rent at $1,386, down 10.1 percent year over year, and Zumper’s median is down 20 percent. Underwrite conservative rent and a vacancy allowance above the usual 5 percent.
Jump from rent to proceeds. Lower rent used for lender review shrinks the loan the property can carry at 1.00 coverage, which is a second ceiling alongside the 75 percent LTV cap. The lower of the two binds.
What Lenders Actually Look At
Lendmire’s deal desk sees a consistent pattern on files from small, softening markets like this one. The cleaner files carry a current lease or a market-rent appraisal schedule that supports the rent, a payoff statement showing the existing balance, and a title record that clearly shows ownership timing for the seasoning clock. The common friction point is a gap between what the owner thinks the property is worth and what a conservative appraisal returns. Files that arrive with realistic expectations tend to move through review with fewer surprises.
On parameters, the typical guidance is about six months of ownership from title recording, a 75 percent LTV ceiling, a 1.00 minimum coverage ratio, a credit floor of 620 with better tiers at 660, 680, and 700, and reserves of about six months PITIA. Loan amounts run up to $3,000,000 on standard programs. All of it is subject to lender guidelines, credit review, and property review, and equity available is never a guaranteed figure.
What Happens to the Proceeds
Cash-out funds are only as good as the next deal. In a market where prices are falling, pulling equity out of Marble Falls to buy more Marble Falls is a doubling-down decision. An owner might instead redeploy into a different market where rent-to-value is higher, which is where a multi-market DSCR platform matters. Investors weighing a cash-out against a straight rate-and-term can also compare refinancing options, including a side-by-side comparison with conventional financing.
For a first look at your own numbers, see what the numbers look like or call 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Marble Falls?
The lender reviews the property’s rent against its full monthly obligation, with 1.00 as the common baseline. Typical guidance also includes about six months of ownership, a credit score of at least 620, and reserves near six months of PITIA. Because Marble Falls single-family rents are low relative to value, duplex or attached product usually qualifies more comfortably. Everything remains subject to lender guidelines.
DSCR vs. conventional financing
There are two common ways to finance an investment property in Marble Falls, TX, and they qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property loan in Marble Falls, Texas?
Expect the lender to ask for an appraisal with a rent schedule, proof of ownership timing, reserves, and a credit profile at or above the program floor. Cash-out leverage is capped at 75 percent LTV. Property taxes and insurance, which vary by county and carrier, get verified with qualified local professionals.
Will falling Marble Falls prices block a cash-out refinance?
Yes, they can. Both Zillow and Redfin show declines in Marble Falls, and the 75 percent ceiling applies to the current appraisal rather than the original purchase price. An owner who bought at 80 percent LTV sits above the cap unless value has risen meaningfully. Owners with substantial down payments or below-market purchases keep more room.
Why do duplexes work better than houses for cash-out coverage in Marble Falls?
Two units at roughly $1,100 each produce about $2,200 in rent, versus a $1,550 single-family median at Zumper. Stacked rent lifts the coverage ratio without needing a higher purchase price. Check the price first, since per-unit rents are modest.
Can Lendmire help arrange DSCR financing for an investment property in Marble Falls?
Yes. Lendmire arranges DSCR investor loans through lenders. Programs review the property’s rental income rather than personal income documents, subject to lender guidelines.
The Blind Spot: Equity You Think You Have
The biggest risk for DSCR-financed investors in Marble Falls is anchoring on a purchase price or peak value the market no longer supports. With prices down across every source and new apartment concessions pressuring rents, the appraisal and the rent used for program review can both come in below expectations at once. Underwrite to the lower number, and treat any cash out as a bonus rather than a plan.
About Lendmire
Lendmire, NMLS# 2371349, is a DSCR and non-QM mortgage brokerage with investor loan programs in 41 markets, including Washington, D.C. Lenders commonly review DSCR eligibility around property-level rent rather than personal income documentation, subject to lender guidelines, and the brokerage helps arrange financing for LLC-owned portfolios beyond conventional financed-property limits. It is recognized by Scotsman Guide as a 2026 Top Workplace (see the 2026 Top Workplaces feature) and as a 2025 Scotsman Guide Top Mortgage Workplace.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Zillow Home Values, Marble Falls
2. Redfin Housing Market, Marble Falls
5. Point2Homes
7. Movoto
8. Census-based figure at Data USA
9. Zumper Rent Research, Marble Falls
10. Homes.com Multi-Family, Marble Falls
11. Baylor Scott & White Medical Center–Marble Falls
12. Apartments.com
13. the 2026 Top Workplaces feature
14. a 2025 Scotsman Guide Top Mortgage Workplace
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: DSCR Cash Out Refinance in Marble Falls, Texas: Old Town Duplex Equity Under Softening Prices · Cash Out Refinance Investment Property in Pharr, Texas: 2026 DSCR Guide to the Bridge Corridor · DSCR Cash Out Refinance in Pharr, Texas: The 2026 Cash-Out Guide to the Pharr Bridge Corridor
Guides: Investment Property Cash-Out Refinance in Texas
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Important disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage brokerage. Lendmire is not a direct lender, depository institution, or financial advisor. All loan inquiries are subject to lender underwriting; this article does not constitute a commitment to lend. Rates, terms, and program guidelines are subject to change without notice and vary by borrower profile, property type, and state. Information in this article is general in nature and is not financial, legal, or tax advice. Equal Housing Opportunity. NMLS Consumer Access: nmlsconsumeraccess.org.