How To Document Large Deposits On A Bank Statement Second Home Loan
The underwriter isn’t accusing you of anything.

The underwriter isn’t accusing you of anything.
The first appraiser inspects the property and sets value.
How A Bank Statement Lender Sets Reserves By Loan Size On A Second Home — what borrowers need to know, from Lendmire.
The trustee typically signs as the individual guarantor even though the trust holds title.
PL Loan Treats One Declining Year For A Loan-out Corporation — A P&L loan usually won’t average a rough year with a strong one.
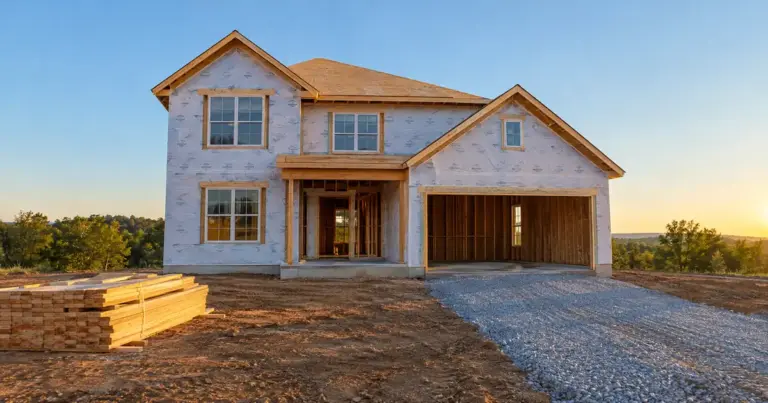
Finance New Construction On 1099 Bank Statement Income — Ground-up construction and permanent financing are two different loans, not one.
Get that classification wrong and the qualifying income figure moves a lot, in either direction.
But it changes what the underwriter checks.
The ARM-versus-fixed choice sits on top of that, as a separate decision about payment behavior after closing.
Most other trust structures — irrevocable trusts, charitable trusts, donor-advised funds — get excluded outright, no partial credit.
Can One Declining Year Of Deposits Sink A Loan-out Bank Statement Loan — No, not automatically.
Picking your LTV means picking a size tier and a credit tier at the same time.
Super Jumbo Bank Statement Loan Sets LTV By Loan Tier — Leverage steps down as the loan gets bigger, not up.
Lenders qualify you on documented deposits, an expense adjustment, and how durable that single-client relationship looks.
A 24-month window smooths the average, which helps a borrower with flat or seasonal income who needs to prove stability over a longer stretch.