DSCR Loan For A Ski-town Rental: Complete Guide
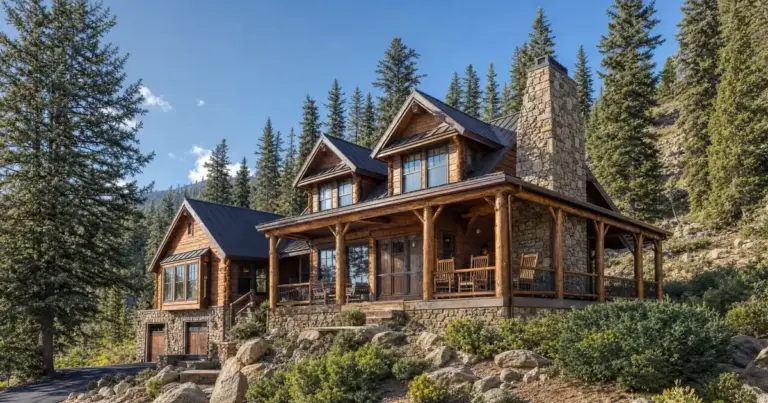
The real risk isn’t the ratio math — it’s confirming the property still has legal permission to operate as a rental once the loan closes.

The real risk isn’t the ratio math — it’s confirming the property still has legal permission to operate as a rental once the loan closes.
Investors who price all three before making an offer avoid the surprises that kill beachfront files late.
What changes is what lands inside that payment before the ratio gets calculated.
Loan sizing runs from $150,000 into the mid-seven figures through select wholesale programs, with leverage stepping down as the loan amount climbs.
DSCR Loans For LLC Borrowers: Complete Guide — LLCs are the default borrower type on DSCR loans, not an exception lenders tolerate.
Underwriting still runs primarily off each property’s own rent-to-payment math, credit tier, and reserve position.
Underwriting checks whether the property’s rent covers its own payment; where you sleep at night never enters that math.
DSCR Loans For Family Offices: Complete Guide — DSCR loans qualify a family office’s rental acquisition on the property’s own rent
The catch at the top of the market isn’t paperwork — it’s yield.
This guide walks through the mechanics, the structures, and the places the general rule breaks.
DSCR Loans For High Net Worth Investors: Complete Guide — A DSCR loan qualifies a rental purchase or refinance on the property’s own
The mechanics shift at each size tier: credit floor, reserve math, appraisal count, and how coverage below 1.00 gets handled.
Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
– LTV (loan-to-value): the loan amount expressed as a percentage of appraised value. Lower LTV means more equity cushion behind the loan.
Loan size runs from $150,000 up to $6,000,000 across the wholesale network Lendmire places files through, with leverage stepping down as the balance climbs.