
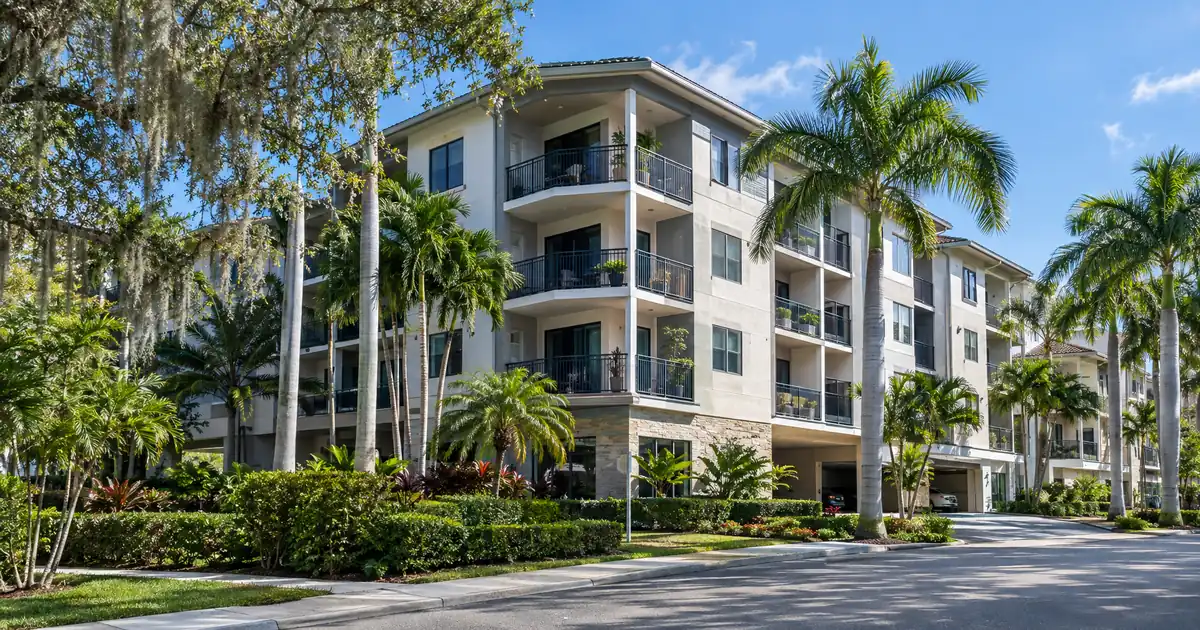
An out-of-state investor scanning Aventura sees the obvious things first: Aventura Mall, a 2.6-square-mile city holding 39,885 residents, and CoStar-sourced average rents of $2,328 a month, well above the national figure. What that investor misses is that the equity they plan to pull out sits inside a high-rise condo, in a market where the citywide median sale price has been falling. The cash-out question here has less to do with how much the rent covers than with what the appraiser says the unit is worth today.
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that arranges DSCR investor loans across 40 states plus Washington, D.C. This piece looks at Aventura from the equity-extraction side, for investors who already own here.
DSCR Cash-Out Calculator
Run the cash-out numbers in Aventura, FL
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
The Short Version:
A DSCR cash-out refinance on an Aventura, Florida investment property is underwritten primarily on the rental income the unit earns measured against its full monthly obligation, with proceeds sized by a loan-to-value ceiling and subject to lender guidelines, appraisal review and condo association documentation rather than the owner’s traditional personal-income documentation.
- Redfin listed 1,233 condos and just 1 multifamily property in a recent month.
- Citywide median sale price has softened noticeably year over year.
- Cash-out caps at 75% LTV after roughly 6 months of ownership.
- Modeled coverage spans roughly 0.65x to 1.2x depending on building tier.
- Building selection matters more than the neighborhood label. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
Aventura Market Snapshot
A quick read on the Aventura investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Home prices | $423,548 average home value (Zillow Home Values) |
| Typical rents | $2,328 avg (Apartments.com Rent Market) |
| Recent appreciation | 4000 williams island +5.2% (LuxLife Miami Blog) |
| Population | 39,885 population (Census Reporter) |
| Employment | 17.5K→17.2K employees (-1.44%) (DataUSA) |
What Does an Aventura Owner Actually Hold?
Almost every Aventura investment property is a condo unit, and that shapes every refinance decision. The for-sale mix shows it: 1,233 condos, 34 townhouses and one multifamily property in a single month, per the Redfin snapshot above. The classic move of stacking four rent rolls against one loan is essentially unavailable inside city limits. Investors who want that structure look at adjacent North Miami Beach, Sunny Isles Beach or Ojus.
The tenant base is real but not driven by a corporate campus. DataUSA shows resident employment slipping 1.44%, from 17.5k to 17.2k workers, with Professional Services, Health Care and Retail Trade the leading sectors. The demand anchors are Aventura Mall (fifth-largest in the country by retail square footage, with 300+ stores) and HCA Florida Aventura Hospital, a 493-bed facility. Per the hospital’s careers page, it employs more than 1,800 colleagues. Both feed workers into the rental pool. About 36% of households rent, so the renter base is meaningful even in an owner-heavy city.
Vacancy is a gap. No dated Census or BLS vacancy figure specific to Aventura turned up, so any vacancy percentage an investor sees quoted should be treated as unverified.
The Appraisal Is the Real Cap
The 75% LTV ceiling matters less in Aventura than the value it gets applied to. Redfin’s citywide median sale price of $428K is down 20.2% from a year earlier, with price per square foot at $339, down 20.0%, and homes selling in around 140 days. Zillow’s average home value of $423,548 is down 6.4%. Homes.com shows a higher $515,000 median, and the gap reflects methodology and how much luxury product each source captures. This article uses the Redfin figure as its citywide anchor. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Upper tiers show the same softness. A local mid-year condo report put the $3M-$6M segment’s months of inventory at close to 29, up from 10, with discounts off original asking widening from 9.6% to 12.4%.
Picture an investor who bought a unit years ago and is counting on an equity number based on last year’s comps. That is the trap. Cash-out proceeds in this market should be modeled on the most recent closed sales, not the peak-era ones. A 6-month seasoning window, measured from title recording, is the program minimum. In a market with widening negotiated discounts, owners with longer holding periods generally have an easier appraisal conversation. The equity-extraction mechanics explain how seasoning and value interact.
Coverage Math by Tier
Coverage in Aventura swings from comfortable to underwater depending on the building tier, and the ultra-luxury end is not where the numbers work. The figures below are modeled assumptions, not sourced market data: a 75% LTV cash-out, full PITIA including taxes and insurance at Florida averages, HOA dues excluded, and every band rounded down. Values and rents come from the cited sources. Exact terms depend on the lender’s guidelines, property type, leverage, and a full review of the borrower’s file.
| Tier | Value / rent used | Modeled coverage |
|---|---|---|
| Williams Island | $1,025,000 / $8,000 | About 1.2x |
| Aventura Estates | $730,293 / $4,810 | About 1.0x |
| Citywide 2BR | $428K / $2,887 | About 1.0x |
| Turnberry Isle | $843,419 / $3,533 | About 0.65x |
Values here come from Homes.com for Williams Island and NeighborhoodScout for Aventura Estates. The Turnberry Isle inputs from NeighborhoodScout are dated, so treat them cautiously. Williams Island rent is the Redfin neighborhood median. The citywide rent is the Apartments.com two-bedroom average of $2,887.
Two cautions. Mixing a median price from one source with a median rent from another is imprecise, and the true building-level number could land either side. And HOA dues, which sit in the obligation for a condo, pull every band lower. Skip any refinance that only clears 1.00x before HOA.
Turnberry Isle is the cautionary case. At roughly 0.65x, the unit doesn’t carry itself on long-term rent. Structures a lender might review include a sub-1.00 program, interest-only restructuring or lower leverage, each subject to lender guidelines, credit approval and property review. The trade-off is reduced proceeds. A 1.00x baseline is common because rent covers the payment at that level, and going lower usually means stronger compensating factors, less leverage or different pricing. The DSCR explainer covers the ratio mechanics.
One Island, Two Personalities
Building selection inside Williams Island matters more than the island label, and the refinance thesis has to be tower-specific. Per a local performance analysis, Bella Maré’s price per square foot climbed from roughly $469 to $1,014, an 115% gain, with about 80% of residences owner-occupied. Nearby 4000 Williams Island has hovered in the mid-$400s per square foot, up only 5.2% in total, with 30% of units leased.
Bella Maré is an appreciation story with a thin rental pool. Equity there is real, but the tenant base is small and the rent roll is hard to benchmark. 4000 Williams Island is the opposite: flatter value, more leased units, and easier rent comps. The inventory data reinforces the split. Bella Maré has averaged 6.8 months of supply, trending near 8. 4000 Williams Island averages 13.5, near 14 currently. The cash-out proceeds at 4000 Williams Island fund the next purchase, but the exit for that unit is slow.
Is a thin-pool, appreciation-led unit better than a flat, well-leased one? It’s a genuine toss-up. Owners who plan to hold and recycle proceeds favor the leased building. Owners who might sell into strength favor the other.
Where Does the Cash-Out Actually Pencil?
The middle tier pencils best on rent-to-value. Redfin’s neighborhood rent breakdown shows a roughly 3.5x spread across submarkets a few miles apart. Point East Condominiums has a median rent of $2,250 and Golden Shores $2,875, while The Waterways sits at $4,234 and Williams Island at $8,000. Apartments.com also flags The Waterways, Admirals Port and Mystic Pointe as the most affordable neighborhoods in the city.
Mid-tier one- and two-bedroom units in those communities carry the best rent-to-basis stack, because purchase prices there haven’t run to seven figures. Price data at the building level is thinner than at the neighborhood level, so exact ratios need current comps. Town Center, per Apartment List, is the walkable, newer-finish district, and it draws professional and retail-hospitality tenants. The best refinance candidates tend to sit in the middle: not Williams Island, but a unit whose rent comfortably clears full PITIA plus HOA.
Condo Paperwork Is the Friction Point
Condo underwriting, more than credit or LTV, is where Aventura files slow down. Most refinances here involve HOA financials, master-policy details and, in some buildings, non-warrantable status. The common friction point in markets like this one is the association questionnaire and budget review, not the borrower. Cleaner files from a documentation standpoint tend to arrive with the HOA package already assembled and a lease in place.
Program guidance is straightforward. Credit tiers start at a 620 floor, reserves run about 6 months of PITIA (about 9 months above $1,500,000, which matters for Williams Island product), and standard programs reach up to $3,000,000. Manufactured homes and barndominiums fall outside these programs, though that rarely matters in a condo city. Vesting in an LLC is common, subject to lender program eligibility. Qualification remains subject to lender overlays.
Where the Proceeds Go
Because Aventura has essentially no duplexes or fourplexes, the equity often has to travel. Investors commonly redeploy proceeds into adjacent submarkets with small multifamily stock. The investment property refinance options and the side-by-side comparison help frame whether a DSCR cash-out beats a conventional refinance for that purpose. Lendmire’s Florida DSCR platform covers the state-level program picture.
Two local wrinkles. A listed West Aventura four-unit development lot, on Homes.com, can by right build up to 45 units and 12 stories. It is an entitlement play, not a stabilized cash-flow deal. Scarce larger houses are also diverging: per Lifestyle Aventura, four-bedroom homes rose 3.9% and five-bedroom homes 14.3% while the broader median fell. Those are appreciation holds, not rent-yield holds. Investors should verify current local rental rules, taxes and insurance, including any association special assessments, with qualified local professionals. To discuss a specific unit, reach Lendmire at 828-256-2183.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance in Aventura?
Qualification centers on the unit’s rent used for lender review against full PITIA, with 1.00 as the standard benchmark, a credit floor of 620 and about 6 months of reserves. The property must also have roughly 6 months of seasoning and fit inside a 75% LTV cap. Condo documentation and appraisal review are reviewed alongside, subject to lender guidelines.
What are the requirements for an investment property loan in Aventura, Florida?
Expect a condo that meets lender review, documented rent, reserves and credit in the tiers noted above. Loan sizes reach up to $3,000,000 on standard programs. Association financials often decide whether the unit fits a given program.
How do DSCR lenders review rental income instead of traditional tax-return income in Florida?
Lendmire arranges DSCR investor loans. Lenders in the network generally review the property’s rent against its obligation rather than the borrower’s personal income documents. That review is subject to lender guidelines and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Aventura, FL. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
Why does falling condo pricing matter for a cash-out here?
Proceeds are sized off appraised value, and Aventura’s median sale price is down 20.2% year over year. A refinance modeled on older comps can come in short. Stress-test against the most recent closed sales in the same building.
Can a Williams Island unit clear coverage?
Sometimes, but building by building. Modeled coverage near 1.2x is possible on high-rent units, though reserves rise above $1,500,000 and tower-level inventory varies widely. It is not a neighborhood-wide answer.
For current guidelines and terms, see Lendmire’s DSCR loan programs page.
About Lendmire
Lendmire (NMLS# 2371349) is a DSCR-focused mortgage broker that helps arrange investor financing across 41 markets, including Washington, D.C., through wholesale and investor-lending channels. DSCR eligibility is generally reviewed by the lender on the property’s rental income rather than personal income documentation, subject to lender guidelines, which works for self-employed investors, LLC operators and portfolios above four financed properties. Scotsman Guide named Lendmire a Top Mortgage Workplace in both 2025 and 2026.
Ask any local appraiser about Aventura and the answer is the same: the tower matters more than the zip code, and a unit priced off last year’s comps is priced off a market that no longer exists.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
1. Census Reporter — Aventura FL
2. Apartments.com — Rent Market Trends Aventura FL
4. Redfin — Aventura Housing Market
5. Zillow — Home Values Aventura FL
6. Luxlifemiamiblog.com — the Best and Worst Performing Condos
7. DataUSA
9. HCA Florida Aventura Hospital
10. careers.hcahealthcare.com — Hca Florida Aventura Hospital
11. RentCafe — Average Rent Market Trends Aventura
12. Homes.com
13. Luxlifemiamiblog.com — the Aventura Condo Market Report Midyear Review
14. Homes.com
17. Redfin neighborhood median
18. Apartment List
19. Homes.com
21. 2025
22. 2026
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Cash Out Refinance Investment Property in Aventura, Florida: The 2026 DSCR Guide to Biscayne Blvd · DSCR Cash Out Refinance in Lauderhill, Florida: The 2026 DSCR Financing Guide to Inverrary · DSCR Cash Out Refinance in Pinecrest, Florida: Can the Rent Support a Cash-Out in Pinecrest?
Guides: Investment Property Cash-Out Refinance in Florida
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Required disclosures. Lendmire (NMLS# 2371349) operates as a licensed mortgage broker, not a direct lender or depository. The discussion in this article is general in nature and should not be relied upon as financial, legal, or tax advice — every investment scenario is unique and should be reviewed by a qualified professional. Any loan inquiry is subject to lender underwriting, and this article is not a commitment to lend or a guarantee of approval. Mortgage rates, loan terms, and program guidelines vary by borrower, property, and state, and may change without notice. Equal Housing Opportunity. Verify licensure at NMLS Consumer Access.