
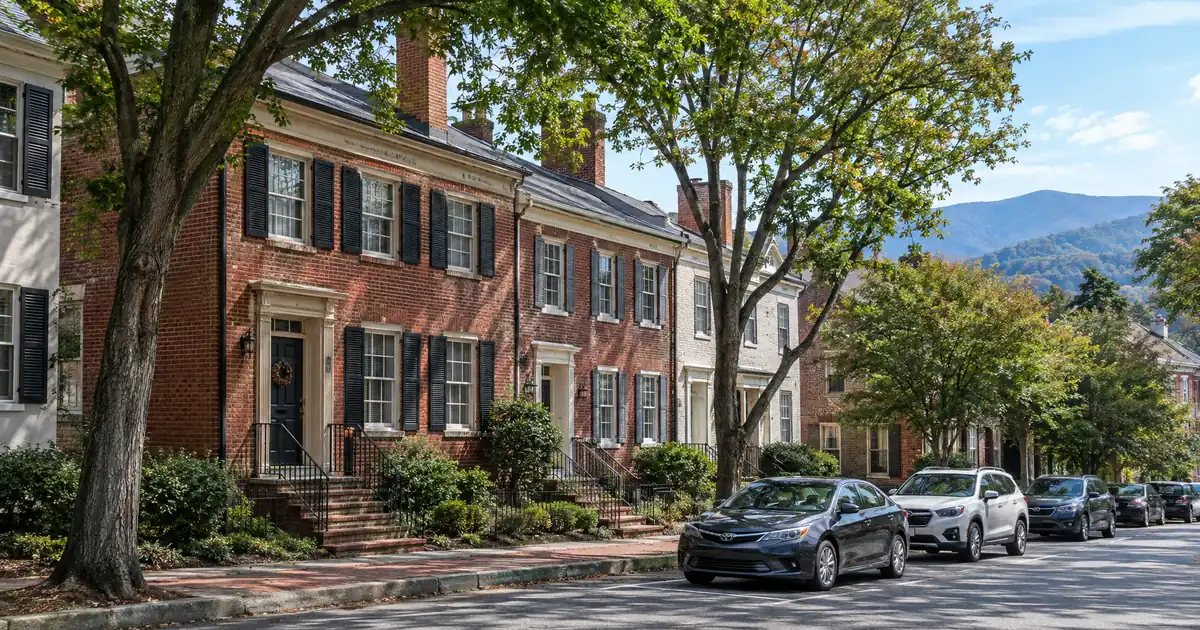
A rental in Hethwood hits the DSCR math like this. Say you own a three-bedroom house valued near the $389,000 Hethwood–Prices Fork single-family median, leased at the $2,198 median house rent Zumper reports for town. Run a cash-out at the 75% LTV ceiling with taxes and insurance counted in the full obligation, and coverage lands in the mid-0.9s (modeled assumptions, not a quote). Just shy of 1.00. That near-miss explains most of what matters about pulling equity out of Blacksburg property. Every figure here varies by lender and program — guidelines, property type, leverage, and credit profile all apply.
The Quick Read: A cash-out refinance on a Blacksburg, Virginia rental is underwritten primarily on the property’s rental income measured against its full monthly obligation, so the process runs from an appraisal-backed value and six months of title seasoning through a rent schedule, reserves review and lender placement, with proceeds sized against a 75% LTV ceiling. Final terms depend on lender guidelines, property type, leverage, and the borrower’s complete credit picture.
DSCR Cash-Out Calculator
Run the cash-out numbers in Blacksburg, VA
Rate source: Freddie Mac 30-yr average via FRED® — Federal Reserve Bank of St. Louis · effective Sep 24, 2026
Prefilled with starting assumptions — enter your property’s value, balance, taxes, and insurance for a more accurate picture.
Program parameters update from Lendmire’s centralized guideline source. Taxes and insurance are editable estimates.
As of Sep 24, 2026 · General Freddie Mac market benchmark, not a Lendmire loan offer. Property value, balance, taxes, and insurance are editable estimates. Maximum loan-to-value varies by lender, program, property type, and seasoning. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
- Single-family at the town median sits near or under 1.00 coverage once taxes and insurance are counted.
- Duplexes and small multifamily are where coverage clears 1.00 with room to spare. Virginia Tech’s official enrollment of 38,995 anchors long-term rental demand.
- A new 862-bed building on North Main pressures per-room rentals near campus.
- Appreciation is flat to modest, so equity comes mostly from basis and improvements.
For real estate investors in Blacksburg, Virginia, Lendmire helps structure and place DSCR financing through wholesale lenders operating in 41 markets, including D.C. Lendmire is NMLS# 2371349, a DSCR-focused mortgage broker. This article assumes you already own the property. The question is what the equity can do for you next.
Blacksburg Market Snapshot
A quick read on the Blacksburg investor landscape — figures come from the cited sources below. Confirm current property-level numbers before underwriting.
| Metric | Detail |
|---|---|
| Typical rents | $2,313 avg (RentCafe/Yardi Matrix rent) |
| Cap rates | 5.4% cap rate (CapRateCity Blacksburg) |
| University enrollment | ~39,000 students (Virginia Tech Facts) |
Hethwood–Prices Fork: The Best Starting Point
Hethwood–Prices Fork is the strongest Blacksburg submarket for pulling equity, because the basis is low relative to rent. The $389,000 single-family median compares with $599,900 in Tom’s Creek and $400,000 downtown. Listings describe Hethwood as the neighborhood non-student tenants prefer, near Heritage Community Park and the Huckleberry Trail. That means staff, workforce and non-student renters on more conventional lease terms, with less pure student-calendar risk.
The catch is that plain single-family still struggles here. CapRateCity, working from Zillow indices, puts the town’s rent-to-price ratio at about 0.6%, well under the 1% rule. It estimates a 5.4% cap rate and says investors need below-median or value-add product. A Hethwood house at the median with median rent lands in the mid-0.9s at full 75% cash-out leverage. Some lenders review sub-1.00 files, but standard programs are built around a 1.00 benchmark. Sub-1.00 usually means lower leverage, stronger credit, more reserves and closer lender review.
If your Hethwood house sits just under 1.00, you have three levers. Take less cash out and the coverage number improves. Raise documented rent through a renovation or a re-lease. Or ask whether a sub-1.00 program at a select lender fits your credit and reserve profile. Qualification stays subject to lender guidelines, credit approval and property review.
Where Do Duplexes Change the Math?
Small multifamily is the cleanest way to lift coverage in Blacksburg. Apartments.com puts average rent at $1,489 for a two-bedroom and $1,848 for a three-bedroom. Those are averages across all apartments, not duplex-only, so treat them as a guide. Two 2BR sides would gross about $2,978 a month (my arithmetic, not a sourced figure). That’s roughly 35% more than the $2,198 house median before you compare purchase prices.
Run the numbers on a modeled duplex valued at $400,000, a stand-in and not a market quote. At a 75% cash-out LTV with taxes and insurance in the obligation, coverage lands around 1.2x. The same $400,000 in a single-family house would sit well below that. Verify actual duplex values against current comps before relying on this. These specifics are subject to lender guidelines and a full review of property, leverage, and credit.
DSCR files in markets like this one typically look the same. The rent schedule and the appraisal do most of the work, and reserves are the quiet gatekeeper. Owners with a single-family that barely misses 1.00 often do better refinancing the small multifamily in their portfolio first and leaving the marginal house alone. Lenders want to see documented leases, current rents that match market, and about six months of PITIA in the bank. Above $1,500,000 the reserve ask rises to about nine months.
Skip Tom’s Creek for Cash Flow
Tom’s Creek carries the highest medians in town, $599,900 for single-family, and the weakest ratio. At that basis a house renting near the town median produces coverage in the low 0.6s at full leverage, even with taxes and insurance treated generously. It’s a premium tier for owner-occupants and faculty, and it’s a poor place to build a DSCR cash-out thesis.
Downtown and the North Main student core deserve a more careful read. The $400,000 downtown median is workable, and the walkable blocks near the Lyric Theatre and Moss Arts Center rent reliably. Then there’s supply. WDBJ reports that the Rambler on North Main will bring 247 units and 862 beds, and construction is expected to run for the next few years. Roughly 860 new purpose-built beds compete most directly with per-room rentals in the downtown and North Main core. If you hold room-by-room rentals there, underwrite higher concessions and some extra vacancy before you count on a rent bump for the appraisal.
The Demand Story Is Real
Virginia Tech is the demand engine. The university reports nearly 39,000 students on and off campus in a town of 45,446 residents per the Census Reporter ACS profile, and RentCafe’s Census-based figures show 64% of households rent. The fall census showed a first-year class of 7,088 from a record 57,700 applicants, with first-year retention at 94.7%. Applications and retention at highs support rent durability, and that helps at appraisal.
Growth has a ceiling, though. Cardinal News reports that Tech is reaching its geographic limits in Blacksburg, which will cap incoming class sizes. Underwrite flat-to-modest rent growth. Sources show anywhere from roughly 3% to 6% year over year, and none of them promise student-driven upside.
There’s a non-student layer too. The New River Valley Regional Commission ranks Virginia Tech first among regional employers, followed by Volvo Group North America, the Montgomery County School Board, Radford University and Carilion New River Valley Medical Center. The Virginia Tech Corporate Research Center houses 220 companies per the university’s facts page, which feeds a professional renter pool. The Carilion medical center in nearby Christiansburg adds healthcare staff. That’s the tenant base for workforce single-family and townhouses outside the student core. Christiansburg and Radford offer lower basis near I-81, though this research found no sourced price data for either.
Appreciation Is Flat: Equity Comes From Basis
Blacksburg equity rarely comes from price momentum. Zillow shows a $418,961 average home value, up 0.5% over the past year, while CapRateCity cites roughly 2.9% annualized. Call it flat to modest growth.
Sources disagree on the citywide median. This article uses Homes.com‘s $445,000 to stay consistent with its neighborhood medians. Houzeo puts the median lower, at $335,000, on a different methodology. Ignore any forecast that shows triple-digit gains. It’s a data artifact.
The honest read: if you bought at or near market and the appraisal comes back flat, 75% LTV on that value leaves limited proceeds after the existing balance. The owners who pull meaningful equity bought below market, added a bedroom or unit, or held long enough for basis to fall behind value. Proceeds also depend on rent used for lender review, reserves and the 75% ceiling, so they aren’t a guaranteed cash figure. Terms vary by lender guidelines, property type, leverage, credit profile, and full file review.
Seasoning, LTV and What the Proceeds Do
The cash-out mechanics are simple, and the details matter. Cash-out refinances are capped at 75% LTV, not the 80% purchase figure. Seasoning runs about six months of ownership, measured from title recording. Minimum coverage on standard programs is 1.00 on rent used for lender review against full PITIA. Credit tiers run 620, 660, 680 and 700, with 620 as the floor, and loan amounts go up to $3,000,000 on standard programs. Program terms are guidelines that vary by lender, and none of this is a commitment to lend.
Ownership in an LLC works with many DSCR programs, subject to lender program eligibility. Manufactured homes, log homes and barndominiums sit outside these programs. That rarely matters for Blacksburg’s townhouse, duplex and condo stock, but it can affect outlying rural parcels.
Condos deserve a mention. At $210,000 for one-bedrooms and $248,800 for two-bedrooms, entry basis is low. HOA dues reduce net income, and rental caps in the HOA documents can shut the door entirely. Read the governing documents before you count on a condo as a refinance candidate.
Where do the proceeds go? Investors here commonly use cash-out to fund the next lower-basis unit, whether a duplex or a townhouse outside the student core, or to renovate an existing property into a higher rent tier. That’s one property’s equity becoming down payment on the next. The cash-out refinance walkthrough covers the mechanics, the guide “What Is a DSCR Loan” explains the coverage test, and the program-to-program comparison shows how these programs stack up against conventional refinancing. A look at investor refinance options covers the rate-and-term alternatives.
Student leases turn over annually, so occupancy risk clusters in summer. A file that shows leases in place through the summer months reads better than one showing vacancy at the wrong time. For any local rental rules, taxes and insurance, verify current details with qualified local professionals.
One judgment call is genuinely close. A house-hacked four-bedroom near campus might gross well above the town median if leased by the bed, but the pricing basis for per-bed listings isn’t always clear, and the new North Main supply cuts against it. The steadier play may be the Hethwood-area duplex or townhouse aimed at staff, though investors chasing higher gross rent could argue the other way.
If you’re weighing a Blacksburg cash-out, Lendmire’s Virginia DSCR loan programs page lays out how the platform approaches the state. Investors can also call 828-256-2183 to talk through a specific file.
Frequently Asked Questions
How do you qualify for a DSCR cash-out refinance on a Blacksburg rental?
Qualification rests mainly on the property’s rent against its full obligation, including taxes and insurance, with 1.00 as the standard benchmark. Lenders also review credit, reserves and a current appraisal. On most files the property needs about six months of seasoning before cash-out. At the median house rent and a median Hethwood value, coverage at full leverage sits under 1.00, so many owners lower the LTV or look at multi-unit product. Final eligibility depends on lender guidelines and property review.
DSCR vs. conventional financing
Two common ways to finance an investment property in Blacksburg, VA. They qualify you differently — here’s how investors weigh them.
Why investors choose it
- Qualifies on the property’s rental income — no personal tax returns, W-2s, or pay stubs needed to document income.
- No personal debt-to-income ceiling to clear, so existing mortgages and obligations don’t cap your borrowing the same way.
- Can be closed in an LLC, keeping the property inside a business entity.
- Built for scaling — not held to the limit on number of financed properties that conventional financing applies.
- Underwriting centers on the deal: generally qualifies when the rent covers the payment, a 1.00x coverage ratio being a common baseline (confirmed in underwriting).
- Designed specifically for investment property, including long-term and, where the program allows, short-term rentals.
Where it’s strong
- Often the lowest ongoing financing cost for a buyer who fully qualifies on personal income — a fit for a first property or a cost-first purchase.
Trade-offs for investors
- Requires full personal income documentation and must fit within a debt-to-income limit — salary, existing debts, and other mortgages all count.
- Typically held in your personal name rather than a business entity.
- Caps how many financed properties you can carry, which can become a ceiling as a portfolio grows.
- Evaluates you as a borrower as much as the property, which usually means more paperwork.
How investors usually choose: a first or single property often optimizes for the lowest financing cost; portfolio builders often optimize for leverage, vesting in an LLC, and scaling past conventional caps. The right answer depends on your goals, the property, and current guidelines — both paths run through select lenders in Lendmire’s wholesale network, with eligibility and terms confirmed in underwriting.
What are the requirements for an investment property cash-out refinance in Blacksburg, Virginia?
Expect a 75% maximum LTV, about six months of ownership measured from title recording, a credit floor of 620 with better tiers at 660, 680 and 700, and reserves of about six months PITIA. Programs generally cover up to $3,000,000. Property types like duplexes, townhouses, condos and single-family are typical fits, while manufactured homes, log homes and barndominiums are not. Guidelines vary by lender and borrower.
Does a student-heavy tenant base make Blacksburg harder to refinance?
Not by itself, but it shapes the file. Lenders look at lease terms, rent documentation and how the property performs across the academic calendar. With roughly 64% of households renting and Virginia Tech enrolling 38,995 students, demand is deep, though annual leases concentrate turnover in summer. Properties near the new North Main supply may draw closer review of vacancy and concessions.
Which Blacksburg property types give cash-out the best chance of working?
Duplexes through fourplexes, and townhouses or houses in Hethwood aimed at non-student tenants, tend to pencil best. Single-family at the town median sits near a 0.6% rent-to-price ratio, so coverage is tight. Tom’s Creek’s $599,900 median makes cash flow especially hard. Outcomes depend on the actual rent, value and program review.
What loan-amount ranges may DSCR lenders review for Blacksburg rental properties?
Lendmire arranges DSCR investor loans. Standard programs generally run up to $3,000,000, and smaller balances route through select lenders in the network. Most Blacksburg rentals, from condos near $210,000 to houses under $600,000, fall comfortably inside that range.
What Happens Next
Blacksburg pays owners who pair a student-town demand base with a lower-basis, multi-unit property and modest growth expectations. It punishes anyone who treats a premium single-family as a cash-out engine. The next step is a straight read of your own coverage number, at your own rent and your own value. Is your equity sitting in a property that clears 1.00, or one that’s waiting for a better structure?
About Lendmire
Lendmire (NMLS# 2371349) is a mortgage brokerage built around DSCR investor lending, with programs available in 41 markets, including Washington, D.C. DSCR lenders commonly evaluate rental-income coverage instead of personal income paperwork, which is a practical fit for LLC-owned and multi-property investors. Terms vary by lender, property, leverage and program. Lendmire is a 2026 Scotsman Guide Top Mortgage Workplace and was a top-ranked workplace in 2025. To discuss a file, request a scenario review.
Get Started
Ready to find the right loan for you?
In about 30 seconds you can review financing options available for your investment property. No commitment required.
Informational only. Not a Loan Estimate, approval, or commitment to lend. Program availability and eligibility are subject to lender guidelines, credit approval, property review, and underwriting.
References
2. Zumper — Rent Research Blacksburg VA
3. Virginia Tech’s official enrollment of 38,995
4. RentCafe — Average Rent Market Trends Blacksburg
5. CapRateCity
8. WDBJ7: Rambler construction
9. Census Reporter — Blacksburg VA
10. Cardinal News: Virginia Tech enrollment
11. New River Valley Regional Commission: Largest Employers
13. Zillow
14. a 2026 Scotsman Guide Top Mortgage Workplace
15. Scotsman Guide — Top Workplaces 2025
This article is part of Lendmire’s investment property cash-out refinance program — full qualification details, guidelines, and scenarios live on the program page.
Related reading: Luxury Rental DSCR Loans In New Jersey · Jersey Shore Vacation Rental Loans: DSCR Financing In Ocean City, Cape May And Long Beach Island · DSCR Cash-out Refinance In New Jersey: Pulling Equity From A Rental
Guides: Investment Property Cash-Out Refinance in Blacksburg, VA · Investment Property Cash-Out Refinance in Virginia
Brandon Miller
Founder & CEO, Mortgage Loan Originator, Lendmire LLC
- Mortgage Loan Originator · NMLS# 1129696 · Verify on NMLS Consumer Access
- North Carolina Real Estate Broker · License# 343312 · Verify on NCREC
- North Carolina Insurance Producer · License# 19053198 · Property, Casualty, Life, Health · Verify on NAIC SBS
- Lendmire LLC · Firm NMLS# 2371349 · Verify firm licensure
Compliance and disclosures. Lendmire (NMLS# 2371349) is a licensed mortgage broker and is not a direct lender, depository institution, financial advisor, or tax professional. Content in this article is general market analysis and educational information — not financial, legal, or tax advice for any specific situation. Lendmire does not guarantee loan approval; every transaction is subject to underwriting by the funding lender. Mortgage pricing and loan program guidelines are subject to change at any time without notice and vary by borrower characteristics, property type, and state regulations. Lendmire complies with Equal Housing Opportunity. Licensure verification: NMLS Consumer Access.